

What Are the Tax Consequences of Changing Jobs Mid-Year?
Last reviewed: July 2026
Changing jobs mid-year can trigger under-withholding, an accidental 401(k) over-contribution, and a surprise tax bill the following April. The core problem is that each employer calculates withholding as if you worked there all year, so they never see your combined income. The tax implications of switching jobs are manageable, but only if you check your numbers before December, not after you file.
Key Takeaways
- Each employer withholds taxes as if you earned that salary for the full year, which often leaves mid-year job changers under-withheld.
- The 2026 employee 401(k) deferral limit is $24,500 and applies per person, not per employer.
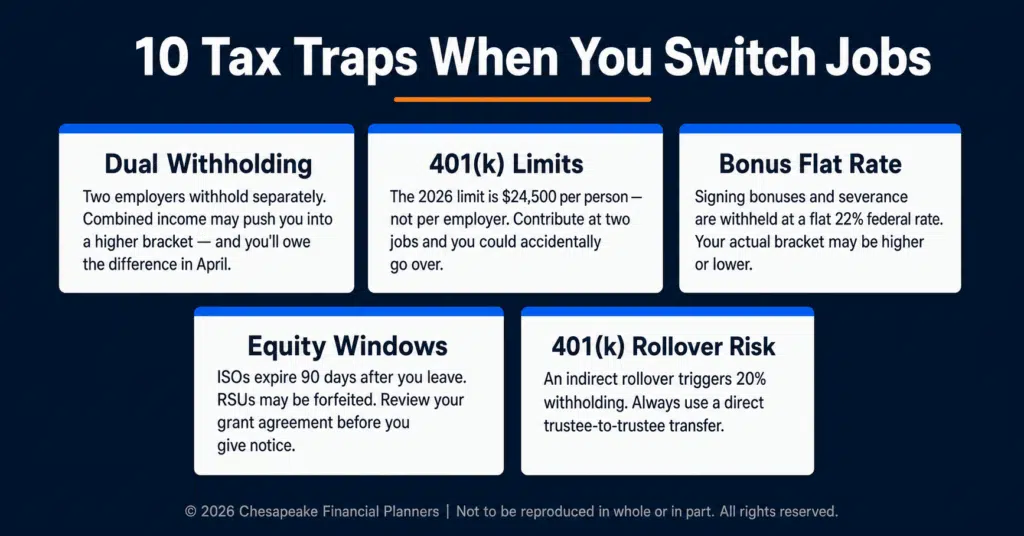
- Bonuses and severance are typically withheld at a flat 22% supplemental rate, which may not match your real bracket.
- Leaving before equity vests can forfeit unvested RSUs and shorten the window to exercise stock options.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate job transitions and the tax messes they create since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff sees the same pattern every spring: a client took a great new job, never touched their W-4, and walked into a four-figure tax bill they could have prevented in ten minutes.
A new job usually means more money. It also means two W-2s, two payroll systems, and two sets of tax assumptions that don't talk to each other. Below are the issues that actually cost people money, plus what to do about each one.
Why Does Switching Jobs Cause a Tax Surprise?
When you change jobs mid-year, both employers run payroll withholding based on annualized income. Your old job withheld as if you would earn your old salary for twelve months. Your new job does the same with your new salary. Neither one knows about the other.
Say you earned $40,000 at your first job over six months, then $50,000 at the second over the back half of the year. Your total income lands around $90,000, but each employer withheld as though you sat in a lower bracket all year. Combined, you may have pushed into a higher marginal rate that nobody withheld for.
The IRS Tax Withholding Estimator is the fix here. Run it after you start the new job, then submit an updated Form W-4 to your new employer. Jeff's rule with clients: do this in the same week you fill out new-hire paperwork, while you're already thinking about it. Wait until November and you've already missed most of the year's withholding.
Can You Over-Contribute to a 401(k) by Changing Employers?
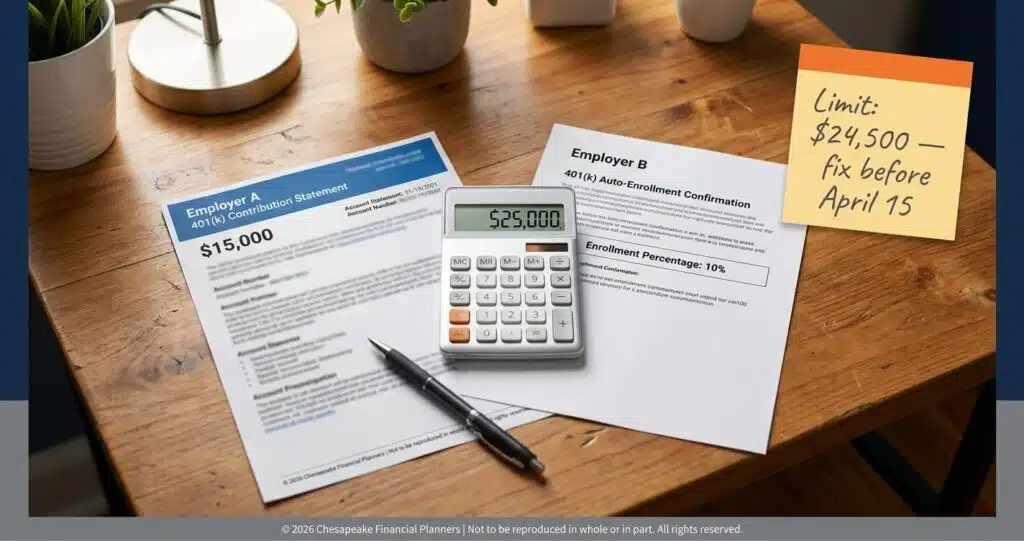
Yes, and it happens more than people think. The 401(k) employee contribution limit is per person, not per plan. For 2026, that employee deferral limit is $24,500, with an additional $8,000 catch-up if you're 50 or older.
Here's the trap. You contributed $15,000 at your first job through June. Your new employer auto-enrolls you at 10%, and by year-end you've added another $10,000. That's $25,000 against a $24,500 limit, and your new payroll system had no idea what you already contributed elsewhere.
Excess deferrals get taxed twice if you don't catch them: once in the year you contributed and again when you eventually withdraw. You have to pull the excess out by the April deadline to avoid that double hit. The cleaner move is to track your running total and dial down the contribution percentage at the new job so you never cross the line. If you want the bigger picture on coordinating retirement accounts during a transition, the What are all my options when rolling over or withdrawing from an old 401(k)? guide walks through it.
How Are Bonuses and Severance Taxed When You Switch Jobs?
Bonuses, signing bonuses, and severance are usually treated as supplemental wages and withheld at a flat 22% federal rate (37% on amounts above $1 million in a year). That flat rate is a withholding shortcut, not your actual tax.
If your marginal rate is 32% or 35%, a 22% withholding leaves you short, and the gap shows up as a bill at filing. If your marginal rate is 12%, you over-paid and you'll get it back as a refund, which is really just an interest-free loan you handed the government for a year.
Know your real marginal rate before you spend the bonus. If you're under-withheld on a large payout, make an estimated payment rather than waiting and hoping. The difference between your effective and marginal tax rate trips up a lot of people here, and the What Is the Difference Between Marginal and Effective Tax Rate? post clears it up.
What Happens to Your Stock Options and RSUs When You Leave?
Equity compensation is where job changes get expensive fast. Leaving before shares vest can mean forfeiting unvested RSUs entirely, and it usually starts a clock on any vested stock options you hold.
Most option plans give you a short window after your last day, often 90 days, to exercise vested options before they expire. Exercising can create a taxable event, and incentive stock options can drag you into the alternative minimum tax in the exercise year. RSUs that vest on your way out are taxed as ordinary income at vest, and that income stacks on top of your regular wages.
Before you accept a new offer, get your equity vesting schedule in writing and map out what you keep versus what you walk away from. Jeff has watched clients leave six figures of unvested stock on the table because they timed a resignation three weeks before a vest date. For the details on planning around vesting, see How Do I Avoid Surprise Tax Bills When My RSUs Vest?.
A Framework for Handling a Job Change Cleanly
At Chesapeake Financial Planners, we walk clients through transitions using the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. A job change touches the first three steps hard: review your combined income and withholding, uncover the equity and 401(k) details, then design the W-4 and estimated-payment plan before year-end. Getting ahead of What is a year-round tax planning calendar for retirees and pre-retirees? is the difference between a smooth transition and an April surprise.
Frequently Asked Questions
Will I owe taxes if I change jobs in the middle of the year?
You might. Because each employer withholds as if you earned that salary all year, your combined income can land in a higher bracket than either job withheld for. Run the IRS Tax Withholding Estimator after starting the new job and update your W-4 to close the gap before year-end.
How do I avoid over-contributing to my 401(k) after switching employers?
Track your total employee deferrals across both jobs against the per-person limit. For 2026, that limit is $24,500, plus an $8,000 catch-up if you're 50 or older. Lower your contribution percentage at the new job so the combined total stays under the cap, since new payroll never sees your prior contributions.
Why was my bonus taxed so high when I started a new job?
Bonuses and signing bonuses are usually withheld at a flat 22% supplemental wage rate, which can feel high or low depending on your bracket. If your marginal rate exceeds 22%, you may actually owe more at filing. Know your real rate and make an estimated payment if you're under-withheld on a large payout.
What happens to my unvested RSUs and stock options if I quit?
Unvested RSUs are typically forfeited when you leave, and vested stock options usually must be exercised within a short window, often 90 days, before they expire. Exercising can trigger taxes, and incentive stock options may create alternative minimum tax exposure in the exercise year. Confirm your vesting schedule before resigning.
Do I need to make estimated tax payments after changing jobs?
You may, if your combined withholding falls short of your actual tax liability. This is common when two employers each under-withhold or when a bonus is withheld at the flat 22% rate. Estimating your shortfall mid-year and paying quarterly helps you avoid both a surprise bill and an underpayment penalty.
Does changing jobs affect my tax bracket?
Indirectly, yes. Your tax bracket is based on total annual income, not per-job income. A mid-year move to a higher salary can push your combined income into a higher marginal bracket, even though neither employer withheld at that rate. Your effective rate is what ultimately matters, and it averages across all your income.
Take the Next Step
A clean job change comes down to checking three numbers before December: your combined withholding, your total 401(k) contributions, and your equity vesting dates. If you want a simple way to stay ahead of every tax move tied to a major life change, download our tax planning guide at chesapeakefp.com and put a plan around your transition before the next April surprise finds you.
Want to go deeper? Our Tax Strategy Readiness Quiz walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


