
How Do I Plan for Retirement When My Wealth Is Tied Up in My Business?
Last reviewed: July 2026
Retirement planning for business owners starts with one hard truth: if most of your net worth sits inside a single company you can't easily sell, you don't yet have a retirement plan. You have a bet. The fix is to build liquid, diversified wealth outside the business over time, so your retirement doesn't depend on a sale closing at the right price on the right day.
Key Takeaways
- Most business owners hold 70-90% of their net worth in one illiquid asset, creating concentration risk no employee would tolerate.
- A Solo 401(k) lets owners contribute up to $72,000 in 2026, or more with catch-up provisions.
- Aim to hold at least 30-40% of your net worth outside the business within ten years of retirement.
- A business that runs without you is worth 30-50% more and gives you exit options beyond a forced sale.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement planning for business owners since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched too many owners treat "the business will fund my retirement" as a plan, then scramble when a buyer walks. The owners who retire comfortably are the ones who started pulling cash out years before they ever listed the company.
Why Is "The Business Will Fund My Retirement" Such a Risky Plan?
The business-as-pension plan is risky because it requires a long chain of events to all go right at once, and you control almost none of them. You must stay healthy enough to keep running it. The business must hold its value in a changing industry. You must find a qualified buyer who has cash and motivation. The deal must actually close. And the proceeds must be enough after taxes, fees, and debt payoff.
That last point surprises people the most. A $2 million sale can become roughly $1.2 million after capital gains taxes, transaction fees, and paying off business debt. According to the IRS, the sale of a business is generally treated as the sale of individual assets, which can mix ordinary income and capital gains rates. Jeff often tells clients that the number on the offer sheet is not the number that lands in your bank account, and the gap is bigger than most owners expect.
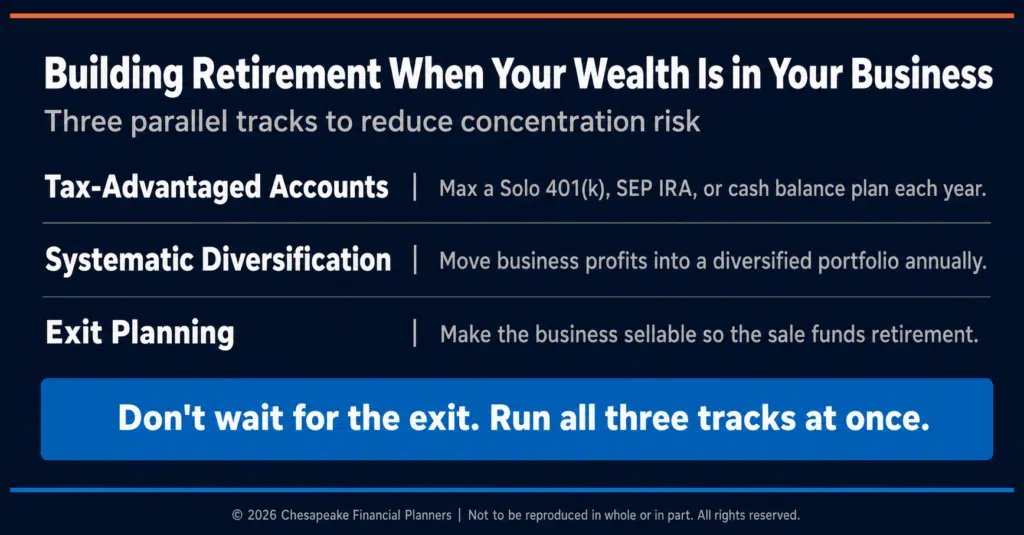
This is why business exit planning has to start a decade early, not the month you decide you're done. Diversification is the whole game.
How Do I Build Liquid Retirement Accounts as a Business Owner?
You build liquid retirement accounts by maxing out tax-advantaged contributions every year, regardless of how the business is doing. These accounts become your retirement floor, completely independent of what the company is worth.
For most owners, the Solo 401(k) does the heavy lifting. According to the IRS, a one-participant 401(k) combines employee deferrals with employer profit-sharing contributions. For 2026, total contributions can reach $72,000 for owners under 50, $80,000 for those 50 and older using the standard catch-up, and $83,250 for owners ages 60 through 63 under the enhanced catch-up rules created by SECURE 2.0. A SEP IRA allows up to $72,000 in 2026 based on 25% of compensation, per the IRS.
Here's the math that makes the case. Contributing $60,000 a year for 15 years at a 7% assumed return grows to roughly $1.6 million, none of it tied to your business value. The excuse Jeff hears most is "I need every dollar for growth." Treat retirement contributions like rent or payroll: a non-negotiable expense. If you want to weigh this against other priorities, see our breakdown of Should I max out my 401(k) or invest somewhere else?.
How Do I Move Excess Cash Out of My Business Tax-Efficiently?
You move excess cash out by systematically extracting profit beyond what operations and growth require, then investing it in accounts you own outside the company. Once the business is stable, this is how you build the diversified base that protects you.
| Strategy | How It Works | Best For |
|---|---|---|
| S Corp distributions | Take distributions after a reasonable salary; no additional self-employment tax | S corporations with steady profit |
| Qualified dividends | C corp dividends taxed at favorable long-term rates fund outside investing | Profitable C corporations |
| Taxable brokerage investing | Invest extracted cash in a diversified, liquid portfolio | Every owner building outside wealth |
The target: work toward holding at least 30-40% of your net worth outside the business by the time you're ten years from retirement. Picture a business worth $2 million, $800,000 in retirement accounts, and $500,000 in taxable accounts. That's $3.3 million total, with 39% outside the company. You are no longer trapped by a single illiquid asset. This is where business owner wealth diversification stops being a slogan and starts being a balance sheet.
How Do I Make My Business Sellable Without Me?
You make your business sellable by reducing its dependency on you, which raises both its value and your number of options. A company that needs the owner for every decision is hard to sell and easy to lowball.
Four moves matter most. Hire key managers so someone other than you runs sales, operations, and finances. Document everything, moving customer relationships, vendor contacts, and pricing logic out of your head and onto paper. Build repeatable systems instead of personal heroics. And develop a strong number-two leader buyers can rely on after you leave. A business that runs without you can be worth 30-50% more, and it lets you step back gradually instead of selling under pressure. This is the heart of business succession planning, and it pairs naturally with a broader What is the best order to withdraw from my 401k, Roth IRA, and taxable accounts in retirement? once the proceeds are in hand.
What Are My Exit Options If a Sale Isn't Optimal?
Your exit options widen dramatically once you have wealth outside the business, because you no longer need a sale to retire. That liquidity is what gives you leverage.
You can keep the business and hire a CEO, collecting distributions while someone else runs daily operations. You can do a partial sale, selling 60-70% to a strategic buyer or private equity firm while keeping income and some upside. An ESOP lets you sell to employees over time with tax advantages and preserved culture, as described by the Department of Labor. Or you can pass the business to the next generation if they genuinely want it and you've built separate retirement wealth. Without outside liquidity, none of these doors open. With it, you choose.
This is the same principle behind the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Owners who run a structured process build options early instead of negotiating from weakness later. If you want to see how the pieces connect, What Life Events Should Trigger a Financial Plan Review? covers selling a business directly.
Frequently Asked Questions
How much of my net worth should be outside my business before I retire?
Aim to hold at least 30 to 40 percent of your net worth in liquid assets outside the business by the time you are ten years from retirement. That balance protects you if the business sells for less than hoped or takes years to sell, and it gives you genuine retirement income that does not depend on a closing date.
Can I contribute to a Solo 401(k) and a SEP IRA at the same time?
You generally should not run both for the same business, because contribution limits coordinate and a SEP can reduce your Solo 401(k) employer space. For 2026, a Solo 401(k) usually allows higher total contributions for owners over 50 thanks to catch-up rules. Most owners pick the Solo 401(k) and skip the SEP to maximize tax-advantaged savings.
What happens to my retirement if my business doesn't sell?
If your business does not sell, your retirement still works as long as you built liquid wealth outside it. Owners with substantial retirement and taxable accounts can hire a CEO, take distributions, pursue a partial sale, or simply wait for a better offer. Owners with everything tied up in the business have no choice but to keep working or accept a discount.
Is a cash balance plan worth it for a business owner?
A cash balance plan can be worth it for owners aged 45 and up with strong, stable profits who want to contribute well beyond 401(k) limits. These defined benefit plans allow large annual contributions that grow with age, accelerating diversified savings outside the business. They add administrative cost and require consistent funding, so they fit established, profitable companies best.
How do taxes affect what I actually keep from a business sale?
Taxes can reduce a business sale meaningfully because proceeds may be split between capital gains and ordinary income, and you still owe transaction fees and any remaining debt. A $2 million sale can net closer to $1.2 million after these costs. Planning the structure years ahead, with your CPA and advisor, protects more of the proceeds for retirement.
Ready to Stop Betting Your Retirement on One Outcome?
Retirement planning for business owners is about building options long before you need them, so the business sale becomes a bonus rather than a requirement. At Chesapeake Financial Planners, Jeff Judge and the team work through diversification, exit strategy, and tax-efficient wealth extraction with owners across Harford County and the Baltimore metro every week. Schedule a free fit call at chesapeakefp.com and let's build the floor under your retirement.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


