
Should I Relocate to Another State for Retirement Tax Savings?
Last reviewed: July 2026
Sometimes, yes — relocating for retirement taxes can save a high-income retiree tens of thousands of dollars over a 25-to-30-year retirement, but only when income tax savings outweigh higher property, sales, or estate taxes in the new state. The right answer depends on your income sources, your home value, and how you spend. Moving from Maryland to Florida looks great on a tax spreadsheet. Moving from Maryland to a high-property-tax state with no income tax might be a wash.
Key Takeaways
- Nine states levy no state income tax, but several recover that revenue through higher property or sales taxes.
- Maryland fully exempts Social Security from state income tax and offers a pension exclusion for eligible retirees.
- High-income retirees with paid-off, modest homes benefit most from no-income-tax states.
- As of 2026, federal Social Security taxation still applies regardless of which state you move to.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement relocation taxes since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched clients move for a "no income tax" headline only to discover their property tax bill doubled, so he always runs the full tax picture before anyone calls a mover.
What State Taxes Actually Matter When You Retire?
Retirement relocation taxes are not one number. They are a stack of separate taxes that hit retirees differently than working households. A retiree drawing down IRAs and collecting Social Security has a different tax profile than a 45-year-old with a W-2 paycheck, so the state that's cheapest for your neighbor may not be cheapest for you.
Four categories drive the decision:
- Income tax: Some states tax nothing, some exempt retirement income specifically, and some tax every dollar of your pension and IRA withdrawals.
- Property tax: Often a retiree's largest annual tax once the mortgage is gone. According to the Tax Foundation, effective property tax rates vary widely by state and can erase income tax savings entirely.
- Sales tax: Hits daily spending. Many states exempt groceries and prescriptions, which softens the blow for retirees.
- Estate and inheritance taxes: Only a handful of states impose these, but they matter for legacy planning. The IRS levies a separate federal estate tax above its exemption threshold.
The mistake Jeff sees most often is chasing the income tax headline while ignoring the other three. A state with no income tax that doubles your property tax bill has not saved you anything.
Which States Have No Income Tax for Retirees?
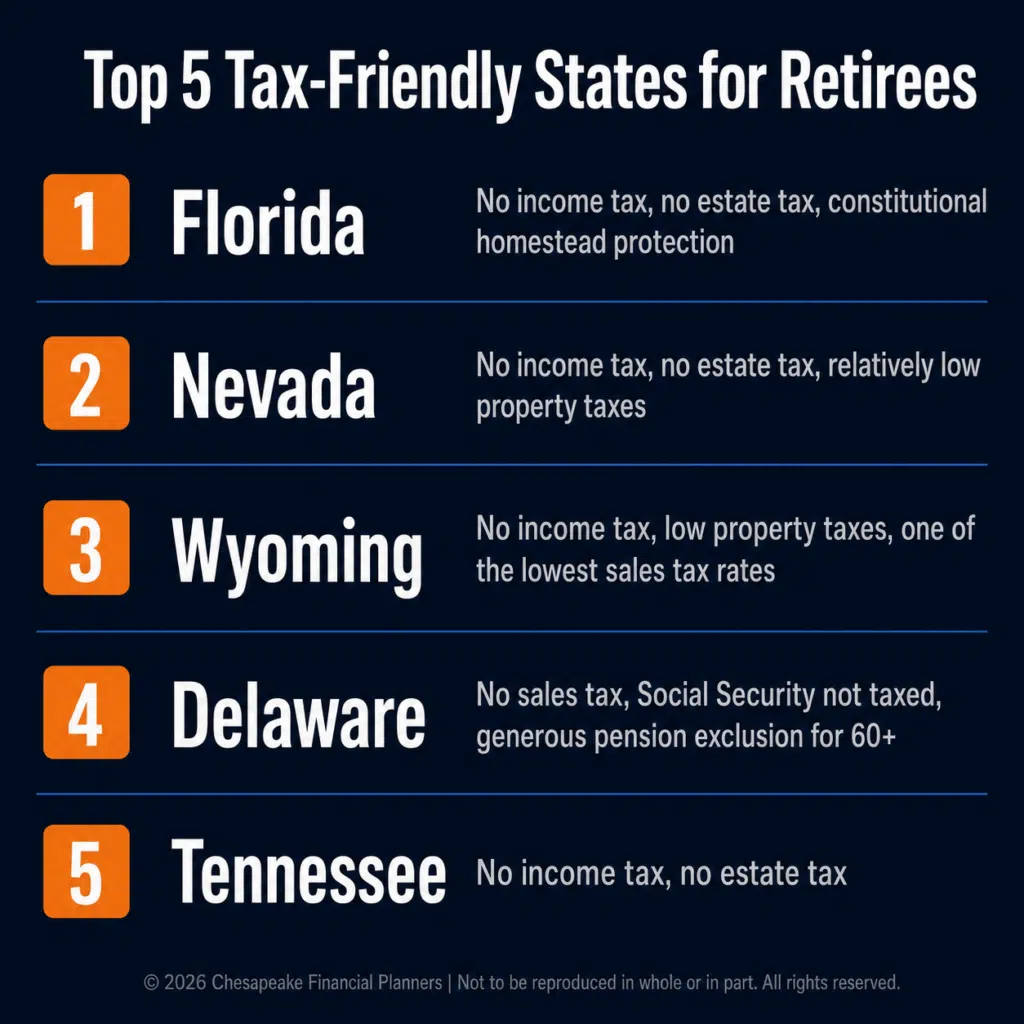
Nine states impose no state income tax on retirees as of 2026: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. New Hampshire historically taxed interest and dividend income, though that levy has been phasing out, so confirm the current rule before counting on it.
In these states, your Social Security benefits, pension income, IRA and 401(k) withdrawals, and investment income all avoid state income tax. For a retiree pulling six figures from taxable retirement accounts, the savings versus a high-tax state can run well into five figures every year.
The trade-off is real. These states raise revenue somewhere. According to the Tax Foundation, Texas carries some of the highest effective property tax rates in the country, and Washington leans on a high combined state-and-local sales tax. The retiree who benefits most owns a modest, paid-off home and draws substantial taxable income. The retiree who benefits least owns a high-value home and lives frugally on Social Security.
| State | Income Tax | Property Tax (relative) | Sales Tax |
|---|---|---|---|
| Florida | None | Moderate | 6% state |
| Nevada | None | Low-to-moderate | 6.85% state |
| Wyoming | None | Low | 4% state |
| Texas | None | High | 6.25% state |
| Washington | None | Moderate | 6.5% state |
This is also where the R.U.D.D.E.R. Method™ — Chesapeake Financial Planners' six-step planning process of Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine — earns its keep. The "Uncover and Understand" step is where a relocation decision lives or dies, because it forces the full tax picture into view before anyone signs a lease.
How Does Maryland Treat Retirement Income Compared to Other States?
Maryland is not the tax nightmare many retirees assume. The state fully exempts Social Security benefits from state income tax, and it offers a pension exclusion for eligible retirees who meet the age and income requirements set by the Comptroller of Maryland. That pension exclusion can shield a meaningful portion of qualifying pension and certain retirement-plan income from state tax.
Maryland does tax IRA and 401(k) withdrawals as ordinary income, and the state has both an estate tax and an inheritance tax, which is unusual. For a retiree with a large IRA balance and a sizable estate, those features can tip the math toward relocating. For a retiree living mostly on Social Security and a modest pension, Maryland often looks more competitive than the reputation suggests.
Before treating "leave Maryland" as the default answer, run the actual numbers against your specific income mix. How Can Maryland Retirees Reduce Their State Tax Burden? walks through the state's rules in detail.
Does Moving Change How My Social Security Is Taxed?
No — moving changes only your state tax treatment, not your federal tax treatment of Social Security. Federal taxation of Social Security benefits follows the same provisional-income rules no matter which state you live in. According to the Social Security Administration, up to 85% of your benefits can be subject to federal income tax depending on your combined income.
What moving can change is the state-level tax on those benefits. Most states, including Maryland, do not tax Social Security at the state level, so the relocation upside on Social Security specifically is often smaller than retirees expect. The bigger state-tax swing usually comes from IRA withdrawals, pensions, and investment income — not Social Security. Your claiming strategy still matters here; see Should I Take Social Security at 62 or Wait Until 70? for how timing interacts with your overall tax picture.
Frequently Asked Questions
How much can I actually save by relocating for retirement taxes?
Savings depend entirely on your income mix and home value. A high-income retiree drawing six figures from IRAs and pensions can save five figures annually by moving from a high-tax state to a no-income-tax state. A retiree living mostly on Social Security may save little, because most states already exempt Social Security from state income tax.
Are no-income-tax states always cheaper for retirees?
No. No-income-tax states often recover revenue through higher property taxes, sales taxes, or fees. According to the Tax Foundation, Texas carries some of the highest effective property tax rates in the country. A retiree with a high-value home in a no-income-tax state can pay more overall than in a moderate-income-tax state with low property taxes.
Does Maryland tax Social Security benefits for retirees?
No, Maryland fully exempts Social Security benefits from state income tax as of 2026. The state also offers a pension exclusion for eligible retirees who meet age and income requirements set by the Comptroller of Maryland. Maryland does tax IRA and 401(k) withdrawals as ordinary income, so your total picture still depends on your retirement account mix.
Which taxes matter most when comparing states for retirement?
For most retirees, property tax and income tax matter most, because property tax is often the largest annual tax expense once a mortgage is paid off. Sales tax affects daily spending, while estate and inheritance taxes matter for legacy planning. Compare all four categories together rather than focusing only on income tax.
Should I establish residency in a new state before I retire?
Establishing residency before drawing large retirement distributions can matter, because the state where you reside when you take income generally taxes that income. Confirm the specific residency rules and domicile requirements with the destination state, and document the move carefully. Rushing residency without understanding the rules can trigger audits or dual-state tax claims.
Do I need to factor in estate and inheritance taxes when relocating?
Yes, if you have a sizable estate. Maryland imposes both an estate tax and an inheritance tax, which is unusual among states. Several popular retirement destinations, including Florida, impose neither. For retirees focused on leaving a legacy, eliminating state-level estate and inheritance exposure can be a meaningful part of the relocation case.
Is Relocating Worth It for Your Situation?
Run the full tax picture before you run a moving truck. The income tax headline is only one of four taxes that matter, and for many retirees the property tax line undoes the income tax savings entirely. If you found this helpful, our retirement tax planning guide breaks down how income sources, residency timing, and estate exposure fit together — download it at chesapeakefp.com to see how a relocation decision would play out for your specific numbers.
Want to go deeper? Our Tax Strategy Readiness Quiz walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


