
Last reviewed: September 2026
Joint titling after a windfall is one of the few money decisions that is hard, and sometimes impossible, to reverse. Adding an adult child or sibling to an inherited or newly funded account usually gives that person present-day ownership, which can create a gift, expose the money to their creditors or divorce, and override your estate plan. A financial power of attorney and a transfer-on-death designation get you the help and the inheritance goal without giving up ownership.
Key Takeaways
- In most cases, adding a joint owner creates real, present ownership, not just emergency access to the account.
- Adding a non-spouse can count as a gift; the 2026 federal annual gift tax exclusion is $19,000 per recipient.
- Maryland's 10% inheritance tax applies to jointly held accounts passing to non-exempt joint owners such as nieces, nephews, and friends.
- A financial power of attorney and a transfer-on-death designation solve the access and inheritance goals without shared ownership.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate sudden wealth and estate planning decisions since earning his CFP® certification in 2013, by using Chesapeake's signature process, the R.U.D.D.E.R. Method™. "The question I ask first is simple," Jeff says. "Does this person need access to the account, or ownership of it? Almost everyone means access."
Why Does Adding a Name to an Account Feel So Small?
A widow inherited her husband's brokerage account and, a few months later, added her adult son as a joint owner. She wanted him able to help if she ever couldn't manage things, and it felt like a small, practical step. It wasn't. The account was no longer entirely hers. Her son's creditors could reach it. A divorce he didn't see coming put half of it on the table in settlement talks. And when she updated her estate plan a year later, the account didn't pass the way she intended, because it wasn't fully hers to leave.
Most decisions after a wealth event can be corrected, even the uncomfortable ones. A poorly timed investment can be adjusted, and some gifts can be offset later. Adding someone's name to an account is different, and it's one of the moves I see most often in the first year after an inheritance, a settlement, or a business sale.
The instinct behind it is a good one. You want a spouse, child, or sibling able to step in if something happens to you. The bank form makes it look like a formality, and nobody at the branch frames it as a transfer of ownership. But in most states, adding a joint owner creates immediate, real, and often equal legal ownership. That person gains a present interest in the account, with the rights and exposure that come with it.
What Can Go Wrong With Joint Titling After a Windfall?
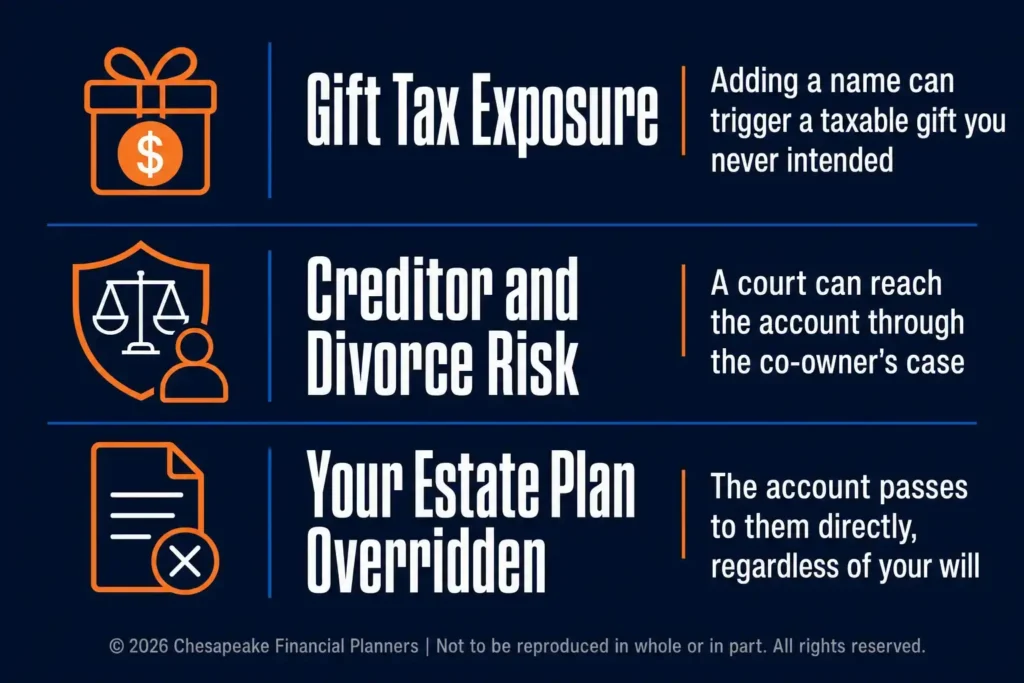
Three things go wrong, and they compound:
- Gift tax exposure. Adding a non-spouse can be treated as a completed gift, depending on the account type and how it's titled. A gift above the annual exclusion requires a gift tax return even if no tax is owed, because it draws down the $15 million lifetime exemption for 2026.
- Creditor and divorce exposure. Once another name is on the title, the account can become reachable in that person's bankruptcy, lawsuit, or divorce, regardless of whose money funded it.
- Your estate plan gets overridden. A joint account with survivorship usually passes straight to the surviving owner, no matter what your will or trust says.
"Jeff Judge has described this as one of the only mistakes in wealth event planning that can't be talked back once it's made, because a court doesn't care that the money was your inheritance."
The gift timing trips people up. The IRS instructions for Form 709 explain that with a joint bank account you can take back without the other owner's consent, "you have made a gift to the donee when the donee draws on the account for the donee's own benefit." Property bought with your money and titled as joint tenants with right of survivorship is different: the gift is "half the value of the property" when the title is created. Most people learn they created a filing obligation when their CPA asks about it the following spring.
The estate plan override causes the quietest damage. If your plan divides assets evenly among children or funds a trust, one account you forgot was jointly titled can route around it entirely. I've seen this create real inequities between siblings, not because anyone intended unfairness, but because a convenience decision made years earlier overrode a careful plan.
Is Adding a Spouse Different From Adding a Child?
Yes. Adding a spouse to an account you inherited or received in a settlement is a different conversation from adding an adult child or sibling. Spousal ownership raises its own questions, especially how inherited or separate property is treated in a divorce, and those deserve a talk with an attorney who knows your state's rules. The creditor, estate-override, and gift issues above catch people off guard most often when the added person is a child, sibling, parent, or friend.
Do the rules change by state? Meaningfully. Joint tenancy with right of survivorship, tenancy in common, and community property rules treat ownership, creditor access, and what happens at death differently. That's why a short call with your estate attorney is worth far more than copying what worked for a friend in another state.
A client of ours added his daughter's name to a taxable account shortly after selling his business, purely as a convenience. Four years later she went through a difficult divorce, and her spouse's attorney counted half the account in the marital estate, even though every dollar came from the business sale. He spent months and a meaningful legal bill establishing the money was his. He got most of it resolved in his favor, but the outcome was far from certain and depended heavily on the facts. A different setup from the start would have avoided the whole year.
How Does Maryland Tax Jointly Titled Accounts?
Maryland adds a layer national articles skip. According to the Maryland Register of Wills, inheritance tax applies to "any interest as a joint owner in any real or personal property, including credit union, bank, or other financial institution accounts." Spouses, children, grandchildren, stepchildren, parents, grandparents, siblings, and a child's spouse are exempt. A niece, nephew, friend, or unregistered partner named as joint owner can owe the 10% tax on their share when you die, even though the account didn't pass through your will.
Maryland also has its own estate tax, with a $5 million exemption that sits far below the federal level. Your share of jointly titled accounts still counts toward that total, so moving an account outside the will doesn't take it outside the tax math. Our guide to Maryland inheritance tax for non-lineal heirs walks through who pays and how families plan for it.
For families in Forest Hill, Bel Air, Jarrettsville, and across Harford County and the Baltimore metro, we review titling alongside beneficiary forms and the estate plan in one sitting. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Titling gets caught in Review and Recognize, before a form is signed rather than after a court gets involved.

What Should You Use Instead of Joint Ownership?
The goal behind joint titling, having someone able to help and making sure the right person inherits, is achievable without the ownership problem.
| Goal | Better tool | Changes ownership? | Exposes account to their creditors? |
|---|---|---|---|
| Someone can manage accounts if you can't | Financial power of attorney | No | No |
| Account passes to a named person at death | Transfer-on-death or payable-on-death designation | No | No |
| Precise control over how and when assets pass | Revocable trust | No, you keep control while living | No |
| Convenience today (the default reflex) | Adding a joint owner | Yes | Often yes |
A power of attorney and a beneficiary designation solve different problems, and most people need both. The power of attorney covers what happens if you're alive but unable to manage your affairs. The beneficiary designation covers what happens after you die. Joint ownership tries to solve both with one tool, which is why it creates so much overlap and exposure. Where a family business, real property, or a blended family is involved, a revocable trust often does the job more precisely.
Should you revisit accounts that are already jointly titled? Yes. If a family member's name went on an account years ago, check whether it still reflects what you want, especially if your estate plan, family, or that person's circumstances have changed. A review every few years, or after a major life event, catches these before a divorce, lawsuit, or death does. Before any form, ask one question: does this person need access, or ownership? For the broader sequence of first-year decisions, our sudden wealth checklist is a good next read.
Frequently Asked Questions
Is adding my child to my bank account a good idea after an inheritance?
Usually not, if the goal is help or inheritance. Adding a child typically gives them present ownership, which can expose the account to their creditors or divorce and override your estate plan. A financial power of attorney handles access while you're alive, and a transfer-on-death designation handles inheritance without shared ownership.
Does adding someone to my account trigger gift tax?
It can. For a joint bank account you can withdraw from without the other owner's consent, the IRS treats the gift as made when the other owner withdraws funds for their own benefit. For securities or property titled jointly with survivorship, a gift of half the value can occur when the title is created.
Can a joint account owner's creditors take my money?
They may be able to. Once another person is a joint owner, the account can become reachable in that person's bankruptcy, lawsuit, or divorce, regardless of who funded it. Proving the money was yours can take time and legal fees, and the result depends on your state's law and the specific facts.
Does Maryland inheritance tax apply to joint accounts?
Yes. Maryland's inheritance tax applies to a decedent's interest in jointly held accounts and property. Spouses, children, grandchildren, parents, siblings, and other lineal relatives are exempt, but a non-exempt joint owner, such as a niece, nephew, or friend, can owe 10% on the share they receive at your death.
What is the difference between a joint owner and a POD beneficiary?
A joint owner shares ownership of the account now, with the rights and risks that come with it. A payable-on-death or transfer-on-death beneficiary has no ownership during your lifetime and receives the account only at your death, outside probate. That's why a POD designation usually does what people wanted joint titling to do.
Should You Pause Before Adding a Name?
Joint titling after a windfall is easy to do at a bank counter and hard to undo afterward, so a five-minute conversation first is worth it. Ready to put a plan around yours? Jeff Judge and the Chesapeake Financial Planners team serve families and business owners across Harford County, Forest Hill, Bel Air, and the Baltimore metro area. Schedule a free fit call at chesapeakefp.com before you sign the form.
A version of this article was originally published on Chesapeake Financial Planners' LinkedIn.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


