Last reviewed: October 2026
Handling family asking for money after an inheritance comes down to two separate timelines: one for what you tell family, and a slower one for what you decide. Tell people early that a plan is being built, give them a rough checkpoint, and let one person field the questions. That keeps the pause deliberate instead of open-ended, and it keeps big gifts, loans, and purchases from being decided at a dinner table.
Key Takeaways
- Family opinions usually arrive before the plan does, and the person who inherited is often the most cautious voice in the room.
- In Maryland, collateral heirs such as nieces and nephews owe a 10% inheritance tax, one reason the tax picture deserves time.
- Gifts above the 2026 annual exclusion of $19,000 per recipient require a gift tax return, so generosity belongs inside the plan.
- Writing down the reasoning behind each money decision prevents the "was it a loan or a gift" arguments that surface years later.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate inheritances and other wealth events since earning his CFP® certification in 2013, by using Chesapeake's signature process, the R.U.D.D.E.R. Method™. "The first decision after an inheritance isn't about the money," Jeff says. "It's deciding who gets to set the pace, and the answer should be you."
Why Does Family Pressure After an Inheritance Start Before You Have a Plan?
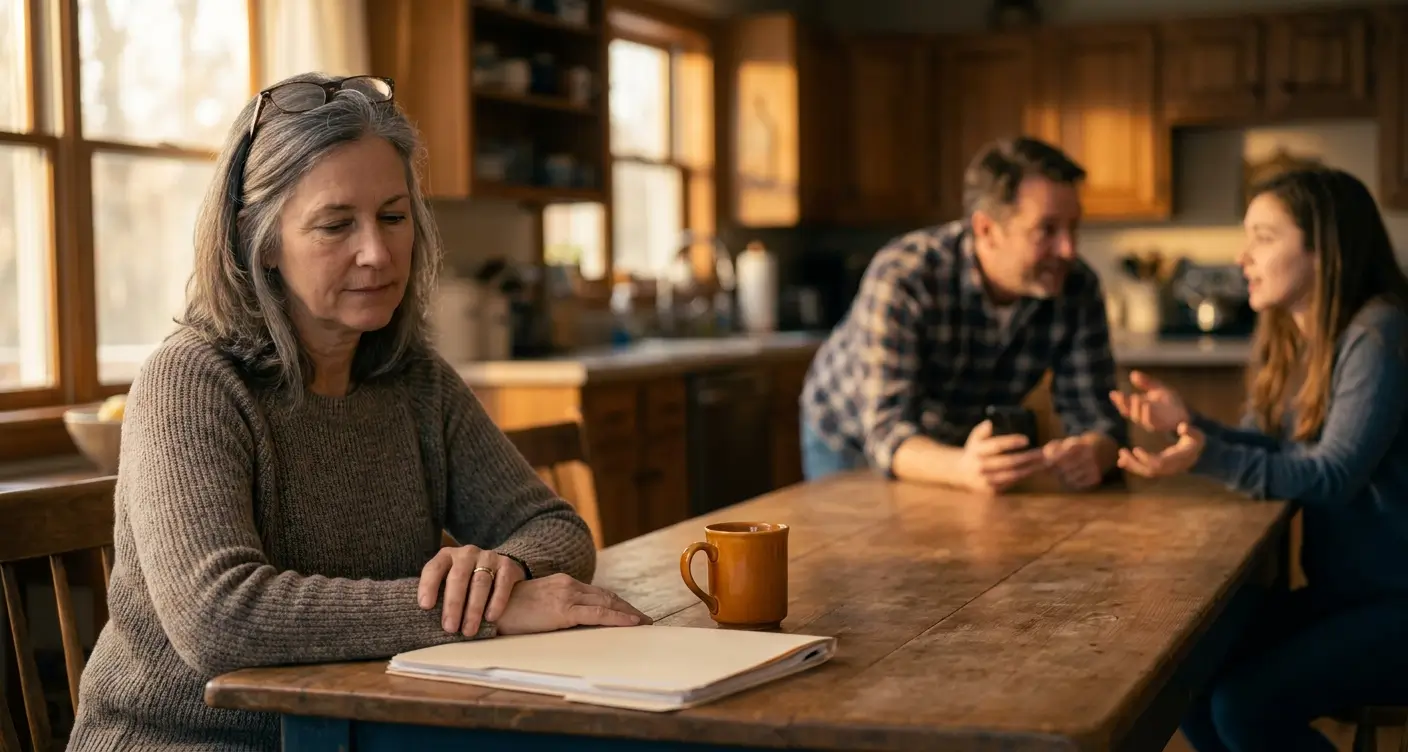
Because news of a wealth event travels faster than anyone can think. Three weeks after her father's estate settled, one of our clients called us. She hadn't touched the money. What she wanted to talk about was her brother, who had already texted twice asking when she planned to "do something" with her share, and her mother, who brought up a nephew's tuition at every family dinner. She hadn't made a single financial decision, yet she was already managing everyone's opinion about the decisions she hadn't made.
That pattern repeats whether the money comes from an inheritance, a business sale, or a legal settlement. A sibling hears the amount before the recipient meets an advisor, or a spouse starts mentally pricing a renovation. Most of it comes from affection or worry, not selfishness.
The effect is the same either way. Opinions show up on a schedule set by other people's expectations, not by the recipient's readiness. And the person who received the money is often the most careful voice in the conversation while carrying the most pressure to look decisive. The tax questions have answers. The family dynamics don't come with a worksheet.
Why Does Taking Time Look Like Indecision to Family?
Silence gets read as avoidance. A reasonable "let me sit with this for a few months" gets translated into "she doesn't know what she's doing" or "he's being strange about the money." Yet taking time is usually the right instinct after a large change in circumstances.
A client we worked with after a business sale put it well. The deal wasn't the hard part. The hard part was watching his adult kids treat a normal pause as a red flag, asking whether he was okay and whether something was wrong. Nothing was wrong. He was doing exactly what a thoughtful person should do after a seven-figure change: nothing, on purpose, for a while.
"Jeff Judge has pointed out that the recipients who make the worst decisions in the first year after a windfall are almost never the ones who waited."
They're the ones who felt cornered into acting fast because waiting felt socially expensive. In the first months after a wealth event, the financially sound move and the socially comfortable move often point in opposite directions, and family pressure pushes toward comfort.
That doesn't mean waiting forever. Our guide to what "I'll wait until I'm ready" actually costs explains why an open-ended pause has its own price. The goal is a bounded pause with the money parked somewhere deliberate, not paralysis.
What Does Giving In to Family Pressure Actually Cost?
The bigger cost is decisions made to relieve pressure rather than serve your goals. Those tend to be the ones people regret:
- A quick loan to a sibling made to avoid an awkward conversation, with no paperwork and no repayment plan.
- A large gift decided over one dinner instead of as part of a broader plan, sometimes above the annual exclusion and without anyone filing the return it requires.
- A renovation greenlit because a spouse had already spent the money in their head before anyone ran the numbers on taxes or timing.
- An inherited IRA withdrawn too fast, even though most non-spouse beneficiaries have a 10-year window to spread the taxable income.
None of these choices is automatically wrong. Helping family, giving generously, and upgrading a home can all belong in a plan. The problem is sequence: a decision made under social pressure before you understand your own tax situation, your long-term needs, and what you actually want, as opposed to what feels easiest to say yes to.
Is it selfish to make family wait? No. A gift or loan made after the plan exists is usually larger, cleaner, and better documented than one made in month one. Waiting serves the relationship as much as the money.
How Do You Handle Family Asking for Money Without Damaging Relationships?
Separate the timeline for family communication from the timeline for financial decisions. They don't have to move at the same speed, and treating them separately takes a surprising amount of pressure off.
- Tell family early that a plan is being built. Say that specific decisions will come once it's in place, without promising a date.
- Give them a reason that isn't defensive. "We're working through the tax picture before deciding anything" reframes the wait from evasive to responsible.
- Set a loose checkpoint. "We expect a clearer picture by the end of summer" replaces an open-ended wait, which invites speculation, with a bounded one, which mostly doesn't.
- Pick one person to field questions. A spouse or your advisor can handle the "so what are you going to do" texts so you aren't relitigating at every gathering.
- Write down the reasoning, not just the decision. Jeff Judge emphasizes this with families: a short note on why you gave, lent, or held cash prevents a drifted memory years later, when one sibling remembers a loan and another remembers a gift.
What if the pressure comes from your spouse? A spouse belongs in the planning process, especially when the money will shape your shared life. The line is between a spouse being part of the process and a spouse's preferences short-circuiting it. One couple we worked with after a settlement spent their first two meetings just agreeing on what "taking our time" meant: four to six months, which decisions could wait, and which couldn't. That early conversation prevented more friction than any investment choice did.
Not every question is pressure for its own sake, either. A sibling asking about the family cabin has a real stake and deserves an answer about that property, even in month one. A sibling asking when a cash gift is coming can be told, honestly, that gifting decisions come after the plan. Separating "what are you worried about" from "what have you decided" lets a family address the first without forcing the second.
Why Does the Maryland Tax Picture Justify a Pause?
Maryland is one of the few states with both an estate tax and an inheritance tax, so "we're working through the tax picture" is often literally true. According to the Register of Wills, "For decedents dying on or after July 1, 2000, direct or lineal heirs are exempt from inheritance tax." Collateral heirs, such as nieces, nephews, cousins, and friends, generally pay 10%. Maryland's estate tax has a $5 million exemption, far below the federal level, and settling an estate can take months.
That means the amount you'll actually have, and when, may not be clear in the first weeks. Committing money before the estate closes is how people promise family money that later turns out to be smaller.
For families in Forest Hill, Bel Air, Jarrettsville, and across Harford County and the Baltimore metro, we build that pause into a plan rather than leaving it to willpower. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. The first two steps happen before any money moves, which gives you a credible answer when family asks what's next. Our sudden wealth checklist lays out the first 90 days, and our guide to handling family expectations after a windfall covers setting boundaries once decisions are made.
Frequently Asked Questions
How long should you wait before making decisions after an inheritance?
Many families benefit from a deliberate pause of three to six months before major decisions, with the money parked somewhere accessible and low-volatility while the estate settles and the tax picture comes into focus. The key is a bounded pause with a checkpoint, not an open-ended wait that turns into avoidance.
How do you tell family you need time after an inheritance?
Tell family early and plainly that a plan is being built and that specific decisions, including any gifts, will come after it's in place. Offer a reason, such as working through the tax picture, and a rough checkpoint like the end of the season, so the pause reads as responsible rather than evasive.
How do you stop family members from asking for money after an inheritance?
You usually can't stop family members from asking for money, but you can slow the requests by telling relatives early that a plan is being built and that gifts and loans come after it. Relatives asking for money after an inheritance usually act out of affection or worry, so one consistent answer works better than case-by-case decisions.
Do I owe Maryland inheritance tax on money I inherit?
It depends on your relationship to the person who died. Maryland exempts lineal heirs, such as children, grandchildren, and parents, along with siblings and spouses. Collateral heirs, including nieces, nephews, cousins, and friends, generally pay a 10% inheritance tax on what they receive, separate from Maryland's estate tax.
Should I lend money to a family member right after inheriting?
Usually not in the first months. A loan made quickly to avoid an awkward conversation is often undocumented, and the IRS can treat an informal, interest-free family loan as a gift. Build the plan first, then decide whether a loan or a gift fits, and put either one in writing.
What should I write down when I make a family money decision?
Write the date, the amount, whether it's a gift or a loan, any repayment terms, and a sentence or two on why you made the choice. Jeff Judge recommends keeping that note with your estate documents, because disputes years later are rarely about the decision and usually about a memory that drifted.
Ready to Build a Plan Before the Pressure Builds?
Family asking for money after an inheritance is easier to handle when you can point to a real plan with a real timeline. Ready to put a plan around yours? Jeff Judge and the Chesapeake Financial Planners team serve families and business owners across Harford County and the Baltimore metro. Schedule a free fit call.
A version of this article was originally published on Chesapeake Financial Planners' LinkedIn.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 ½ may result in a 10% IRS penalty tax in addition to current income tax.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


