

What's the Best Way to Handle Debt Coming Into a Marriage?
Last reviewed: July 2026
The best way to handle debt before marriage is to disclose everything fully, decide together whether you'll pay it down jointly or keep it separate, and protect the debt-free partner's credit through clear legal and account boundaries. Pre-marriage debt almost always stays with the person who incurred it, but the choices you make now shape your financial life as a couple for years. Talk about it before you set a wedding date, not after.
Key Takeaways
- Debt you bring into a marriage stays legally yours in most states; your spouse is not automatically responsible for it.
- Full disclosure of every loan, balance, and interest rate is the foundation of any joint plan.
- The average graduate carries $38,375 in federal student loan debt as of 2026, per the Education Data Initiative.
- A prenuptial agreement can lock pre-marriage debt to the original borrower when balances are large.
- Decide deliberately whether to attack debt together or separately; default drift causes resentment.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate major financial transitions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched more marriages strained by a hidden $15,000 credit card balance than by the balance itself; the secret does the damage, not the number.
How Should Couples Disclose Debt Before Marriage?
Want to go deeper? Our Marriage & Money walks through this step by step.
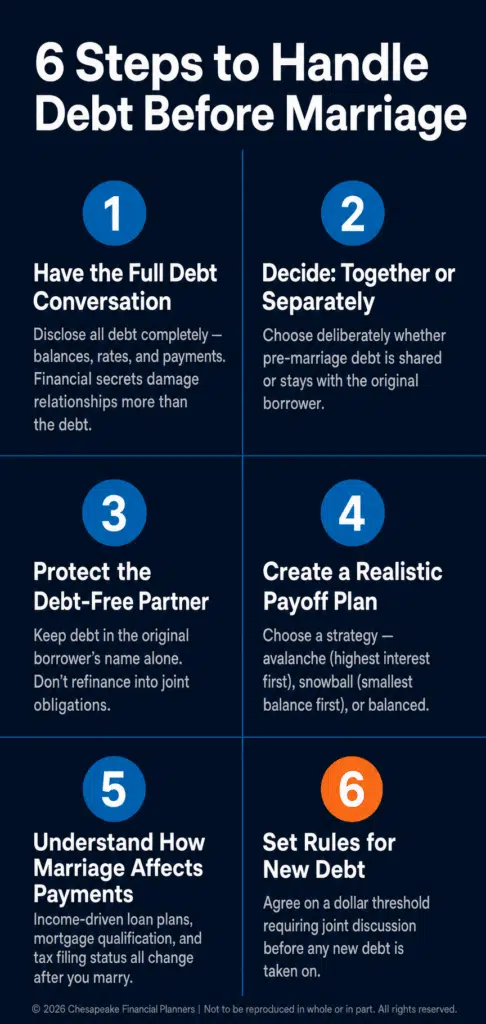
Before you book a venue, sit down together and put every obligation on the table. Full disclosure means no minimizing, no hiding, no sugar-coating. The financial secret almost always corrodes trust faster than the debt does.
Share everything in writing:
- Student loans, with current balances, interest rates, monthly payments, and payoff timelines
- Credit card debt, including balances, rates, and minimum payments
- Car loans with remaining balances
- Personal loans from banks, family, or other sources
- Medical debt from past health expenses
- Tax debt owed to federal or state authorities
- Other obligations like child support, alimony, or legal judgments
This matters more than couples expect. The Federal Reserve reports total U.S. household debt reached $18.2 trillion in 2025, so odds are good at least one partner carries something. Don't shame each other for past decisions. The point is building a shared future, not relitigating the past. Jeff Judge tells engaged couples to treat this conversation the way they'd treat a medical history with a new doctor: complete honesty now prevents a much worse surprise later.
Should You Pay Off Debt Before Marriage Together or Separately?
You have two real paths, and you should choose one on purpose rather than letting it happen by accident.
Keeping debt separate means each partner stays responsible for their own pre-marriage balances, paying from individual income or accounts. This works when debt amounts are badly imbalanced, when one partner feels strongly about not owning debt they didn't create, or when you want clean boundaries between pre-marriage and marital obligations.
Tackling debt together means treating every balance as "ours" and combining resources to pay it off faster. This works when balances are similar or manageable, when combined income creates real acceleration power, and when you want to kill "yours versus mine" thinking early.
Neither approach is right or wrong. It depends on the numbers, your values, and how you operate as a couple. The mistake is drifting into one without ever discussing it. This is also where Chesapeake Financial Planners' R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. The "Discuss and Decide" step is exactly where this choice belongs. For more on merging accounts, see How Should We Combine Our Finances After Getting Married?.
How Do You Protect the Debt-Free Partner?
If one of you is debt-free and the other brings substantial balances, take deliberate steps to keep the clean partner clean.
Keep the debt in the original borrower's name alone. Don't refinance student loans, car loans, or credit cards into joint obligations. Once debt becomes joint, both credit scores and both partners' security are on the hook.
Understand how new debt works after the wedding. Debt incurred during marriage for marital purposes typically becomes joint regardless of whose name is on it, but pre-marriage debt usually stays with the original borrower in most states. Maryland is an equitable-distribution state, which generally keeps pre-marriage debt separate, though the details get fact-specific.
Consider a prenuptial agreement when the balance is large or you want absolute clarity. A prenup can specify that pre-marriage debt remains the sole obligation of the person who incurred it. The Consumer Financial Protection Bureau notes that marriage itself doesn't merge your credit files, but joint accounts will link your financial fates quickly.
Hold off on joint credit applications until pre-marriage debt is substantially paid down. The indebted partner's lower score or high debt-to-income ratio will drag down what you can qualify for on a mortgage. Maintain separate credit cards at first to shield the debt-free partner's score. To go deeper, read How Does Marriage Affect Your Credit Score and Financial Health?. Jeff Judge notes: "I tell couples to hold off on any joint credit application until the indebted partner's balances are substantially down, because dragging a high debt-to-income ratio into a mortgage application can cost you far more in rate than you might expect."
What's the Smartest Debt Payoff Strategy for Newlyweds?
Wishful thinking doesn't erase a balance. You need a concrete plan built on real numbers.
Start by calculating exactly how much you owe, to whom, at what rate, and with what minimum payment. Then pick a method:
| Method | How It Works | Best For |
|---|---|---|
| Avalanche | Pay minimums, then attack the highest interest rate first | Minimizing total interest paid |
| Snowball | Pay minimums, then attack the smallest balance first | Building momentum with quick wins |
| Balanced | Target high-interest debt while clearing one stressful balance early | Couples who need both math and motivation |
The avalanche method saves the most money. The snowball method keeps couples motivated through visible progress. Be honest about timelines. With the average graduate carrying $38,375 in student loans per the Education Data Initiative, a minimum-payment plan can stretch past two decades unless you accelerate. Name that reality in your plan instead of pretending it disappears quickly.
Marriage can also reshape your payments. Income-driven student loan repayment plans may shift if you file taxes jointly, and the U.S. Department of Education confirms that joint filing can raise your calculated payment. Your combined debt-to-income ratio also affects mortgage qualification, so understand the math before you shop for a home. For the bigger picture, see How do we align our financial goals as a newly married couple?.
Frequently Asked Questions
Am I responsible for my spouse's debt before marriage?
No, in most states you are not legally responsible for debt your spouse incurred before the wedding. Pre-marriage debt stays with the original borrower unless you actively make it joint by co-signing or refinancing into both names. Community property states have narrower exceptions, so check your state's rules.
Does marriage combine your debt automatically?
Marriage does not automatically combine your existing debt. Each partner keeps the balances they brought in, and your credit files stay separate until you open joint accounts. Debt taken on during the marriage for shared purposes is generally where joint responsibility begins, not the loans you walked in with.
Should we get a prenup if one partner has a lot of debt?
A prenuptial agreement makes sense when one partner brings substantial debt and you want absolute legal clarity. A prenup can state that pre-marriage debt remains the sole obligation of the borrower, protecting the debt-free spouse if the marriage ends. For modest, manageable balances, a prenup is often unnecessary, but it removes ambiguity for large amounts.
Will my spouse's debt hurt my credit score?
Your spouse's pre-marriage debt does not directly hurt your credit score, because credit files remain individual after marriage. The risk appears when you open joint accounts, co-sign loans, or add your spouse as an authorized user. Keep accounts separate early to protect a strong score while paying down the other partner's balances.
How do we decide whether to pay off debt together or separately?
Decide based on the size imbalance, your shared values, and how you operate as a couple. Pay together when balances are similar and combined income speeds payoff; keep debt separate when amounts are badly mismatched or one partner wants clear boundaries. The key is choosing deliberately rather than drifting into a default arrangement.
If you're heading into marriage with debt on one or both sides, the conversation is worth having now while you have options. Our free guide to merging your financial lives walks couples through disclosure, account structure, and a payoff plan step by step. Download it at chesapeakefp.com.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
CFP Board owns the marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the U.S.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization’s initial and ongoing certification requirements to use the certification marks.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


