
How Does Marriage Affect Your Credit Score and Financial Health?
Last reviewed: July 2026
Marriage does not merge your credit scores or change your credit number on its own. Your credit report stays tied to your Social Security number, not your marital status, so a 780 score and a 620 score never average into a 700. What actually moves the needle is the financial behavior that follows the wedding: joint accounts you open together, authorized user arrangements, and loans you apply for as a couple. Understanding how marriage can affect your credit score helps you protect both partners before a missed payment or maxed-out card does damage neither of you saw coming.
Key Takeaways
- Marriage itself never merges credit scores; your report stays tied to your Social Security number, not your marital status.
- Joint credit accounts report to both spouses, so one person's late payment can drop both scores.
- As of 2026, FICO scores still range from 300 to 850 and are calculated per individual.
- Adding a spouse as an authorized user can build their credit using your account history.
- Lenders typically qualify joint applicants on the lower of the two credit scores.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate major financial transitions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched newly married couples make one expensive assumption over and over: that "we're married now" means their finances automatically protect each other. The opposite is often true until you set up the right accounts.
Do Credit Scores Merge When You Get Married?
No. There is no such thing as a joint credit score, and marriage does not blend your credit history with your spouse's. The three major bureaus, Equifax, Experian, and TransUnion, track each person's credit separately using their Social Security number. Getting married changes your relationship status, not your credit identity.
That separation cuts both ways. You do not inherit your spouse's late payments or collections, but you also do not get a boost from their flawless history just by signing a marriage certificate. According to FICO, scores still range from 300 to 850 in 2026, and each one belongs to a single individual.
Here is the common scenario. You walk into the marriage with a 780 score, no debt, and a spotless payment record. Your spouse has a 620 score and $30,000 in credit card debt. The day after the wedding, your score is still 780 and theirs is still 620. Nothing automatically combined. Jeff Judge tells clients this is the single most misunderstood part of marriage and money, and clearing it up early prevents a lot of needless worry.
How Can Marriage Affect Your Credit Score Through Joint Accounts?
Joint accounts are where marriage actually touches your credit. When you open a joint credit card, auto loan, or mortgage, both spouses are equally responsible for the debt, and the account appears on both credit reports. Every payment, balance, and mistake is shared.
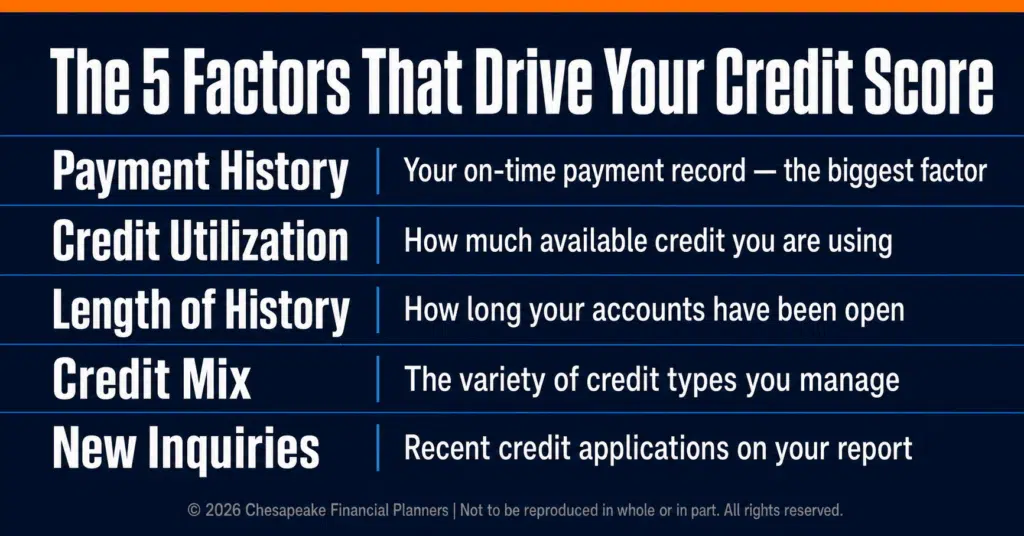
When the account is managed well, both scores benefit. On-time payments build positive history for each of you, and a higher combined credit limit (when you keep balances low) improves your credit utilization ratio, which Experian reports accounts for roughly 30% of your FICO score. Shared discipline strengthens both profiles at once.
When it goes the other way, it hurts both of you. A late payment, a maxed-out balance, or a default lands on each spouse's report. The painful version looks like this: you open a joint card with a $10,000 limit, your spouse maxes it out and misses two payments, and both scores drop even though you never swiped the card. That is the risk of combining finances after marriage without a clear plan for who pays what and when.
What's the best way to handle debt coming into a marriage?
How Does Authorized User Status Affect a Spouse's Credit Score?
Adding your spouse as an authorized user on your credit card can build their credit without making them legally responsible for the debt. The primary cardholder still owes the balance, but the account's history often appears on the authorized user's credit report.
This is one of the most effective tools for a spouse with thin or damaged credit. If you add a partner to a well-managed card you have held for years, that account's age, payment history, and low utilization can flow onto their report and lift their score over time. For a spouse with no credit history at all, authorized user status can jumpstart the file.
A few cautions matter. Not every card issuer reports authorized user activity to the bureaus, so confirm yours does before counting on it. If the primary cardholder runs up a balance or misses payments, that damage can flow to the authorized user too. The good news is that an authorized user can be removed at any time, which detaches the account from their report without hurting the primary cardholder. Used carefully, authorized user credit is one of the cleanest ways to lift a struggling spouse's score. Jeff Judge notes: "Before you count on an authorized user account to move the needle on your spouse's score, call the card issuer and confirm they actually report that status to all three bureaus, because not all of them do."
What Happens to Your Credit When You Apply for Loans Together?
When you apply for a mortgage, auto loan, or joint credit card, lenders pull both credit reports and weigh both scores. For qualification, most lenders use the lower of the two scores, not the average and not the higher one. That single rule shapes how much house or car a married couple can afford.
Picture a mortgage application where you have a 780 score and your spouse has a 620. The lender will often price the loan off the 620, which can mean a higher interest rate or a tougher approval, even though your credit is excellent. According to the Consumer Financial Protection Bureau, even a modest rate difference compounds into tens of thousands of dollars over a 30-year mortgage.
Lenders also consider both incomes for your debt-to-income ratio and review both credit histories for risk. So a spouse with strong income but weak credit helps on affordability while hurting on rate. Jeff Judge often runs the numbers both ways with couples before they apply, because sometimes one spouse applying alone gets a better rate than both applying together. This is exactly the kind of fork the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process of Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, is built to work through before you sign anything.
How Should We Combine Our Finances After Getting Married?
How do we align our financial goals as a newly married couple?
Frequently Asked Questions
Does getting married hurt your credit score?
Getting married does not hurt your credit score by itself, because your credit report stays tied to your Social Security number, not your marital status. Your score only changes if you take on joint debt, become an authorized user, or co-apply for a loan that one spouse manages poorly.
Do married couples have a combined credit score?
No, married couples do not have a combined or joint credit score. Each spouse keeps a separate credit report and score with Equifax, Experian, and TransUnion. Lenders may look at both scores when you apply for joint credit, but the two numbers never merge into one shared score after marriage.
Can my spouse's bad credit affect mine?
Your spouse's bad credit does not affect your individual score unless you share an account. If you open a joint credit card or loan, their late payments and high balances appear on your report too. Keeping accounts in one name limits how much a spouse's poor credit can reach your own profile.
How can I build my spouse's credit after marriage?
You can build your spouse's credit by adding them as an authorized user on a long-standing, well-managed card that reports to the bureaus. Their score can also rise through on-time payments on a joint account. Confirm your issuer reports authorized user activity before relying on this strategy to raise their score.
Should we combine finances when we get married?
Combining finances after marriage works best as a deliberate choice, not an assumption. Many couples blend everyday spending through a joint account while keeping individual credit cards open to protect each spouse's separate credit history. The right mix depends on your debts, incomes, and how you both prefer to manage money together.
Does marriage affect your financial health beyond credit?
Marriage affects financial health through shared income, combined debts, joint tax filing, and aligned goals, not just credit scores. Two incomes can accelerate saving, while mismatched spending habits can create strain. Building a shared budget and reviewing each partner's debts and credit early helps protect your long-term financial health as a couple.
Ready to Start Your Marriage on Solid Financial Ground?
The wedding is the easy part. Aligning two credit histories, two sets of debts, and two money personalities is where real planning pays off. If you found this helpful, our guide on combining finances after marriage covers joint accounts, budgeting, and protecting both credit profiles in depth. Download it at chesapeakefp.com and start your marriage knowing exactly how marriage can affect your credit score and your shared financial health.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


