
Published: | Last reviewed: November 2026 by Jeff Judge, CFP®
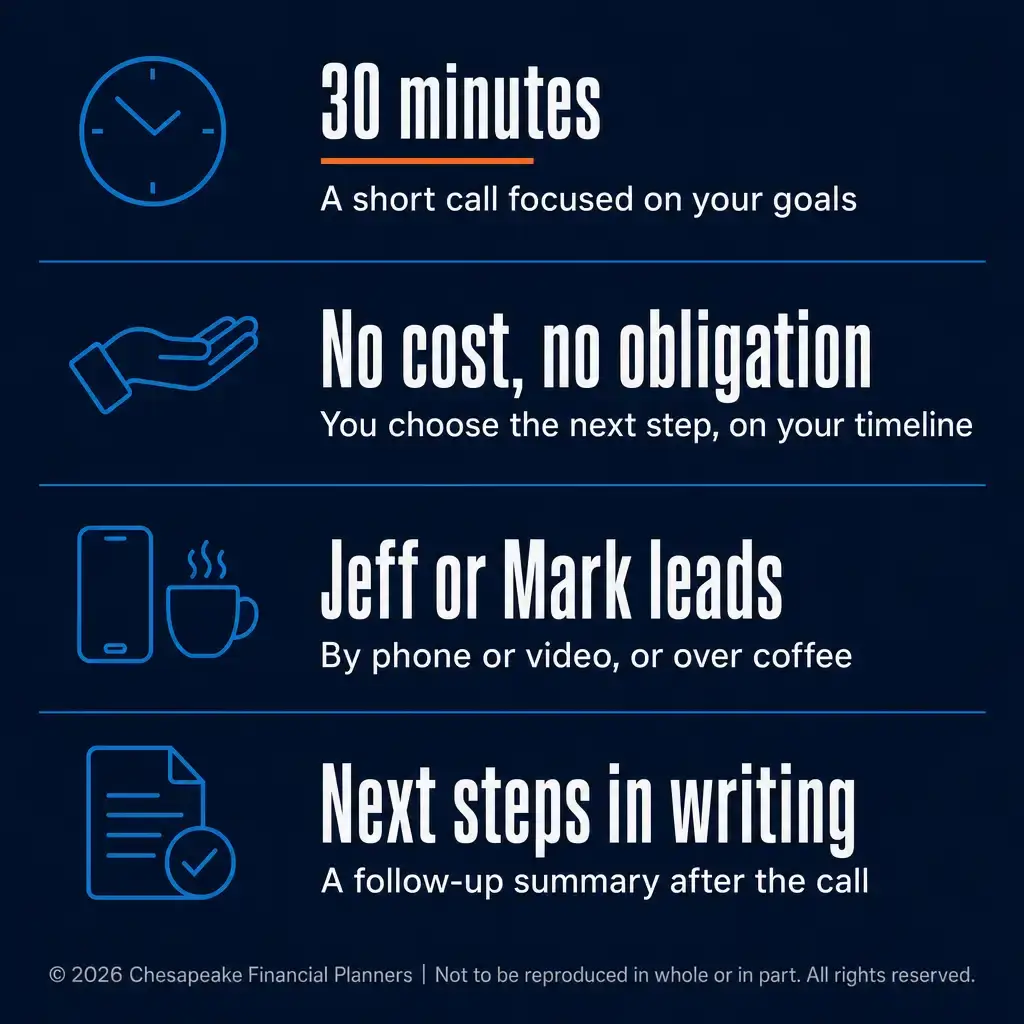
Your first meeting with Chesapeake Financial Planners is a 30-minute fit call. It costs nothing and carries no obligation. Jeff Judge or Mark Rossbach leads it, you do most of the talking about your goals, and the purpose is simple: find out whether we are a good mutual fit. This guide walks through the call itself, what happens next, what to gather, how we are paid, and what the first 90 days look like if we decide to work together.
On This Page
- What happens in the first meeting with Chesapeake Financial Planners?
- What happens after the fit call?
- What should I gather before we meet again?
- How does Chesapeake Financial Planners charge, and where can I verify it?
- What do the first 90 days look like after the first meeting?
- How do I know whether Chesapeake is the right fit for me?
- Ready to book your first meeting?
- Frequently Asked Questions
Key Takeaways
- The first meeting is a 30-minute fit call with no cost and no obligation, built to learn whether working together makes sense for both sides.
- If we both want to proceed, we email the list of documents and data we need so meeting time goes to decisions, not number gathering.
- Paycheck and benefits details help us compare your 401(k) deferrals with the IRS 2026 employee limit of $24,500.
- The IRS generally says to keep tax records for 3 years, so your last two returns should be within reach.
- Chesapeake lists planning fees of $3,000 to $10,000 per year; investment management starts near 1.30% of assets and falls to 0.35%.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate first conversations with an advisor since earning his CFP® certification in 2013, by using Chesapeake's signature process, the R.U.D.D.E.R. Method™. “A first meeting should leave you knowing what working together would look like, whether or not you ever become a client.”
What happens in the first meeting with Chesapeake Financial Planners?
The first meeting with Chesapeake Financial Planners is a 30-minute fit call, and it is mostly listening. We ask about your goals and what a good outcome would look like for you and your family. You are welcome to ask questions about how we work, but we pride ourselves on transparency so our website has a lot of answers already. The call is built around hearing you out, finding out what is important to you, and how we can help.
The purpose is to decide, together, whether we are a good mutual fit. That cuts both ways. If your situation calls for something we do not do well, or the chemistry is off, a 30-minute call is a cheap way to learn that on both sides. Many people expect a financial advisor consultation to feel like an audition for a sales pitch. This one is built to feel like the opposite.
Does the fit call cost anything or lock me into working together?
No. The fit call costs nothing and carries no obligation. You can end the conversation with a clearer picture of your own goals and decide on your own timeline whether to take a next step.
Jeff Judge describes what he wants people to take from it this way: “I would rather you leave the call knowing exactly what working with us involves than leave it feeling sold.” That is a general observation about how the firm approaches the conversation, and it sets the tone for everything that follows.
| Fit call detail | What to expect |
|---|---|
| Length | 30 minutes |
| Cost | None |
| Obligation | None |
| Format | Phone or video conference from home, coffee or breakfast, or in person at your home if you are local to our Forest Hill area |
| Led by | Jeff Judge or Mark Rossbach |
| Main activity | Listening to your goals |
| Afterward | A follow-up summary and next steps |
Who leads the call, and where does it happen?
Jeff or Mark leads the fit call. Both are partners in the firm, so the person you talk to first is not a gatekeeper handing you off to someone else. The call is virtual, by phone or video conference, and you can take it from your kitchen table or home office without driving anywhere or rearranging your workday. If you would rather meet over coffee or breakfast, that works too, and if you are local to our Forest Hill area, we can meet in person at your home. Choose the format that lets you talk openly about money, because a good financial advisor meeting depends far more on candor than on the setting.
Do I need to prepare anything for the fit call?
No. Preparation is optional before the first meeting. It does make this meeting as well as later meetings more productive, and the sections below explain exactly what helps. For the fit call itself, bring your goals and your questions. After the call, we send a follow-up summary and next steps, so you are not left trying to remember everything you discussed.
What happens after the fit call?
After the fit call, the two of us decide what the relationship would look like, whether to start, and when. Scope matters here. Some people want a full planning relationship with ongoing investment management. Others want help with one specific decision. We sort that out before anyone commits to anything.
If we decide together to work together, we send a follow-up email listing the documents we need and the data we need to collect. The goal is straightforward: spend meeting time on the important issues, on clarifying the data, and on your questions, instead of copying numbers that already sit on your statements.
Jeff Judge puts the logic plainly: “Instead of asking questions about this data, we can review it beforehand and come in to the meeting with questions and have a better handle on their situation.”
That is why the meeting after the fit call tends to be more useful than the first one. We have already read what you sent, so the conversation starts from your actual situation, not from a blank page. It also means you can spend your own energy on the part only you can supply: what matters to you, what worries you, and what you want your money to do.
What should I gather before we meet again?
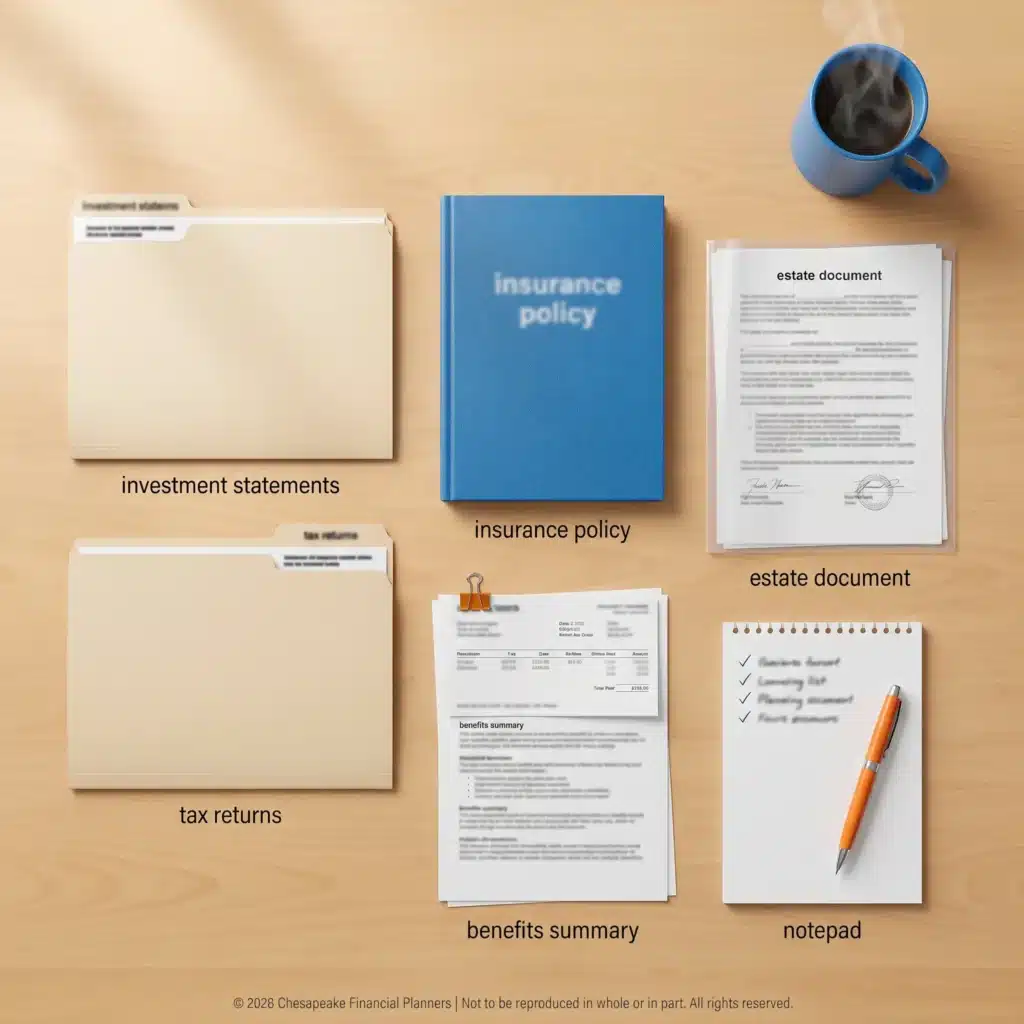
Gather your recent investment and retirement statements, your last two years of tax returns, your insurance policies and estate documents, your paycheck and benefits information, and a list of your own questions. Nothing here is required before the first meeting, but every item shortens the path from conversation to plan. Treat it as a financial advisor meeting checklist you can finish in an evening. Our post on what to bring to your first financial planning meeting goes through it item by item.
| What to gather | Why it helps |
|---|---|
| Recent investment and retirement statements | Shows what you own, where, and what it costs |
| Last two years of tax returns | Shows your income, deductions, and tax picture |
| Insurance policies and estate documents | Confirms coverage, beneficiaries, and who is named to act for you |
| Paycheck and benefits information | Shows savings rates, employer match, and benefit choices |
| Your own list of questions | Keeps the meeting pointed at what worries you |
A few details are worth knowing. The IRS generally advises keeping tax records for 3 years, so two years of returns should be easy to find. Your paystub shows how much you defer into your workplace plan, and the IRS lists a 2026 elective deferral limit of $24,500, so it is a fast way to see how your savings compare.
Our preferred route is simple. When you register for a meeting, we send a questionnaire, and you upload your statements through our secure upload portal. The link sits in the website header. If uploading feels like a hurdle, tell us and we will work out another way to receive them.
Do not let a missing document stop you from booking. A statement you cannot find yet is a question for us to help answer, not a reason to wait, and the follow-up email after the fit call spells out what we need.
How does Chesapeake Financial Planners charge, and where can I verify it?
Chesapeake is paid in four ways, and we explain which ones apply to you before you commit. They are an asset-based fee on managed assets, a flat or annual planning fee, a one-time planning project fee, and commissions on some insurance or brokerage products offered through LPL.
For the published ranges, the site is the source of record. Planning and personal oversight runs $3,000 to $10,000 per year, depending on the complexity of your situation. Investment management starts around 1.30% for smaller portfolios and decreases to as low as 0.35% as assets grow. A one-time planning project is a fee of $5,000 to $15,000 that covers one year of follow-ups and meetings and does not renew automatically.
| How you may pay | How it works | Published range |
|---|---|---|
| Asset-based fee | A percentage of the assets we manage | About 1.30% for smaller portfolios, down to 0.35% as assets grow |
| Annual planning fee | A flat annual fee for planning and oversight | $3,000 to $10,000 per year |
| One-time planning project | A fee for a defined planning project, with one year of follow-ups | $5,000 to $15,000, no automatic renewal |
| Commissions | Paid on some insurance or brokerage products through LPL | Disclosed with the recommendation |
How can I check what any advisor charges?
Ask for the firm's Form ADV and read the fees section. According to Investor.gov, Part 2A of Form ADV contains 18 separate items, and advisers must describe how they are compensated. That is why we point people to the document instead of asking you to take our word. Fees are always disclosed upfront, before any commitment, and they are outlined in the client agreement. Compare the numbers in any advisor's Form ADV against what the advisor tells you in person, and ask about every line you do not understand. For the full breakdown of how we charge, see our post on how Chesapeake charges for financial planning.
What do the first 90 days look like after the first meeting?
If we decide to work together, the first 90 days follow three steps. First comes data gathering, using the questionnaire and secure portal, followed by a discovery meeting. Second is a plan presentation meeting. Third is account opening and transfers. Those three steps sit inside the R.U.D.D.E.R. Method™. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. If you want the full tour, our guide to the R.U.D.D.E.R. Method™ covers all six steps, and our look at how a financial plan actually gets built goes deep on the design stage.
How often will we meet once the plan is in place?
We meet with planning clients two to four times a year, depending on your preference and situation, and you can ask to meet whenever life changes. Jeff Judge notes that the plan is not the finish line: “The presentation meeting is where the real work starts, because a plan only matters if it keeps getting updated as your life moves.”
How do I know whether Chesapeake is the right fit for me?
You know by testing us against the same questions you would put to any advisor, and our post on what it means for a financial advisor to be a fiduciary covers the biggest one. Ask how the advisor is paid, who you will work with, what meetings look like, and what standard of conduct applies to the advice you receive. The CFP Board's Code of Ethics states the standard for CFP® professionals directly: “At all times when providing Financial Advice to a Client, a CFP® professional must act as a fiduciary, and therefore, act in the best interests of the Client.”
On the question of who we serve best, which our post on who Chesapeake works with best covers in more detail, our strongest fits are tech professionals, pre-retirees and retirees, business owners, federal employees and military families, and widows, divorced women, and families after a wealth event. If you fit one of those groups, the planning questions we handle often will sound familiar to you. If you do not, the fit call is still the right place to find out.
One more point matters for people who are unsure about commitment. Chesapeake offers one-time plans as an on-ramp to ongoing planning, so you can start with a defined project and decide later whether a continuing relationship makes sense. Our post on choosing ongoing financial planning or a one-time plan compares the two.
Related Topics Worth Reading
These posts cover the decisions people usually weigh around a first meeting.
- Get ready with What Should I Bring to My First Financial Planning Meeting? for the item-by-item checklist.
- See the numbers in How Does Chesapeake Financial Planners Charge for Financial Planning? for fee types, published ranges, and how to check any advisor's Form ADV.
- Understand the standard in What Does It Mean for a Financial Advisor to Be a Fiduciary? for the duties of care and loyalty and five questions to ask.
- Check your fit with Who Does Chesapeake Financial Planners Work with Best? for the five groups we serve most often.
- Decide how to start with Should I Choose Ongoing Financial Planning or a One-Time Plan? for the on-ramp from a project to ongoing planning.
Articles in this topic
Frequently Asked Questions
Is the first meeting with Chesapeake Financial Planners really no cost?
Yes. The first meeting is a 30-minute fit call that costs nothing and carries no obligation. Its purpose is to see whether we are a good mutual fit, so you can ask questions, describe your goals, and decide afterward whether to take any next step.
How long does the first meeting last?
The first meeting is a 30-minute fit call. Most of that time is spent listening to your goals, with room for your questions about how we work. Afterward we send a follow-up summary and next steps so you have the conversation in writing.
Do I need to bring documents to the fit call?
No. Documents are optional before the first meeting. Recent statements, your last two years of tax returns, insurance and estate documents, and paycheck and benefits information make later meetings more productive, but the fit call itself only needs your goals and questions.
Can I meet from home, or do I have to visit an office?
You can meet from home. The fit call is virtual by phone or video conference, so you can take it from your kitchen table or home office without any travel. If you prefer a more personal setting, coffee or breakfast works too, and if you are local to our Forest Hill area, we can meet in person at your home.
Who will I meet with on the first call?
Jeff Judge or Mark Rossbach leads the fit call. Either one will spend the time listening to your goals and answering your questions, and afterward we send a follow-up summary and next steps so you know exactly where things stand.
What happens if we decide to work together?
If we decide together to work together, we send a follow-up email listing the documents and data we need. The first 90 days then follow three steps: data gathering and a discovery meeting, a plan presentation meeting, and account opening and transfers.
How often will we meet after the plan is in place?
We meet with planning clients two to four times a year, depending on your preference and your situation. You can also ask to meet any time life changes, such as a new job, a move, a health event, or a change in your family.
Ready to book your first meeting?
Ready to put a plan around your goals? Jeff Judge and the Chesapeake team serve families and business owners across Harford County and the Baltimore metro area. Book your no-cost 30-minute fit call and start your first meeting with Chesapeake Financial Planners on your terms.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
CFP Board owns the marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the U.S.
The ChFC® is the property of The American College of Financial Services, which reserves sole rights to its use, and is used by permission.
The CLU® is the property of The American College of Financial Services, which reserves sole rights to its use, and is used by permission.
This material is for educational purposes only. Insurance products contain exclusions, limitations, and terms for keeping them in force. Please contact a qualified insurance professional for costs and complete details.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


