

How Do I Choose a Fee-Based Fiduciary Financial Advisor in Harford County?
Last reviewed: July 2026
To choose a fee-based fiduciary financial advisor in Harford County, confirm the advisor is held to a fiduciary standard in writing, ask exactly how they get paid, and check their credentials and disciplinary record before you sign anything. A financial advisor in Harford County who acts as a fiduciary is legally required to put your interests ahead of their own. Start with their Form ADV, their CFP® status, and a clear, plain-English answer about fees.
Choosing a financial advisor is one of those decisions people put off because it feels complicated. It isn't. The hard part is knowing which questions actually matter. Below is the framework I use with clients who are evaluating advisors here in Harford County, including how to tell a true fiduciary from a salesperson with a nice title.
On This Page
- Key Takeaways
- What Is a Fiduciary Financial Advisor in Harford County?
- Fee-Based vs. Fee-Only: What's the Difference?
- How Do I Verify a Financial Advisor's Credentials and Record?
- How Does a Fee-Based Fiduciary in Maryland Build Your Plan?
- Why Work With a Local Financial Advisor Near Bel Air and Forest Hill?
- Frequently Asked Questions
- Disclosures
Key Takeaways
- A fiduciary financial advisor in Harford County is legally obligated to put your interests first, every recommendation, every time.
- Verify any advisor's record free at BrokerCheck and IAPD before your first meeting.
- The 2026 CFP® certification requires passing a board exam and meeting ongoing ethics standards through the CFP Board.
- Fee-based and fee-only are different; ask the advisor to explain their structure in writing before you hire.
- As of 2026, the median financial advisor earns about $102,140 per year, per the Bureau of Labor Statistics.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate advisor selection and financial planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often tells people that the single most useful question they can ask an advisor is the one most people skip: "How exactly do you get paid, and who else pays you?"
What Is a Fiduciary Financial Advisor in Harford County?
A fiduciary financial advisor in Harford County is an advisor legally bound to act in your best interest, not their own and not their firm's. That sounds obvious. It isn't the standard everyone in this industry is held to.
Many people who call themselves "advisors" operate under a lower bar called the suitability or best-interest standard, which lets them recommend products that are merely acceptable for you, even when something better and cheaper exists. A fiduciary cannot do that. Investment adviser representatives registered through the SEC or state regulators owe a fiduciary duty that covers both their advice and their conflicts of interest.
Here in Harford County, that distinction matters because the local market includes everyone from large brokerage branches to independent planners. Jeff Judge has watched clients arrive with portfolios stuffed full of high-commission products sold by someone who was technically allowed to do it. The fix usually costs them years of unnecessary fees they never knew they were paying. Ask any prospective advisor to confirm their fiduciary duty in writing. A real fiduciary will hand you that confirmation without flinching.
Fee-Based vs. Fee-Only: What's the Difference?
Fee-based and fee-only sound identical and mean different things. A fee-only advisor is paid only by you, through a flat fee, hourly rate, or percentage of assets. A fee-based advisor is paid by you and can also earn commissions on certain products, such as insurance.
Neither structure is automatically better. What matters is transparency. A fee-based fiduciary can still serve your interests well, provided they disclose every way they earn money and explain when a commission applies. The problem is never the structure itself; it's a structure the advisor won't explain plainly.
| Question | Fee-Only | Fee-Based |
|---|---|---|
| Who pays the advisor? | Only the client | Client plus possible product commissions |
| Can they earn commissions? | No | Yes, on certain products |
| Fiduciary duty possible? | Yes | Yes, when registered as an adviser |
| Key thing to verify | Total fee, in writing | Every income source, in writing |
Chesapeake Financial Planners is a fee-based financial planning firm in Forest Hill, Maryland that helps business owners, pre-retirees, and people navigating major financial transitions make data-driven decisions. When you ask how an advisor near Bel Air or Forest Hill gets paid, you should get a straight answer in two sentences, not a five-minute speech that leaves you more confused than when you started.
How Do I Verify a Financial Advisor's Credentials and Record?
You verify a financial advisor's credentials and disciplinary record using two free public tools before you ever sit down with them. Check brokers through FINRA BrokerCheck and investment advisers through the SEC's IAPD database. Both show registration status, employment history, and any complaints or disclosures.
Credentials matter too. The CFP® designation, awarded by the CFP Board, requires coursework, a rigorous board exam, thousands of hours of experience, and ongoing adherence to a fiduciary code of ethics. Other letters worth recognizing include AEP®, ChFC®, and CLU®, each tied to specialized planning knowledge. According to the Bureau of Labor Statistics, employment of personal financial advisors is projected to grow faster than the average occupation through the coming decade, which means more new advisors entering the field and more reason to verify experience before you commit.
A clean record and good credentials don't guarantee a good fit. But a checkered record is a clear stop sign, and it takes about ten minutes to find one.
How Does a Fee-Based Fiduciary in Maryland Build Your Plan?
A fee-based fiduciary financial advisor in Maryland should build your plan through a structured process, not a product pitch dressed up as advice. At Chesapeake Financial Planners, we use the R.U.D.D.E.R. Method™, which is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. The point of a defined process is simple. It keeps the focus on your goals instead of whatever product happens to pay the advisor most this quarter.
Here's what a real planning process looks like in practice. It starts with understanding what you actually own and owe, then moves to what you want your money to do over the next five, ten, and thirty years. Only after that does the conversation turn to specific recommendations. If an advisor near Bel Air or Forest Hill leads with a product before they understand your situation, that's backwards, and it tells you what they're really selling.
Jeff Judge often reminds clients that the best plans get revisited. Tax law changes. Markets move. Your life shifts. A good Harford County advisor reviews your plan on a regular schedule and adjusts it, rather than setting it once and disappearing. Ask any prospective advisor how often they meet with clients and what a typical review covers. The answer reveals whether you're hiring a planner or a salesperson.
Why Work With a Local Financial Advisor Near Bel Air and Forest Hill?
Working with a local financial advisor near Bel Air and Forest Hill means you get someone who understands the financial picture of Harford County families, not a faceless call center three time zones away. Chesapeake Financial Planners sits at 2402 Scotlon Ct in Forest Hill, a short drive from Bel Air, and our clients are the business owners, teachers, retirees, and families who live and work across the county.
A local advisor knows the Maryland tax landscape, the local employers and their retirement plans, and the rhythms of the community. We serve families across Harford County and the broader Baltimore metro area, and many of our relationships span decades. When you can drive ten minutes for a face-to-face conversation about your retirement, that proximity matters more than people expect, especially during the moments that count: a job change, a sale, an inheritance, or a market scare.
What does a fiduciary financial advisor in Harford County do that a broker doesn't?
How do I find a CFP near Forest Hill, MD?
How much does a CFP cost in Maryland?
What should I look for in a financial advisor in Maryland?
Who Is a Virtual Financial Advisor in Maryland Actually Right For?
Frequently Asked Questions
What questions should I ask a financial advisor in Harford County before hiring them?
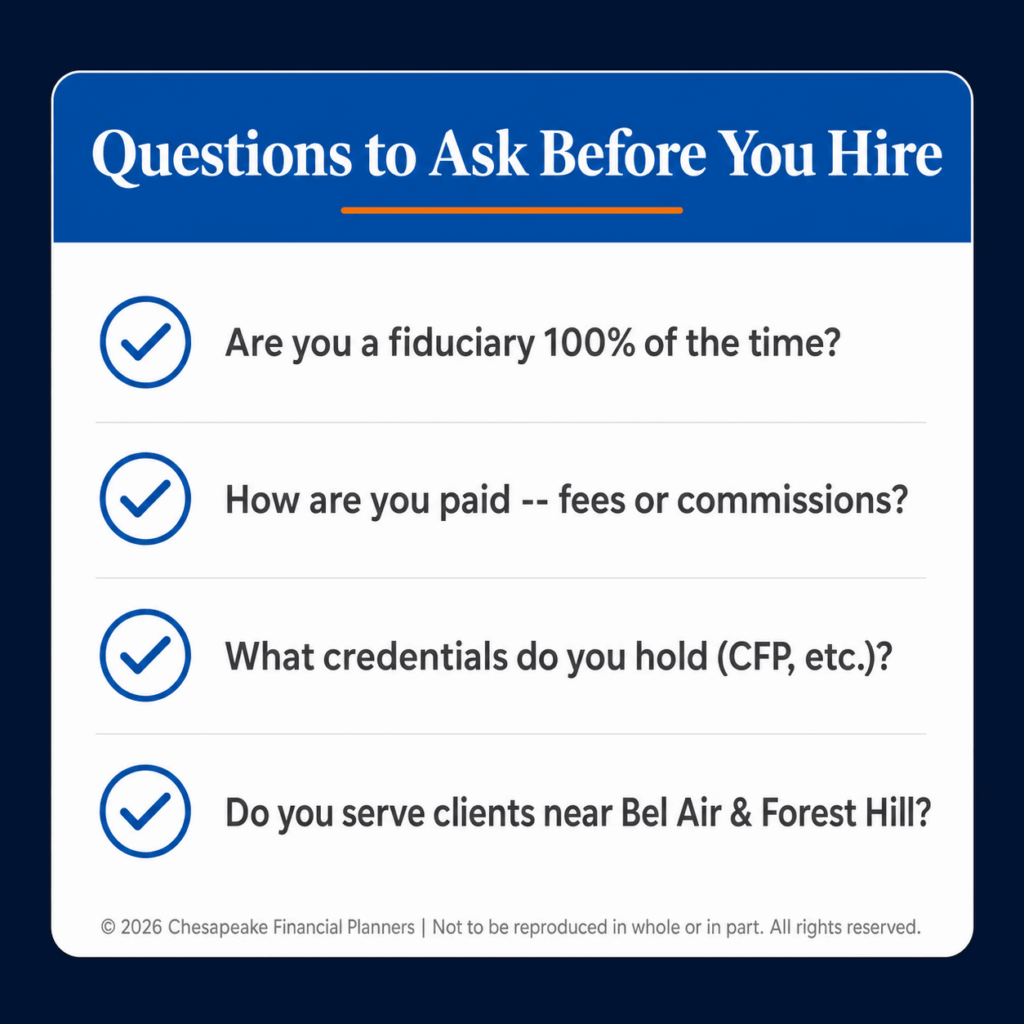
Ask whether they are a fiduciary in writing, exactly how they are paid, what credentials they hold, and how often they review your plan. A trustworthy advisor near Bel Air or Forest Hill answers all four directly and without hesitation. Vague or defensive answers are your signal to keep looking elsewhere.
Is a fee-based advisor the same as a fiduciary in Maryland?
No, fee-based describes how an advisor is paid, while fiduciary describes the legal standard of care they owe you. An advisor can be one without the other. The best choice in Maryland is an advisor who is both a fiduciary and fully transparent about every way they earn money, confirmed in writing.
How do I verify if a financial advisor in Harford County is legitimate?
Verify any Harford County financial advisor for free using FINRA BrokerCheck for brokers and the SEC's IAPD database for investment advisers. Both tools show registration status, work history, and any complaints or disciplinary actions. Confirm credentials like CFP® directly through the CFP Board website as well.
How much does a financial advisor cost in Maryland?
Costs vary by structure. Many Maryland advisors charge a percentage of assets managed, a flat planning fee, or an hourly rate. The most important step is getting the full fee in writing before you hire anyone, so you can compare advisors near Bel Air and Forest Hill on equal terms. Never accept a fee answer you can't repeat back clearly.
Should I choose a local advisor or a national firm near Forest Hill?
A local advisor near Forest Hill offers face-to-face access, knowledge of Maryland tax rules, and an understanding of Harford County's local economy that a national call center cannot match. For most families, that proximity and accountability matter more than a recognizable national brand name, especially during major life transitions when timely, personal advice is worth the most.
Choosing the right advisor comes down to three things you can verify before you ever commit: fiduciary duty, fee transparency, and a real planning process. Jeff Judge and the Chesapeake team serve families and business owners across Harford County and the Baltimore metro from our Forest Hill office near Bel Air. Schedule a free, no-obligation fit call at chesapeakefp.com and bring your questions.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


