
How Do I Know If I'm Saving Enough for Retirement?
Last reviewed: July 2026
You're saving enough for retirement when your projected savings, Social Security, and other income sources will cover your expected retirement expenses for as long as you live. The fastest gut-check: most people on track are saving 15% of gross income (including any employer match) starting in their 20s or 30s, and have roughly 1x their salary saved by 30 and 3x by 40. But the honest answer depends on your goals, not a generic benchmark. Here's how to tell where you actually stand.
Key Takeaways
- Saving enough means your income sources will cover your retirement expenses for life, not hitting a generic number.
- In 2026 you can contribute up to $24,500 to a 401(k), per the IRS.
- A savings rate below 10% of gross income usually signals undersaving unless you started very early.
- Workers ages 60 to 63 get a higher catch-up contribution in 2026, a real chance to close a gap.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. Jeff's take: most people sweat their investment returns and ignore the savings rate, which is the one lever almost entirely in their control. He has been helping families and business owners in Harford County and the Baltimore metro area develop comprehensive retirement and income strategies since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™.
What Does "Saving Enough for Retirement" Actually Mean?
Saving enough for retirement means your combined income sources, your portfolio, Social Security, any pension or rental income, will fund your desired lifestyle from the day you stop working until the end of your life. That's the whole definition. It is not about hitting a round number someone quoted at a dinner party.
The trap is measuring yourself against an abstract figure. The right comparison is your own goal. A couple planning a quiet retirement in a paid-off home needs far less than a couple planning twenty years of travel and a second property. Jeff Judge often tells clients that the number on the brochure means nothing until you attach it to your actual spending.
Two people with identical balances can be in completely different shape. One has a pension and no mortgage. The other rents and supports an adult child. Same savings, very different answers. That's why "enough" is personal.
What Savings Rate Should I Aim For?
Most advisors target saving 15% of gross income for retirement, including any employer match, beginning in your 20s or 30s. Start later and the number climbs fast. If you didn't begin until your 40s, you may need to push toward 20% to 30% to catch up, because you've lost the years where compounding does the heavy lifting.
To find your own rate, divide everything you save in a year (401(k), IRA, taxable investments, HSA dollars earmarked for the future) by your gross income. Below 10% is a yellow flag unless you started very young or have a pension waiting.
The employer match is the cheapest progress you'll ever make. A 6% contribution with a 6% match is effectively a 12% savings rate, and half of it isn't your money. Skipping that match is the single most common mistake Jeff sees in 401(k) reviews. It's free money left on the table every payday.

How Much Should I Have Saved by My Age?
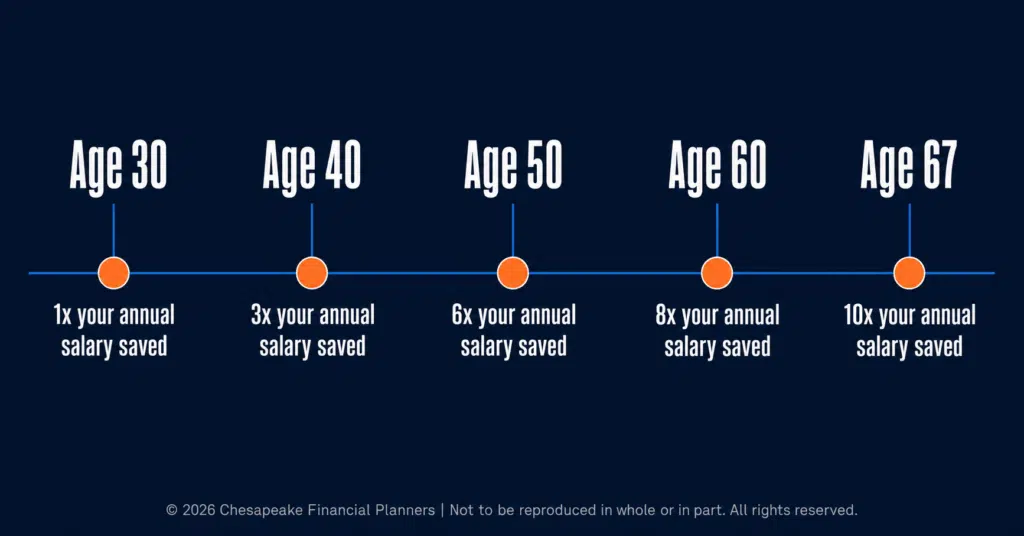
Age-based multiples give you a quick ballpark. A widely used framework suggests roughly 1x your salary saved by 30, 3x by 40, 6x by 50, 8x by 60, and 10x by your late 60s. So a 40-year-old earning $150,000 would aim for about $450,000.
These multiples assume Social Security covers part of your income and your savings replace the rest. The Social Security Administration confirmed a 2.8% cost-of-living adjustment for 2026, which lifts benefits but won't replace most of a high earner's income. The more you earn now, the smaller the share Social Security covers, and the more your own savings have to carry.
Treat the multiples as a thermometer, not a verdict. Behind the benchmark? That's useful information, not a failing grade. It tells you to run the real math.
| Age | Target multiple of salary | Example at $150,000 income |
|---|---|---|
| 30 | 1x | $150,000 |
| 40 | 3x | $450,000 |
| 50 | 6x | $900,000 |
| 60 | 8x | $1,200,000 |
| Late 60s | 10x | $1,500,000 |
How Do I Know If I'm Actually On Track?
The only reliable way to know if you're saving enough is to run a retirement projection that models your real numbers. A benchmark tells you if you're in the neighborhood; a projection tells you if you'll make the mortgage. This is exactly where a structured planning process earns its keep.
A projection pulls together four moving parts: your target retirement age and annual expenses, your estimated Social Security benefit, expected investment growth based on your asset allocation, and whether the money lasts through a long retirement. Get those right and the "am I enough" question answers itself.
At Chesapeake Financial Planners we run this through the R.U.D.D.E.R. Method™, our six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. The reassessment step matters most here, because a plan that was on track three years ago can drift after a job change, a market move, or a new goal.
If you're behind, you have more levers than you think: raise the savings rate, work a year or two longer, trim fixed expenses, or delay Social Security to grow the benefit. Jeff has watched clients close surprising gaps in the final decade simply by capturing the full match and redirecting a raise instead of spending it.
Frequently Asked Questions
What is a good savings rate for retirement?
A good retirement savings rate is 15% of gross income, including any employer match, if you start in your 20s or 30s. Starting in your 40s, you'll likely need 20% to 30% to reach the same goal, because you have fewer years for compound growth to work in your favor.
How much can I contribute to a 401(k) in 2026?
You can contribute up to $24,500 to a 401(k) in 2026, according to the IRS. Workers age 50 and older can add a catch-up contribution, and those ages 60 to 63 qualify for an even larger catch-up amount, making the late-career years a strong window to close a savings gap.
Is the age-based savings benchmark accurate for everyone?
No, age-based benchmarks like 3x salary by 40 are a starting point, not a personal answer. They assume average income replacement and standard Social Security. Your real target shifts with your retirement lifestyle, other income sources like a pension, your debt, and how long you expect to live. Always confirm with a projection.
What if I started saving for retirement late?
If you started late, focus on the levers you control: capture the full employer match, use catch-up contributions after age 50, raise your savings rate as income grows, and consider delaying retirement a year or two. Working slightly longer both shortens the retirement you fund and lets your savings keep compounding, which can meaningfully change the outcome.
How do I calculate my own retirement savings rate?
Divide everything you save in a year (401(k), IRA, HSA dollars earmarked for retirement, and taxable investments) by your gross annual income. A result below 10% usually signals undersaving unless you began very young or have a pension. Use the number as a checkpoint, then validate it against a full retirement projection.
Find Out Where You Actually Stand
If this raised more questions than it answered, that's normal, because the only honest answer comes from running your own numbers. Our free retirement planning guide walks you through estimating your target, your savings rate, and your gap, step by step. Download it at chesapeakefp.com and stop guessing whether you're saving enough for retirement.
How Do I Know If I'm On Track for Retirement?
How can I close the retirement savings gap as a woman?
Should I Take Social Security at 62 or Wait Until 70?
How Do I Create Multiple Income Streams for Retirement?
Want to go deeper? Our Retirement Income Blueprint Workbook walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


