
How Do I Create Multiple Income Streams for Retirement?
Last reviewed: July 2026
You create multiple retirement income streams by layering guaranteed sources like Social Security and pensions underneath flexible sources like portfolio withdrawals, then adding optional layers such as part-time work, rental income, or annuities. The goal is to cover your essential expenses with income you can count on, then fund everything else from sources that can flex when markets move against you.
Key Takeaways
- Layer guaranteed income (Social Security, pension) to cover essentials, then use portfolio withdrawals for discretionary spending you can flex down.
- Delaying Social Security from 62 to 70 raises your benefit roughly 8% per year, per the Social Security Administration.
- Required minimum distributions begin at age 73 under current IRS rules, so build them into your tax plan early.
- Tax diversification across taxable, tax-deferred, and Roth accounts gives you control over your annual tax bill.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement income planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often tells clients that the people who sleep well in retirement aren't the ones with the biggest portfolios; they're the ones whose essential bills are covered by income that shows up no matter what the market does.
Why Do Multiple Income Streams Matter in Retirement?
Relying on a single income source in retirement concentrates your risk in one place. If that source falters, your whole plan wobbles. A retiree who leans entirely on a stock portfolio faces sequence-of-returns risk, where a market drop early in retirement can permanently shrink the money meant to last 30 years. Someone leaning only on Social Security watches inflation chip away at purchasing power year after year. A pension-only retiree is exposed to a fixed payment that doesn't grow.
Multiple streams fix this by giving you options. When stocks are down, you pull from cash or fixed income instead of selling at a loss. When you want to manage your tax bill, you choose which account to tap. And when prices rise, inflation-adjusted sources like Social Security keep pace while fixed sources hold steady.
Jeff has watched this play out across hundreds of client retirements. The ones who panic during a downturn are almost always the ones whose monthly grocery money depends on what the market did last quarter. The ones who stay calm have their floor covered. That difference is structural, not emotional.
This is the kind of decision the R.U.D.D.E.R. Method™ is built for. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine.
Will My Money Last If the Market Crashes During Retirement?
What Are the Core Retirement Income Streams to Consider?
There are six income sources most retirees draw from, and you rarely need all of them. The right mix depends on your assets, your health, and how much certainty you want.
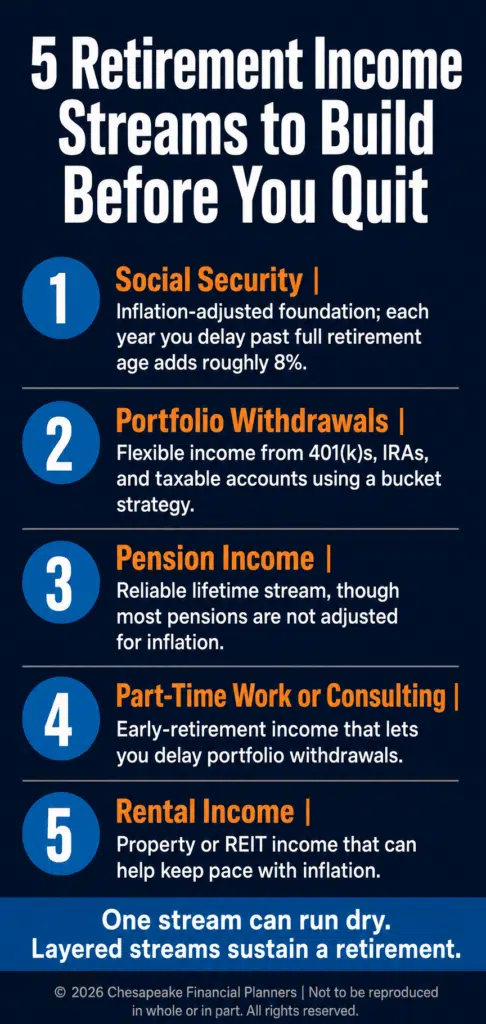
Social Security is your inflation-adjusted foundation. It's guaranteed for life, adjusts annually for inflation, and provides survivor benefits. The 2026 cost-of-living adjustment was 2.8%, according to the Social Security Administration. When you claim matters enormously: benefits can start as early as 62 or be delayed to 70, and each year you wait past full retirement age adds roughly 8% to your monthly check. Jeff Judge notes: "Most clients underestimate what that 8% per year delayed credit actually means in dollars over a 20- or 25-year retirement, and once we put the lifetime totals side by side on paper, the claiming decision looks very different than it did at the kitchen table."
Portfolio withdrawals from 401(k)s, IRAs, and taxable accounts give you the most flexibility. Many retirees use a bucket strategy, segmenting money into short-term cash for one to two years of expenses, medium-term bonds for years three through ten, and long-term stocks for growth beyond that. The structure lets you avoid selling stocks during a downturn.
Pension income is a reliable stream if you have it, though most pensions aren't inflation-adjusted. A payment that feels comfortable at 65 can feel thin at 85.
Part-time work or consulting in the first few retirement years supplements income and, more importantly, lets you delay portfolio withdrawals during the vulnerable early years when sequence risk is highest.
Rental income from physical property or REITs can keep pace with inflation, though physical real estate demands management and carries liquidity constraints.
Annuities, specifically a Single Premium Immediate Annuity or deferred income annuity, trade liquidity for guaranteed lifetime income. They work best for a portion of your assets, never all of them.
When does buying an annuity make sense for retirement income?
Should I Take Social Security at 62 or Wait Until 70?
How Do You Coordinate Income Sources for Tax Efficiency?
The order in which you tap your income sources can change your lifetime tax bill by tens of thousands of dollars. A coordinated plan covers essentials with guaranteed income first, then layers flexible sources on top in the most tax-smart sequence.
Start by covering non-discretionary expenses (housing, utilities, healthcare, food) with Social Security, any pension, and possibly a small annuity. If your guaranteed sources cover your essentials, a market downturn becomes an inconvenience instead of a crisis. Then use portfolio withdrawals for discretionary spending like travel and entertainment, which can flex down in bad years.
The withdrawal sequence usually breaks into phases. Between roughly age 65 and 72, before required minimum distributions begin, you're often in a lower tax bracket, which makes it a strong window for Roth conversions and for drawing from taxable accounts. At 73, RMDs from traditional retirement accounts become mandatory under IRS rules, whether you need the income or not. Coordinating those RMDs with Social Security keeps you from accidentally pushing yourself into a higher bracket. Throughout retirement, tax-free Roth withdrawals give you a lever to manage taxable income in high-expense years.
Keep 12 to 24 months of expenses in cash for surprises. A new roof or a health event shouldn't force you to sell investments at the worst possible time.
How do I create reliable income from my retirement savings?
Frequently Asked Questions
How many income streams do I need in retirement?
Most retirees do well with three to four coordinated income streams rather than chasing every possible source. A common structure has Social Security covering 40 to 50% of expenses, portfolio withdrawals providing 30 to 40%, and a pension or small annuity filling the remaining 10 to 20%. The right number depends on your assets and how much guaranteed income you want.
Should Social Security be my primary retirement income source?
Social Security should serve as your guaranteed foundation, but it works best paired with other sources rather than standing alone. It's the only common income stream that's guaranteed for life and adjusts for inflation every year. For most retirees, Social Security covers a meaningful share of essential expenses while portfolio withdrawals and other streams handle the rest.
When do required minimum distributions start affecting my income plan?
Required minimum distributions from traditional IRAs and 401(k)s begin at age 73 under current IRS rules. Once they start, you must withdraw a set amount each year whether you need the income or not. Building RMDs into your plan early, often through Roth conversions in your 60s, helps you avoid being forced into a higher tax bracket later.
What is the most tax-efficient order to withdraw retirement income?
A common tax-efficient sequence draws from taxable accounts first, then tax-deferred accounts like traditional IRAs, then tax-free Roth accounts last. In your 60s, before RMDs begin, you often have a lower-bracket window ideal for Roth conversions. The exact order depends on your bracket, your account balances, and your income needs in any given year.
Can I retire with only Social Security and a portfolio?
Yes, many retirees build a fully workable plan using only Social Security and a diversified investment portfolio. The key is structuring portfolio withdrawals to survive market downturns, often through a bucket strategy that keeps one to two years of cash available. Adding a third source like part-time work or a small annuity simply gives you more flexibility and resilience.
Ready to Build Your Income Plan?
Turning a pile of savings into reliable monthly income is one of the trickiest transitions in financial planning, and the order you do things in matters as much as the assets themselves. If this overview was helpful, our retirement income guide walks through the bucket strategy, withdrawal sequencing, and Social Security timing in far more depth. Download it at chesapeakefp.com to see how the pieces fit together for your situation.
Want to go deeper? Our Retirement Income Blueprint Workbook walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


