

How Much Does a CFP Cost in Maryland?
Last reviewed: July 2026
A financial planner cost in Maryland depends on one thing more than any other: how the planner gets paid. Fees range from roughly $200 to $400 an hour for project work, $2,500 to $10,000 a year for flat-fee planning, or 0.35% to 1.30% of the assets a CFP® professional manages for you. The right structure depends on the complexity of your situation and how much you have invested, not on a single sticker price.
Key Takeaways
- CFP fees in Maryland follow three models: percentage of assets managed, a flat annual planning fee, or hourly project work.
- Hourly CFP rates in Maryland typically run $200 to $400 per hour, with one-time plans often costing $2,000 to $5,000.
- Every Maryland registered investment advisor must disclose all fees and conflicts in Form ADV Part 2 before you sign.
- The 2018 tax law eliminated the individual deduction for advisory fees, so confirm treatment with your CPA.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate advisor fee decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view is blunt: most people in Maryland obsess over the percentage and ignore whether the planning behind it is actually worth paying for.
There is no uniform price for working with a CFP® professional in Maryland. Below is a plain breakdown of the three main compensation models, what they actually cost here, and how to weigh value instead of just the number.
What Are the Three Main Fee Structures for a Financial Planner in Maryland?
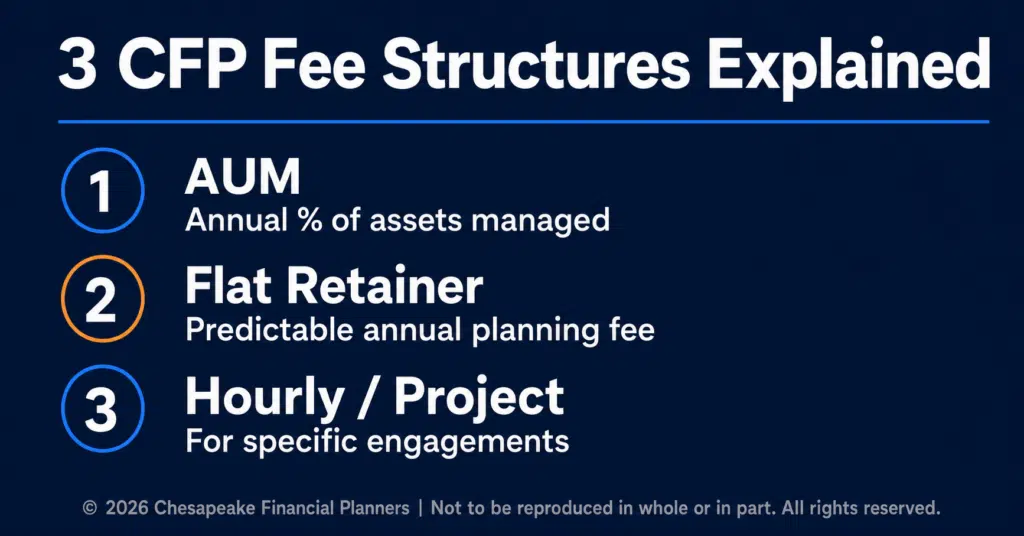
The financial planner cost in Maryland comes down to three structures: a percentage of assets under management, a flat annual retainer, or hourly and project-based fees. A fourth model, commission-based, is technically not a fee you pay directly but still affects your total cost.
Assets Under Management (AUM). This is the most common structure for investment management. The advisor charges an annual percentage of the assets they manage for you, typically 0.35% to 1.30% depending on portfolio size and firm structure. Larger accounts generally pay lower percentages. For a $500,000 portfolio at 1.00%, that is $5,000 a year. For $1 million at 0.75%, it is $7,500. The fee is usually deducted straight from the account, which makes it easy to forget you are paying it at all.
Flat retainer or annual planning fee. A growing number of fiduciary practices in Maryland charge a flat yearly fee for ongoing planning, separate from or in addition to investment management. Retainers commonly run $2,500 to $10,000 or more per year. Business ownership, equity compensation, and active tax strategy all add planning hours and push fees toward the higher end. The advantage is that the planner's pay is not tied to your account balance, which removes certain conflicts around portfolio construction and withdrawal timing.
Hourly or project-based. Some CFP® professionals work on an hourly or per-project basis, which is useful when you have one specific question rather than an ongoing relationship. Hourly rates in Maryland typically run $200 to $400. A one-time written plan might cost $2,000 to $5,000 depending on complexity. This fits a narrow engagement well, like evaluating a pension versus lump sum decision, but it suits ongoing planning less well, since real situations keep changing.
Commission-based. Some advisors are paid through commissions on products they sell, such as annuities, life insurance, or certain mutual funds. There is no direct fee to you, but the business model depends on product placement, which creates incentives a fee structure does not. The CFP Board holds CFP® professionals to a fiduciary standard when giving financial advice, so it is worth understanding exactly how anyone you are considering earns income before you engage.
What Does a CFP Cost at Chesapeake Financial Planners in Forest Hill?
Chesapeake Financial Planners, based in Forest Hill and serving Harford County and the Baltimore metro, operates a fee-based model. Planning fees run roughly $2,500 to $7,500 per year depending on complexity. Investment management fees range from 0.35% to 1.30% of assets, with the rate declining as the portfolio grows.
Jeff Judge, CFP® is direct about the fee conversation. "I want clients to know exactly what they're paying and why before we start," he says. "The planning fee covers the ongoing oversight, the tax planning, the retirement income modeling, the estate coordination. The investment fee covers the portfolio. They're two separate services, and we price them that way."
In Jeff's experience advising clients across Bel Air and Forest Hill, the people who feel best about their fees are the ones who understood the structure on day one. The ones who feel burned almost always discovered a layer of cost they were never walked through. That pattern is why the firm puts the full fee schedule in its Form ADV before any engagement begins.
What questions should I ask when interviewing a fee-only financial advisor in Maryland?
How Do You Decide Whether the Cost Is Worth It in Harford County?
Price matters, but focusing only on cost misses the real question: what are you actually getting? A planner who charges 1.0% and actively coordinates your Roth conversion strategy, tax-loss harvesting, Medicare planning, and estate updates is delivering a different service than one charging 0.50% to maintain a model portfolio with a yearly check-in. Both are called "financial advisors." The fee comparison only means something when the services being compared are genuinely comparable.
A few questions clarify value in a Harford County advisor search:
- What services are included? Investment management only, or comprehensive planning across tax, retirement, insurance, and estate?
- How often do we meet? Quarterly, annually, or only when you reach out?
- Who does the work? The CFP® professional directly, or mostly junior staff?
- What do you cover proactively? Responsive advisors react when asked. Proactive ones bring you opportunities you didn't know to ask about.
Working through Chesapeake Financial Planners' R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process of Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, every engagement begins by mapping the full financial picture before any recommendation. That upfront work is part of what the planning fee buys, and it is where much of the value gets created.
What should I look for in a financial advisor in Maryland?
What Should You Watch For When Comparing Advisor Costs Near Bel Air?
A few patterns deserve attention when you evaluate any planning relationship in Maryland. Vague fee answers are the first red flag. Registered investment advisors are legally required to disclose all fees and conflicts in Form ADV, so if you cannot get a clear answer about what you pay and how the advisor is compensated, ask for the document before signing anything. Watch for commission-heavy product recommendations, especially when a planner's first suggestion is a specific annuity or insurance contract. And watch for "all investment, no planning," where a portfolio gets managed but tax strategy, income planning, and estate coordination never enter the conversation.
| Fee structure | Typical Maryland range | Best fit |
|---|---|---|
| AUM | 0.35% to 1.30% of assets per year | Ongoing investment management with planning |
| Flat retainer | $2,500 to $10,000+ per year | Complex, ongoing planning needs |
| Hourly / project | $200 to $400 per hour; $2,000 to $5,000 per plan | One-time or narrow questions |
| Commission | No direct fee; built into product | Product-specific transactions |
What does a fiduciary financial advisor in Harford County do that a broker doesn't?
How do I find a CFP near Forest Hill, MD?
Frequently Asked Questions
Is there a minimum to work with a CFP in Maryland?
Many full-service practices set investment minimums, often in the $250,000 to $500,000 range, while others offer flat-fee or hourly services with no minimum at all. When you contact a Maryland practice, ask directly whether a minimum applies and whether there is a fee structure that fits your situation before assuming you are priced out.
Can I deduct financial advisor fees on my Maryland taxes?
Under current federal law, investment advisory fees are no longer deductible as a miscellaneous itemized deduction for individuals, a change made by the 2017 tax law. According to the IRS, those deductions remain suspended. Fees inside certain accounts or business structures may be treated differently, so confirm with your CPA.
What is the difference between a fee-only and a fee-based advisor in Maryland?
A fee-only advisor is paid only by client fees and earns no commissions, while a fee-based advisor charges fees and may also earn commissions on certain products. Both disclose compensation in Form ADV, but the distinction matters because it shapes the potential conflicts of interest you should understand before hiring.
How much does a one-time financial plan cost near Forest Hill, MD?
A one-time written financial plan from a CFP® professional in the Forest Hill and Harford County area typically costs $2,000 to $5,000, depending on complexity. Plans involving business ownership, equity compensation, or estate coordination land toward the higher end because they require more analysis and more planning hours.
How do I confirm what a financial planner in Maryland actually charges?
Ask for the planner's Form ADV Part 2 brochure, which every registered investment advisor must provide. According to the SEC, this document spells out all fees, compensation, and conflicts of interest. Reading it before you sign is the single clearest way to confirm what you will pay.
Choosing a planner is a decision worth getting right the first time. If you want a clear, no-pressure conversation about what financial planning would cost for your specific situation, Jeff Judge and the Chesapeake Financial Planners team serve families and business owners across Harford County, Bel Air, and Forest Hill. Schedule a free fit call at chesapeakefp.com.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
CFP Board owns the marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the U.S.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization’s initial and ongoing certification requirements to use the certification marks.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


