
What is a year-round tax planning calendar for retirees and pre-retirees?
Last reviewed: July 2026
A year-round tax planning calendar is a month-by-month schedule that spaces out the tax moves, like Roth conversions, tax-loss harvesting, required distributions, and charitable giving, that are far more effective when planned across the year than rushed in December. Most people treat taxes as an April event, but for retirees and pre-retirees the real savings come from acting at the right time throughout the year. This calendar lays out what to review each season so nothing valuable slips past its deadline.
On This Page
- Key Takeaways
- Why does tax planning need a year-round calendar?
- What tax moves belong in the first half of the year?
- What tax moves belong in the second half of the year?
- Related Topics Worth Reading
- Frequently Asked Questions
- Turning tax planning into a year-round habit
- Disclosures
Key Takeaways
- Tax planning is a year-round activity; the biggest savings for retirees come from acting on a schedule, not scrambling at year-end.
- Early in the year is for funding accounts: in 2026 you can contribute up to $7,500 to an IRA and $4,400 to a self-only HSA.
- Mid-year is for reviewing tax-loss harvesting and pacing Roth conversions before the year-end crunch.
- Year-end is the deadline for required minimum distributions, qualified charitable distributions, and final Roth conversions.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping Harford County and Baltimore-area families plan taxes year-round since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view: almost every client who feels rushed and overtaxed in December is really paying the price for decisions that should have been spread across the prior ten months.
Why does tax planning need a year-round calendar?
Tax planning needs a year-round calendar because the most valuable moves have deadlines, interact with each other, and work best when spread out rather than bunched into one month. A Roth conversion done in January gives you eleven months to see how the rest of your income lands; the same conversion in December is a guess made under a deadline.
The interaction is the real reason. A Roth conversion raises your income, which can affect how much of your Social Security is taxed, whether you cross a Medicare IRMAA threshold, and how much room you have left in your tax bracket. Tax-loss harvesting can offset gains you realize elsewhere. Charitable giving can lower the income a conversion pushes up. None of these decisions stands alone, and trying to coordinate all of them in the final weeks of December is how good opportunities get missed.
A calendar turns a stressful annual scramble into a series of small, deliberate checkpoints. You are not doing more work; you are doing the same work at the moments when it actually moves the needle.
What tax moves belong in the first half of the year?
The first half of the year is for funding accounts, cleaning up the prior year, and setting the table for the strategies you will execute later. These are the foundational steps, in order.
- In January, review your tax withholding and estimated payments so you are neither over- nor under-paying, and start funding your health savings account if you have a high-deductible plan. For 2026 the HSA contribution limit is $4,400 for self-only coverage and $8,750 for family coverage.
- In February and March, make prior-year IRA contributions before the filing deadline, since you can still contribute for the previous tax year up to April 15. The 2026 IRA limit is $7,500, with an extra $1,100 catch-up at age 50 or older.
- In April, pay your first-quarter estimated tax. The IRS sets the 2026 quarterly estimated-tax due dates at April 15, June 15, September 15, and January 15 of the following year. As the IRS warns, "If you don't pay enough tax by the due date of each payment period, you may be charged a penalty even if you're due a refund when you file your income tax return at the end of the year."
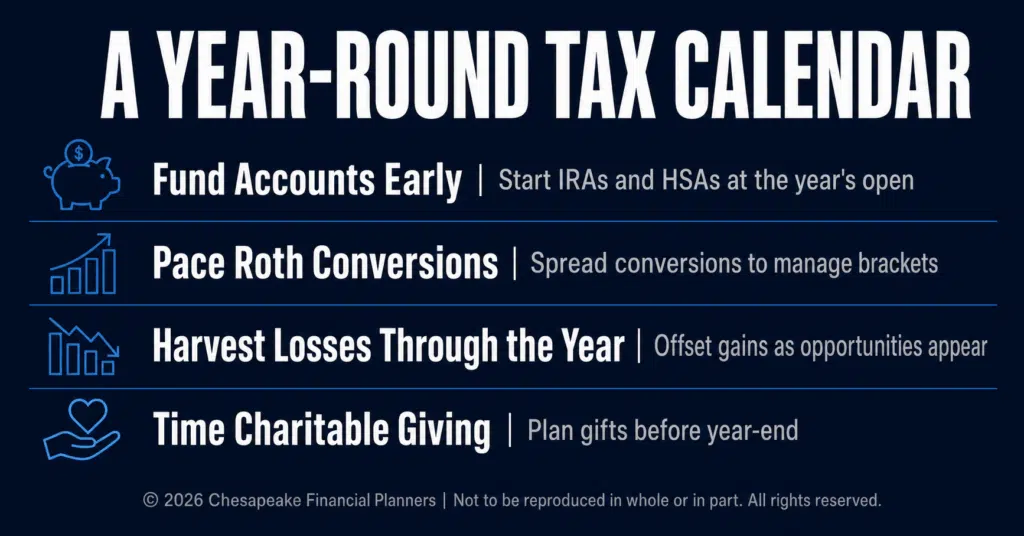
- Through the spring, set your Roth conversion target for the year based on your projected income and the top of the bracket you want to stay within, so you can execute it gradually rather than all at once.
This groundwork is what makes the second half of the year calm instead of frantic. As Jeff Judge puts it, "The people who convert smoothly in December are the ones who decided how much to convert back in April."
What tax moves belong in the second half of the year?
The second half of the year is for executing and finishing: harvesting losses, pacing conversions, and meeting the hard year-end deadlines that have no extensions. This is where the calendar earns its keep.
- From summer into fall, review your portfolio for tax-loss harvesting opportunities, selling positions at a loss to offset realized gains, while staying clear of the wash-sale rule, which the IRS uses to disallow a loss if you rebuy a substantially identical security within 30 days.
- At the fall midpoint, reassess your Roth conversion against your actual year-to-date income, since your real number is now clearer than your spring estimate, and adjust the remaining conversion accordingly.
- In October through December, take any required minimum distributions, which begin at age 73, to avoid the steep penalty for missing them.
- Also in the fourth quarter, make qualified charitable distributions, fund a donor-advised fund if you are bunching deductions, and complete your final Roth conversion before December 31, the hard deadline for the tax year.
A QCD is especially powerful here because it satisfies your required distribution without adding to your income, which can keep you under an IRMAA threshold or reduce how much of your Social Security is taxed. This is exactly the kind of sequencing the R.U.D.D.E.R. Method™ is built for. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, and the year-end execution lives in Execute and Empower, with a Reassess and Refine check before the calendar resets.
Related Topics Worth Reading
A tax calendar ties together conversions, giving, and Medicare planning. These related topics go deeper on the individual moves.
- How to size and time a Roth conversion across multiple years. When does a Roth conversion make financial sense and how do you execute it?
- How qualified charitable distributions satisfy RMDs tax-free. How Can I Donate From My IRA and Reduce Taxes?
- Why tax-loss harvesting can turn market dips into tax savings. How Does Tax-Loss Harvesting Work for High Income Investors?
- How your income decisions ripple into Medicare premiums. How does my Social Security claiming decision affect my Medicare premiums?
- Using the pre-RMD years to cut your lifetime tax bill. How do you use the years between retirement and RMDs to reduce lifetime taxes?
Frequently Asked Questions
When should I do a Roth conversion during the year?
You should decide your Roth conversion target early in the year and execute it gradually, with a final adjustment in the fourth quarter once your actual income is clear. Converting earlier gives you the rest of the year to see how other income lands and avoid accidentally crossing a tax bracket or Medicare IRMAA threshold. The hard deadline is December 31, since conversions count for the calendar year they occur.
What is the deadline for required minimum distributions?
The deadline for most required minimum distributions is December 31 each year, and RMDs begin at age 73 for most retirees. Missing an RMD triggers a significant penalty on the amount you should have withdrawn. Your first RMD can be delayed to April 1 of the year after you turn 73, but doing so means taking two distributions in one year, which can raise your taxable income and Medicare premiums.
When are estimated tax payments due in 2026?
For the 2026 tax year, the IRS sets quarterly estimated tax due dates at April 15, June 15, September 15, and January 15, 2027. Retirees with income from withdrawals, conversions, or investments that is not subject to withholding generally need to make these payments to avoid an underpayment penalty. Reviewing your withholding and estimates in January helps you stay on track all year.
When is the best time for tax-loss harvesting?
Tax-loss harvesting can be done whenever markets create opportunities, but a focused review in late summer through fall lets you plan offsets before the year closes. The goal is to sell positions at a loss to offset realized capital gains, while avoiding the wash-sale rule, which disallows the loss if you buy a substantially identical investment within 30 days. Year-end is the deadline, but waiting until December limits your options.
Do I really need a tax calendar if I have an accountant?
A tax calendar complements an accountant rather than replacing one, because most accountants prepare your return after the year ends, when the planning window has already closed. The moves that save the most, conversions, harvesting, QCDs, and charitable bunching, must happen during the year. A calendar, ideally coordinated with both your accountant and your financial advisor, ensures those deadlines are met while there is still time to act.
Turning tax planning into a year-round habit
The difference between reactive and proactive tax planning is a calendar, and for retirees that difference can be thousands of dollars a year in conversions paced correctly, distributions timed well, and giving structured for maximum benefit. You do not have to do everything at once; you have to do the right thing at the right time. If you found this helpful, our team at Chesapeake Financial Planners builds and runs this kind of year-round tax calendar with clients and their accountants. Visit chesapeakefp.com to learn more.
Want to go deeper? Our Roth Conversion Window walks through this step by step.
Prefer a different starting point? Our Tax Strategy Readiness Quiz is worth a look.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
A Roth IRA offers tax deferral on any earnings in the account. Qualified withdrawals of earnings from the account are tax-free. Withdrawals of earnings prior to age 59 ½ or prior to the account being opened for 5 years, whichever is later, may result in a 10% IRS penalty tax. Limitations and restrictions may apply.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


