

What Do You Need to Review and Change During Medicare Open Enrollment?
Last reviewed: July 2026
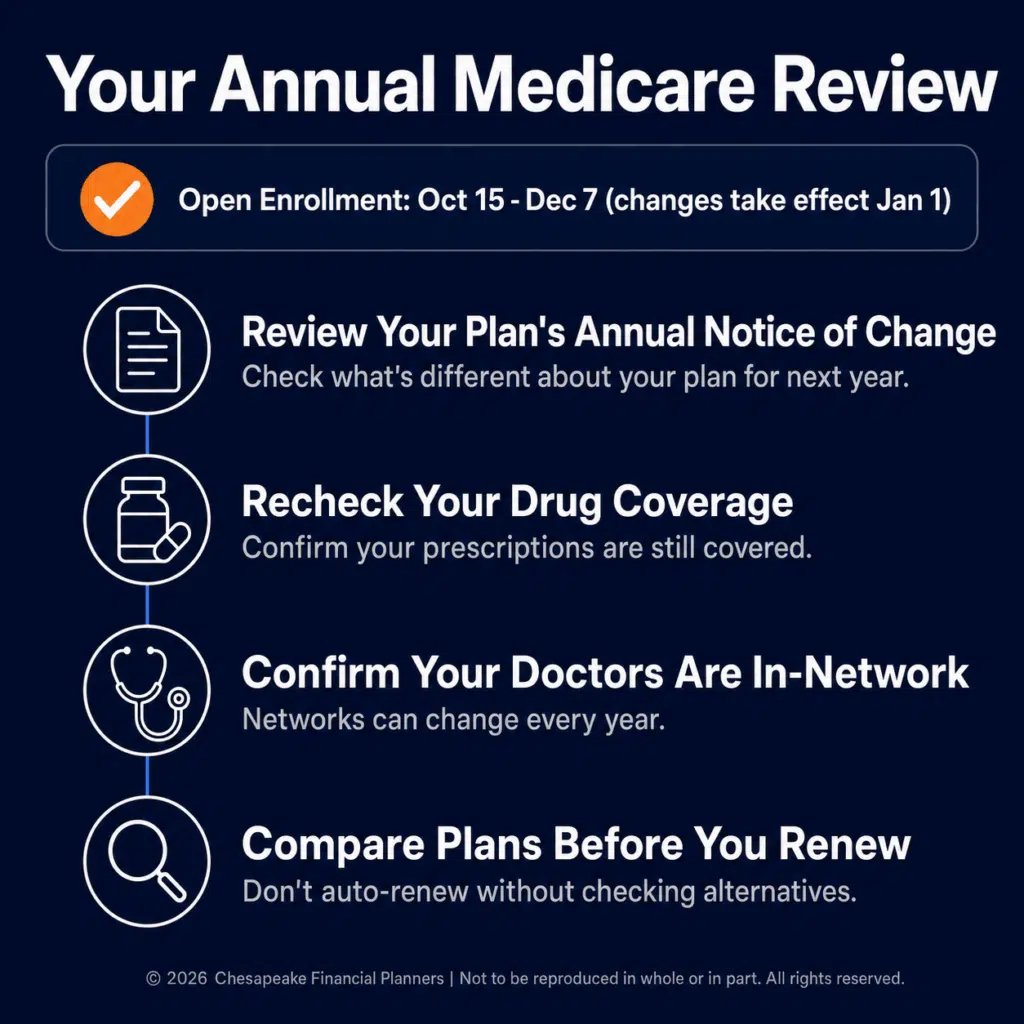
During Medicare open enrollment, you can switch Medicare Advantage plans, change or join a Part D prescription drug plan, move from Original Medicare to Medicare Advantage (or back), and drop or pick up drug coverage. This window runs every year from October 15 to December 7, and any change you make takes effect January 1. The one thing you generally cannot do during this period is switch or buy a Medicare Supplement (Medigap) plan without medical underwriting.
Key Takeaways
- Medicare open enrollment runs October 15 through December 7 every year, and changes take effect January 1.
- You can switch Medicare Advantage and Part D plans, but not Medigap plans without underwriting.
- The standard Part B premium is $185.00 per month in 2025, with most beneficiaries paying that base rate.
- Review your drug formulary every year, because plans change covered medications and pricing annually.
- Doing nothing keeps your current plan, but that plan's terms may have changed for the new year.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate Medicare and retirement healthcare decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff sees the same mistake every fall: people assume their plan stays the same and never re-check the drug formulary, then get surprised by a January price jump on a medication they take daily.
Medicare open enrollment is the one stretch each year when nearly every Medicare beneficiary can make a coverage change without justifying why. Most people ignore it. That is usually a mistake, because the plan you bought two years ago is rarely the same plan you have today.
What Can You Actually Change During Medicare Open Enrollment?
During the medicare open enrollment window of October 15 to December 7, you have four moves available. You can switch from one Medicare Advantage plan to another. You can drop Medicare Advantage and return to Original Medicare. You can join, switch, or drop a standalone Part D prescription drug plan. And you can move from Original Medicare into a Medicare Advantage plan.
What you cannot freely do is change your Medigap supplement. Outside of your initial six-month Medigap open enrollment window, insurers can require medical underwriting, which means they can charge more or deny you based on health history. This is the single most misunderstood rule of the season. The annual enrollment period and Medigap enrollment are not the same thing.
If you take prescription drugs, the drug plan review matters most. According to Medicare.gov, Part D plans publish a formulary each year, and that list of covered drugs, the tiers, and the copays can all shift from one year to the next. A drug that cost you $10 this year can land in a higher tier next year.
When Is the Medicare Annual Enrollment Period and When Do Changes Take Effect?
The Medicare annual enrollment period is always October 15 through December 7. There is no variation year to year. Any change you make during this window takes effect on January 1 of the following year. That timing is the part people forget. If you switch plans on December 1, you keep your old coverage through December 31 and start fresh on January 1.
This is different from the Medicare Advantage Open Enrollment Period, which runs January 1 to March 31 and only lets people already on a Medicare Advantage plan make one switch. Do not confuse the two. The fall window is broader and applies to more people.
Jeff Judge often reminds clients that the calendar is your friend here. You have nearly two months to compare plans, and the Medicare Plan Finder lets you enter your exact prescriptions and pharmacies to see real out-of-pocket costs. Most people spend more time picking a streaming service than picking the plan that covers their medications.
How Do You Decide Whether to Change Your Medicare Plan?
Start with what changed in your life and what changed in your plan. Both matter. If you switched medications, moved, or your doctor left your network, you have a reason to shop. If your plan raised premiums, changed its formulary, or dropped a provider, that is also a trigger.
Every fall, your plan sends an Annual Notice of Change. Read it. This document lists every difference for the coming year, including premium changes, deductible changes, and formulary changes. The Centers for Medicare & Medicaid Services requires plans to send it by late September, so it should be in your mailbox before the window opens.
The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Medicare open enrollment is a natural "Reassess and Refine" moment, because your healthcare needs and plan terms both shift over time and deserve an annual look. Jeff Judge notes: "Your Medicare plan and your health needs are both moving targets, so treating open enrollment as a routine annual checkup rather than a nuisance is one of the simplest ways retirees protect their healthcare dollars each year."
What Are the Different Parts of Medicare and What Do They Cover?
What Are the Costs to Watch During Open Enrollment?
Premiums are only part of the picture. The standard Part B premium is $185.00 per month in 2025, and higher earners pay an income-related surcharge known as IRMAA on top of it. If your income crossed a threshold, your Medicare premiums could rise even if you change nothing.
Pay attention to total expected cost, not just the monthly premium. A plan with a $0 premium can carry higher copays, a tighter network, or a worse drug formulary. According to the Social Security Administration, IRMAA surcharges are based on your tax return from two years prior, so a one-time income spike can follow you into your Medicare costs. This is exactly why retirees planning Roth conversions need to model the Medicare impact before converting.
How do Roth conversions affect IRMAA and Medicare Part B premiums?
How Much Should I Budget for Healthcare Costs in Retirement?
Frequently Asked Questions
What can I change during Medicare open enrollment?
During Medicare open enrollment, you can switch Medicare Advantage plans, move between Original Medicare and Medicare Advantage, and join, change, or drop a Part D prescription drug plan. You generally cannot switch or buy a Medigap supplement plan during this period without medical underwriting, which makes it a separate decision.
When is the Medicare annual enrollment period?
The Medicare annual enrollment period runs from October 15 through December 7 every single year. These dates do not change. Any plan change you make during this window takes effect on January 1 of the following year, so you keep your current coverage through the end of December before the new plan begins.
Can I change my Medicare supplement plan during open enrollment?
No, you generally cannot switch your Medicare supplement plan freely during the fall annual enrollment period. Medigap plans operate on a separate set of rules. Outside your initial six-month Medigap enrollment window, insurers can require medical underwriting, meaning they can charge more or deny coverage based on your health history.
What happens if I do nothing during Medicare open enrollment?
If you do nothing, you keep your current Medicare plan automatically into the new year. The catch is that your plan's terms may have changed. Premiums, deductibles, drug formularies, and provider networks can all shift, so staying put without reviewing your Annual Notice of Change can mean accepting higher costs by default.
How do I compare Medicare Part D drug plans?
Use the official Medicare Plan Finder at Medicare.gov, where you enter your exact prescriptions, dosages, and preferred pharmacies. The tool shows your real estimated annual cost for each plan, including premiums and copays. Comparing on total cost rather than premium alone usually reveals which plan actually fits your medication list best.
Does changing my Medicare plan affect my coverage immediately?
No, changes made during the October 15 to December 7 window do not take effect immediately. Your new plan begins on January 1 of the following year. You remain covered under your existing plan through December 31, so there is no gap in coverage when you switch plans during open enrollment.
Want to go deeper? Our Medicare and Social Security Guide walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


