
What Is a Cash Balance Plan for High-Income Business Owners?
Last reviewed: July 2026
A cash balance plan is a type of defined benefit plan that lets a high-income business owner set aside far more for retirement than a 401(k) allows, and deduct the full contribution from business income. If you already max your 401(k) and still have strong profit left over, a cash balance plan business owner in their 50s can often set aside two to four times the 401(k) ceiling in a single year. It works best for owners with steady profit and a real reason to reduce this year's taxable income.
Key Takeaways
- In 2026 a 401(k) caps employee deferrals at $24,500 and total additions at $72,000; a cash balance plan sits on top of both.
- A cash balance plan is a defined benefit plan, so contribution room scales up with age and can fund toward a $290,000 annual benefit limit.
- The plan fits owners in their late 40s to early 60s with strong, steady profit, a high tax bracket, and a late start on saving.
- Contributions are deductible and grow tax-deferred, but funding is a multi-year commitment with real actuarial and administrative costs.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping business owners in Harford County and the Baltimore metro area coordinate retirement plans since earning his CFP® certification in 2013, by using Chesapeake's signature process, the R.U.D.D.E.R. Method™. "The owners who benefit most are the ones who spent fifteen years building the business and never stopped to ask whether the 401(k) was actually the biggest lever they had," Jeff says. "It usually isn't."
Why Does the 401(k) Fall Short for High-Income Owners?
The 401(k) was built as a broad employee benefit, not as a tool for owners who want to shelter serious money. That is why its ceiling feels low the moment your income climbs. In 2026 an employee can defer up to $24,500, plus an $8,000 catch-up at age 50 or older. Add employer profit sharing and the total additions to one person's account still stop at $72,000 for the year.
For a practice or firm netting several hundred thousand dollars, that ceiling is well below the owner's real capacity to save. You have the cash flow to put away more, and a tax bracket that makes every deductible dollar count, but the account rules cap you. That gap between what you could save and what the 401(k) permits is exactly what cash balance plan contribution limits are built to fill. Jeff Judge often points out that owners fixate on their investment returns while quietly leaving a much bigger number on the table: the deduction they never claimed.
What Is a Cash Balance Plan, and How Does It Actually Work?
A cash balance plan is a modern defined benefit plan. A traditional defined benefit plan defines a future benefit and then works backward to the annual contribution needed to fund it, which is why allowable amounts run far higher than a 401(k) and rise as you age. The older you are, the fewer years the plan has to reach its target, so the required contribution is larger. The benefit the plan funds toward is itself capped, at a $290,000 annual benefit in 2026.
Where a cash balance plan differs from the pension your parents had is the account. Each participant has a hypothetical account balance that grows two ways: a contribution credit set by the plan formula, and an interest credit at a rate defined in the plan document. You get the clarity of an account statement with the funding power of a pension. Every contribution is deductible to the business, making it a tax-deductible retirement plan that lowers this year's taxable income, and the balance grows tax-deferred. At retirement most owners roll the account into an IRA and pay ordinary income tax as they withdraw, ideally in a lower-rate retirement. The big deduction lands in your high-earning years; the tax is deferred to years you may control better.
"Jeff Judge has watched profitable owners spend a decade assuming the 401(k) was the ceiling, when a cash balance plan layered on top could have sheltered several times as much and cut the tax bill every year they ran it."
Is a cash balance plan the same as the old-style pension your parents had? Not quite. It belongs to the same defined benefit family, but the hypothetical account and set interest credit make it far easier to read than a classic pension formula. Owners see a running balance they understand, which is why the plan has found new life among high earners.
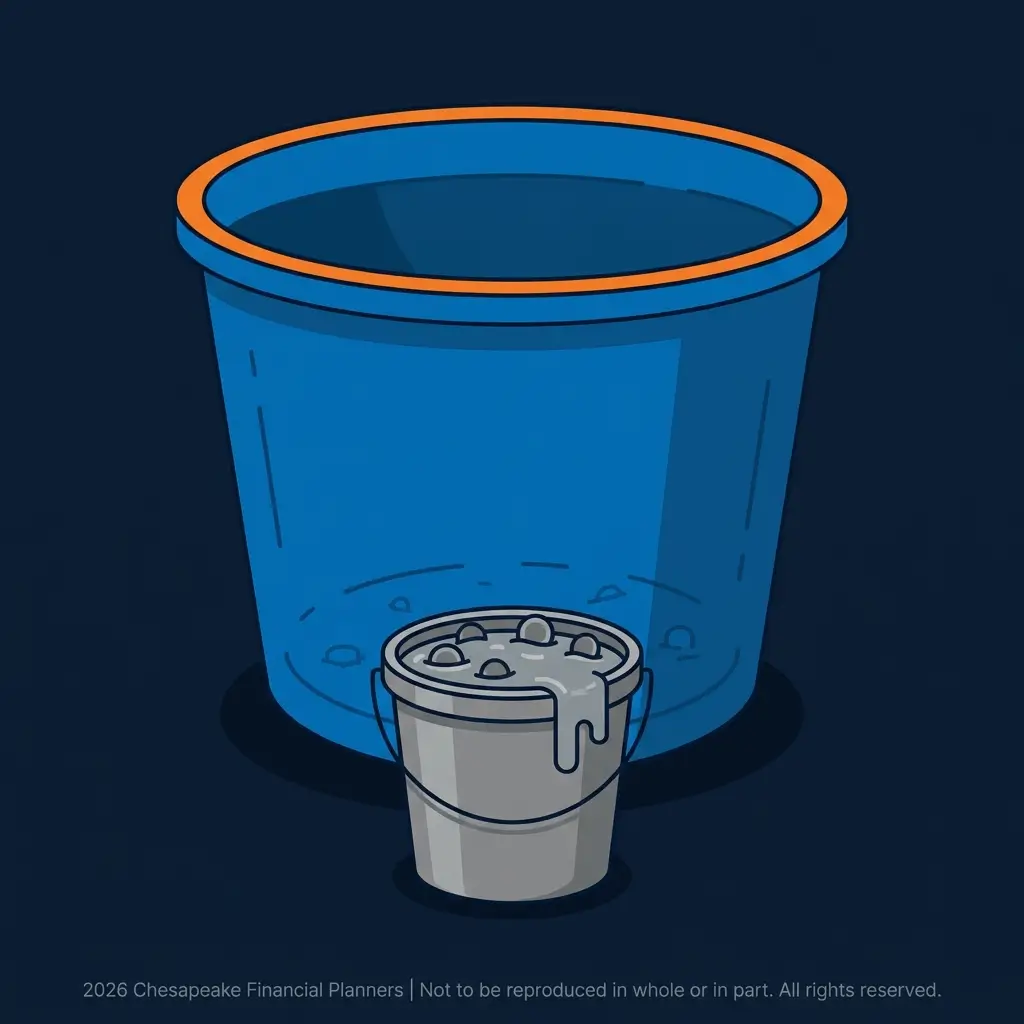
Here is how the two accounts compare when you run them together:
| Feature | 401(k) with profit sharing | Cash balance plan |
|---|---|---|
| 2026 contribution ceiling | Up to $72,000 in total additions | Age-based; can run well into six figures |
| Contribution type | Optional each year | Committed for several years |
| Who sets the amount | You choose | An actuary calculates it |
| Tax treatment | Deductible, tax-deferred | Deductible, tax-deferred |
Who Is the Typical Cash Balance Plan Business Owner?
The typical cash balance plan business owner is in their late 40s to early 60s, runs a business with strong and steady profit, got a late start on retirement saving, sits in a high tax bracket, and has cash flow to spare. The age matters because the allowed contribution scales up with age, so a compressed savings window actually works in your favor here.
Three traits separate a good fit from a poor one:
- Reliable, high income. Funding is effectively mandatory each year, not optional the way 401(k) deferrals are. Consistent profit is what makes that commitment safe.
- A late start you want to make up fast. Owners who reinvested in the business for years can compress a lot of saving into a short window, and the age-driven limits reward exactly that.
- An employee picture the plan can absorb. Nondiscrimination rules mean staff generally receive contributions too, often a few percent of pay through a paired profit-sharing plan.
Do I have to cover my employees, or is this just for me? If you have staff, you generally have to include them, usually through modest profit-sharing contributions of a few percent of pay for eligible workers. A small team keeps that cost manageable and the owner's share large. A large workforce changes the math and can make the plan far less appealing, which is why the design conversation always starts with your census.
What Are the Tradeoffs and Costs You Should Weigh?
A cash balance plan is powerful, but it asks for commitments a 401(k) never does. Name them honestly before you sign on:
- The annual funding commitment. Once the plan is in place, the contribution is not a year-by-year choice. An actuary certifies the required funding each year, and a down year can still leave you owing a contribution.
- Heavier administration. These plans need formal plan documents, an actuary's annual certification, and real yearly costs that a simple 401(k) avoids. Budget for the professional fees.
- Retirement-account restrictions. This is long-horizon money. Early access before age 59 1/2 can trigger penalties, so the dollars you put in should be dollars you will not need for years.
None of these are reasons to walk away. They are reasons to size the plan honestly, so the required contribution fits a number you can fund in a lean year, not just a strong one.
How Do You Decide If a Cash Balance Plan Is Worth It?
Start with three questions. Are you already maxing your existing plans with meaningful income still left to shelter? Is your profit strong and steady, not just strong this year? And what does your employee picture look like once staff contributions are added in? If the answers are yes, yes, and manageable, the plan usually earns its keep quickly.
The reason it gets missed is simpler than most owners expect: nobody puts it on the table. The 401(k) is the default that payroll providers and many advisors stop at, so the conversation ends before it reaches the plan that could have done the most. Jeff Judge sees this pattern constantly, and it is why Chesapeake runs the numbers before assuming the standard plan is the finish line. That structured approach is the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine.
Around Harford County and the Baltimore metro, the owners this fits are often closely held: a medical or dental practice, a professional services firm, or a government-contracting shop near Aberdeen with a handful of employees and strong margins. We see them across Forest Hill and Bel Air, usually in their 50s, finally able to save aggressively after years of pouring cash back into the business. For that owner, deciding whether to add a cash balance plan on top of an existing 401(k) with a profit-sharing plan is often the single largest tax decision of the year. It sits alongside the broader question of whether your exit alone can close the business owner retirement savings gap, and where a plan like this fits within tax planning for high-income earners. For the full picture of how these plans work at scale, our cash balance plans overview walks through the mechanics in depth.
Frequently Asked Questions
What is a cash balance plan for a business owner?
A cash balance plan is a defined benefit, pension-style plan that lets a business owner contribute and deduct far more than a 401(k) permits. Each participant has a hypothetical account that grows by an annual contribution credit and a set interest credit, giving the clarity of an account statement with the funding power of a pension.
How much can a business owner contribute to a cash balance plan in 2026?
The contribution is age-based and calculated by an actuary, not a flat number. Older owners can fund the most, because the plan has fewer years to reach its target benefit, which is capped at a $290,000 annual benefit in 2026. Many owners in their 50s contribute well beyond the 401(k) ceiling.
Can you have both a 401(k) and a cash balance plan?
Yes. Most owners run a cash balance plan alongside a 401(k) with profit sharing, stacking the two for a much larger deduction. In 2026 the 401(k) side allows up to $24,500 in deferrals plus employer contributions, and the cash balance plan sits on top of that.
Is a cash balance plan tax-deductible?
Yes. Contributions the business makes to a cash balance plan are generally deductible as a business expense, and the money grows tax-deferred until retirement. At retirement most owners roll the balance into an IRA and pay ordinary income tax as they withdraw, ideally in lower-bracket years.
Who should not open a cash balance plan?
Owners without steady profit should be cautious, because funding is a multi-year commitment rather than an optional yearly choice. If income swings widely, or you may need the cash soon, the plan's early-access penalties and annual funding requirement can create pressure. It suits reliable, high cash flow, not uncertain years.
Do cash balance plans require covering employees?
Usually yes. If you have staff, nondiscrimination rules generally require meaningful contributions on their behalf, often a few percent of pay through a paired profit-sharing plan. A small team keeps that cost manageable; a large workforce changes the math and can make the plan less attractive.
Is a Cash Balance Plan Your Next Move?
If you are the cash balance plan business owner this describes, maxing your existing plans with real profit still on the table, the next step is running your own numbers rather than guessing. Jeff Judge and the Chesapeake team serve families and business owners across Harford County and the Baltimore metro. Book a free fit call with Chesapeake Financial Planners.
A version of this article was originally published on Chesapeake Financial Planners' LinkedIn.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 1/2 may result in a 10% IRS penalty tax in addition to current income tax.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


