

What Is Sequence of Returns Risk and How Does It Wreck a New Portfolio?
Last reviewed: July 2026
Sequence of returns risk is the danger that poor investment returns early in retirement, or early in the life of a newly funded portfolio, do permanent damage that good average returns can never undo. The order of your returns matters as much as the average. Two portfolios can earn the exact same average return over 30 years and end up worlds apart, simply because one hit a bad stretch in year one while you were pulling money out, and the other hit that same bad stretch in year 25 when the account was smaller and the withdrawals less destructive.
If you just received a windfall and built a brand-new portfolio around it, this is the risk that should keep you up at night, not the headlines about whether the market is "due" for a correction.
On This Page
- Key Takeaways
- What Sequence of Returns Risk Actually Is
- Why a New Windfall Portfolio Is Uniquely Exposed
- How Sequence of Returns Risk Wrecks a Portfolio: A Side-by-Side Comparison
- Who Faces the Most Sequence of Returns Risk
- How to Protect a New Portfolio From Sequence Risk
- How the R.U.D.D.E.R. Method Handles Sequence Risk in Harford County
- Frequently Asked Questions
- Disclosures
Key Takeaways
- Sequence of returns risk means a bad return early in retirement permanently shrinks a portfolio because losses and withdrawals compound against you at the same time.
- The order of returns matters even when the long-term average is identical; timing, not just performance, drives the outcome.
- A newly funded windfall portfolio is most exposed in its first five to ten years, the "fragile decade."
- According to BLS data, inflation pressure forces retirees to withdraw rising dollar amounts, which deepens sequence risk in down years.
- A cash buffer, a flexible withdrawal rate, and disciplined rebalancing are the three most effective defenses.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement income and windfall planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often tells clients that the most dangerous year of their financial life is the one right after a big lump sum lands, because that is when a single bad market stretch can quietly cap their lifetime spending.
What Sequence of Returns Risk Actually Is
Sequence of returns risk is the threat that the timing of your returns, not the average, decides whether your money lasts. When you are adding money to a portfolio over decades, a bad early year barely matters because you have almost nothing invested yet. When you are withdrawing money, the math flips. A bad early year forces you to sell more shares at depressed prices to fund the same dollar of spending, and those sold shares never get the chance to recover.
Why does the order of returns matter if the average is the same?
The order matters because withdrawals and losses interact. Imagine two retirees who each average 6% over 30 years. The first hits a 20% loss in year one; the second hits that same 20% loss in year 30. The first retiree sells shares into a downturn while the account is at its largest and most fragile. The second sells into the same downturn when the portfolio has already done most of its compounding. Identical averages, very different endings. This is the heart of sequence of returns risk for any windfall.
I have watched this play out with clients who sold a business or received an inheritance, funded a portfolio, and then hit a flat or negative first 18 months. The ones who had a plan barely noticed. The ones who started full withdrawals immediately gave up years of future spending they will never get back.
Why a New Windfall Portfolio Is Uniquely Exposed
A newly funded windfall portfolio carries a special kind of sequence of returns risk because every dollar goes in at one moment in time. A 40-year saver dollar-cost-averaged through dozens of market cycles. A windfall recipient does not get that luxury. The entire sum is exposed to whatever the market does in the first few years, and that is exactly the window when sequence risk does its worst damage.
Researchers at Boston College's Center for Retirement Research have long documented that the years immediately surrounding the start of withdrawals carry outsized influence over whether a portfolio survives a full retirement. Some planners call this stretch the "fragile decade," the roughly five years before and five years after you start drawing income.
What is the fragile decade?
The fragile decade is the ten-year window around the start of portfolio withdrawals when sequence of returns risk peaks. During this stretch the portfolio is near its maximum value, withdrawals are beginning, and there is no remaining accumulation phase to absorb a bad market. A loss here is harder to recover from than the same loss earlier or later in life.
For a windfall recipient, the fragile decade can start the day the money lands. If you sold a company and intend to live off the proceeds, your fragile decade begins immediately, which is why the months right after a liquidity event deserve careful planning rather than a fast move into a fully invested, fully drawn-down posture.
How Sequence of Returns Risk Wrecks a Portfolio: A Side-by-Side Comparison
The cleanest way to see sequence of returns risk is to compare two portfolios that earn the identical set of returns in reverse order, with identical withdrawals. The table below illustrates the principle using a simplified $1,000,000 windfall portfolio, a fixed $50,000 annual withdrawal, and the same three returns (-20%, +5%, +25%) arranged in two different orders.
| Dimension | Portfolio A (bad year first) | Portfolio B (good year first) |
|---|---|---|
| Starting balance | $1,000,000 | $1,000,000 |
| Year 1 return | -20% | +25% |
| Year 2 return | +5% | +5% |
| Year 3 return | +25% | -20% |
| Annual withdrawal | $50,000 | $50,000 |
| Approx. balance after Year 3 | ~$933,000 | ~$1,043,000 |
| 3-year average return | 3.33% | 3.33% |
Same withdrawals. Same average return. A roughly $110,000 gap after only three years, driven entirely by the order. Stretch this over 30 years of retirement spending and the bad-first portfolio can run dry a decade before the good-first portfolio, even though both earned the same long-run average. That is sequence of returns risk in one picture.
This is why I tell windfall clients to stop obsessing over forecasting returns and start controlling the things that blunt a bad sequence: how much cash sits outside the market, how flexible the withdrawal rate is, and whether rebalancing is automatic or emotional.
How much can a bad first year cost over a full retirement?
A bad first year can cost a retiree several years of portfolio longevity. Withdrawing 5% from a portfolio that just dropped 20% means selling shares worth far less than planned, and those shares are gone before the recovery arrives. Over a 30-year horizon, an unlucky early sequence has historically been the difference between a portfolio that lasts and one that fails, even at identical average returns.
Who Faces the Most Sequence of Returns Risk
Sequence of returns risk is not a universal danger of equal weight for everyone. It concentrates in a few specific situations, and recognizing whether you are in one of them is the first real step toward managing it.
You face elevated sequence risk if you are a recent retiree drawing income from invested assets, a windfall recipient who funded a large portfolio in one shot, a business owner who just sold and is living off proceeds, or anyone whose spending is largely funded by selling investments rather than by guaranteed income like Social Security or a pension.
According to the Social Security Administration, the maximum monthly Social Security benefit at full retirement age in 2026 is $4,152, which for many high-net-worth households covers only a fraction of their spending. That gap is exactly the part funded by portfolio withdrawals, and it is the part exposed to sequence risk.
Why are high earners and business owners especially exposed?
High earners and recently liquidated business owners are especially exposed because their lifestyle spending is large relative to any guaranteed income they receive. When most of your retirement paycheck comes from selling assets rather than from a pension or annuity, a bad early sequence hits the entire income engine at once. There is no fixed-income floor absorbing the shock.
Many Chesapeake Financial Planners clients in Harford County fit this profile precisely. They built wealth running a company, sold it, and now need that lump sum to generate income for 30 years or more. For them, sequence of returns risk is not theoretical, it is the central planning problem.
How to Protect a New Portfolio From Sequence Risk
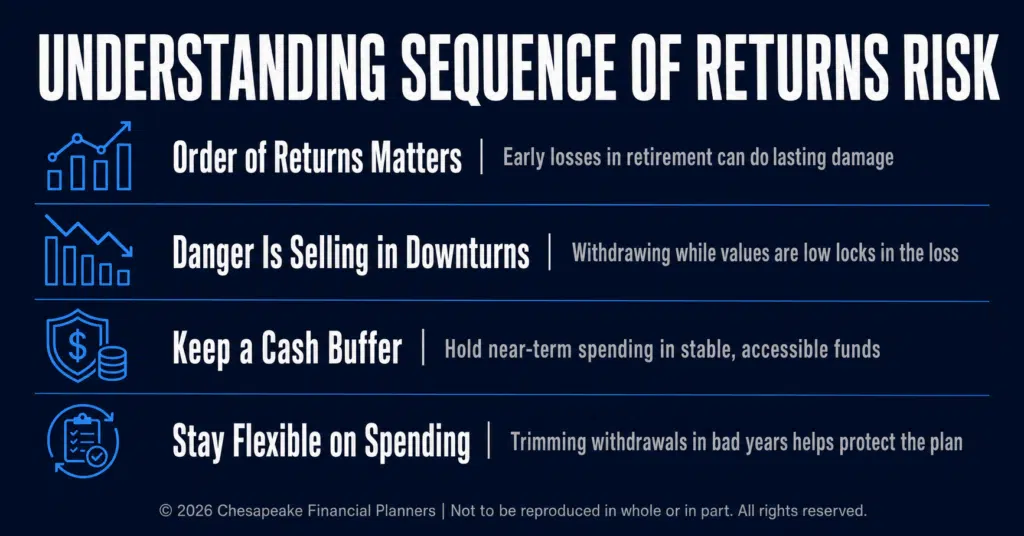
You cannot control the order of market returns, but you can build a portfolio that survives a bad early sequence. Three defenses do most of the heavy lifting, and the good news is that none of them depend on predicting the market.
The first defense is a cash and short-term bond buffer covering one to three years of spending. When the market drops, you spend from the buffer instead of selling depressed shares, giving the portfolio room to recover before you touch it again. The second defense is a flexible withdrawal rate: trimming spending modestly in down years dramatically reduces how many shares you sell at the bottom. The third defense is disciplined, rules-based rebalancing that forces you to buy low and sell high rather than freezing during volatility.
What is the role of a cash buffer in fighting sequence risk?
A cash buffer's role is to keep you from selling investments at a loss during the most fragile years. By holding one to three years of expenses in cash and short-term bonds, a retiree can fund spending from that reserve during a downturn instead of liquidating stocks at depressed prices. This single move neutralizes much of the early-sequence damage that wrecks new portfolios.
The SEC's Investor.gov resources reinforce a basic truth here: diversification and a disciplined plan matter more than timing the market. For windfall recipients, that discipline often means resisting the urge to deploy the entire lump sum at the market top, and instead phasing money in while a buffer protects near-term income.
There is also a tax dimension. IRS guidance on retirement accounts confirms that required minimum distributions begin at age 73 for many savers, which can force sales in a down year whether you like it or not. A buffer and a coordinated withdrawal sequence help manage that forced-sale risk.
I have a simple rule I use with clients in Bel Air and across Harford County: the year after a windfall is the year to be boring. Get the income plan in place, build the buffer, set the rebalancing rules, and only then worry about squeezing out extra return. The numbers do not capture how much money clients lose by doing this backwards, deploying fast and planning later.
How the R.U.D.D.E.R. Method™ Handles Sequence Risk in Harford County
The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. For a windfall recipient worried about sequence of returns risk, this process is built to slow down the most dangerous moment, the first deployment of a large lump sum.
How Does the R.U.D.D.E.R. Method™ Help Sequence of Returns Risk Planning?
The R.U.D.D.E.R. Method™ addresses sequence risk by building the defensive infrastructure — cash buffer, flexible withdrawal rate, phased deployment — before the first withdrawal is made, not after a bad year has already hit. In the Review and Recognize and Uncover and Understand stages, we map out exactly how much of your spending depends on portfolio withdrawals versus guaranteed income, which tells us how exposed you actually are. In Design and Develop, we size the cash buffer and set the flexible withdrawal rules. In Discuss and Decide and Execute and Empower, we phase the money in rather than dumping it at one price point. And in Reassess and Refine, we revisit the plan as your fragile decade unfolds. Jeff Judge notes: "We size the cash buffer and set the flexible withdrawal rules in the Design phase precisely because a market drop in year one of retirement is not the time to be making those decisions for the first time."
Families across Forest Hill, Bel Air, and the wider Baltimore metro use this process specifically because it removes emotion from the moment that matters most. As a fee-based firm headquartered at 2402 Scotlon Ct in Forest Hill, Maryland, Chesapeake Financial Planners sits close to the business owners and pre-retirees in Harford County who most often face a one-time liquidity event.
What Is the R.U.D.D.E.R. Method™?
According to Vanguard research on portfolio construction, disciplined rebalancing keeps a portfolio's risk profile from drifting, which directly supports the flexible-withdrawal and buffer strategies that fight sequence risk. And data from Morningstar's annual retirement spending research consistently shows that flexible withdrawal strategies improve portfolio survival rates compared with rigid fixed-dollar approaches, a finding that maps cleanly onto the sequence-of-returns problem.
The throughline across all of this is simple. You will never control whether the market hands you a good or bad sequence. You can absolutely control whether your portfolio is built to absorb the bad one. That distinction is the entire game for a new windfall portfolio.
Frequently Asked Questions
What is sequence of returns risk in simple terms?
Sequence of returns risk is the danger that bad investment returns early in retirement, while you are withdrawing money, do permanent damage that good later returns cannot repair. The order of your returns matters as much as the average. A loss in the first year of withdrawals hurts far more than the same loss decades later because you are selling shares at depressed prices.
Why is a windfall portfolio more exposed to sequence risk than a portfolio built over decades?
A windfall portfolio is more exposed because the entire sum enters the market at a single moment, with no dollar-cost averaging across market cycles. A saver who built wealth over 30 years absorbed many downturns along the way. A windfall recipient's full balance faces whatever the market does in the first few years, which is precisely when sequence risk causes the most damage.
What is the fragile decade and why does it matter?
The fragile decade is the roughly ten-year window around the start of portfolio withdrawals, about five years before and five years after, when sequence of returns risk peaks. It matters because the portfolio is near its largest value, withdrawals are beginning, and there is no accumulation phase left to absorb a bad market. Losses in this window are the hardest to recover from.
How does a cash buffer reduce sequence of returns risk?
A cash buffer reduces sequence risk by letting you spend from cash and short-term bonds during a downturn instead of selling stocks at a loss. Holding one to three years of expenses in reserve gives the invested portion time to recover before you touch it. This single strategy neutralizes much of the early-sequence damage that drains new portfolios.
Does sequence of returns risk affect everyone the same way?
No, sequence of returns risk concentrates in people who fund most of their spending by selling investments rather than from guaranteed income. Recent retirees, windfall recipients, and business owners living off sale proceeds face the most exposure. Households with large pensions or annuity income that covers most spending face far less, because their income engine does not depend on selling shares.
Can a flexible withdrawal rate really protect against a bad market?
Yes, a flexible withdrawal rate meaningfully improves a portfolio's odds of surviving a bad early sequence. Trimming spending modestly in down years means selling fewer shares at depressed prices, which preserves the share count that drives future recovery. Research from sources like Morningstar consistently shows flexible strategies outlast rigid fixed-dollar withdrawals across difficult market scenarios.
How should I invest a large windfall to avoid sequence risk?
You should avoid deploying the entire windfall at one price point and instead phase it in while building a one-to-three-year cash buffer for income. Set a flexible withdrawal rate and rules-based rebalancing before you fully invest. I advise windfall clients in Harford County to spend the first year getting the income plan right rather than chasing returns.
When should I talk to an advisor about sequence of returns risk?
You should talk to an advisor before you fully invest a windfall or start drawing income, not after a bad year has already hit. The fragile decade begins the moment large withdrawals start, so the planning window is at the front end. Chesapeake Financial Planners in Forest Hill, Maryland helps Harford County families structure that first deployment correctly.
Sequence of returns risk is the one threat where doing nothing, or moving too fast, costs the most. If you have just received a windfall or you are about to start drawing income from a newly built portfolio, understanding sequence of returns risk in those early months is what separates portfolios that last from ones that quietly run short. Ready to put a plan around it before your fragile decade begins? Jeff Judge and the Chesapeake team serve families and business owners across Harford County and the Baltimore metro. Schedule a free fit call at chesapeakefp.com.
This post is adapted from 'Sequence of Returns Risk Wrecks New Portfolios' originally published on Chesapeake Financial Planners' LinkedIn.
Want to go deeper? Our First 90 Days After a Windfall walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


