
Should I Do Roth Conversions Before I Retire?
Last reviewed: July 2026
For many pre-retirees, the answer is yes, but only in the right years and only up to a point. Roth conversions before retirement let you move money from a traditional IRA or 401(k) into a Roth IRA, pay the tax now at a known rate, and lock in tax-free growth and withdrawals for the rest of your life. The window between your last paycheck and the start of Required Minimum Distributions is often the best chance you'll ever get to do this at a low cost.
Key Takeaways
- Roth conversions before retirement work best in low-income years between your final paycheck and the start of RMDs at age 73.
- You pay ordinary income tax on the converted amount now, in exchange for tax-free growth and withdrawals later.
- In 2026, RMDs begin at age 73, according to the IRS.
- Converting too much in one year can trigger higher Medicare premiums and push you into a steeper tax bracket.
- The goal is to "fill up" lower tax brackets each year, not to convert everything at once.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement tax planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often reminds clients that the Roth conversion decision is rarely about this year's tax bill in isolation. It's about the next twenty years of tax bills, and most people are looking at the wrong one.
What Is a Roth Conversion and How Does It Work?
A Roth conversion is the process of moving money from a pre-tax retirement account, like a traditional IRA or 401(k), into a Roth IRA. You owe ordinary income tax on the amount you convert in the year you do it. In return, that money grows tax-free, and qualified withdrawals in retirement are tax-free too.
Think of it as prepaying tax at today's rate to avoid an unknown, possibly higher, rate later. There is no income limit on conversions and no annual dollar cap. You can convert $5,000 or $500,000. The only real constraint is the tax bill you're willing to pay this year.
The strategy matters most when you expect your tax rate in retirement to be the same or higher than it is during the conversion year. That sounds simple, but figuring out your future bracket is where most of the work lives. RMDs, Social Security, and Medicare surcharges all interact in ways that surprise people.
Why Do Roth Conversions Make Sense Before Retirement?
The years right before and just after you stop working are often your lowest-income years on paper. If you retire before age 73 and delay Social Security, you might have a stretch where your taxable income drops sharply. That gap is the opportunity.
Converting during those low-income years lets you pay tax in the 12% or 22% bracket instead of the 24% or 32% bracket you faced while working. You're essentially buying tax-free dollars at a discount.
There's a second reason that has nothing to do with your bracket today. Traditional IRAs force you to start taking Required Minimum Distributions at age 73, whether you need the money or not. According to the IRS, those distributions are taxed as ordinary income and can push you into higher brackets, increase the taxable portion of your Social Security, and trigger Medicare premium surcharges known as IRMAA. Roth IRAs carry no RMDs during your lifetime, so converting now shrinks the pile that will eventually be force-fed back to you as taxable income.
Jeff Judge has watched clients ignore this for years, then hit age 73 with a seven-figure IRA and a tax bill they never planned for. Converting steadily in the lead-up years would have spread that burden across a decade at lower rates. Waiting almost never makes it cheaper.
The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. A conversion plan lives squarely in the Design and Develop stage, where we model the tax impact across multiple years instead of one.
What Should You Prioritize Financially in the 5 Years Before Retirement?
When Are the Best Timing Windows to Convert?
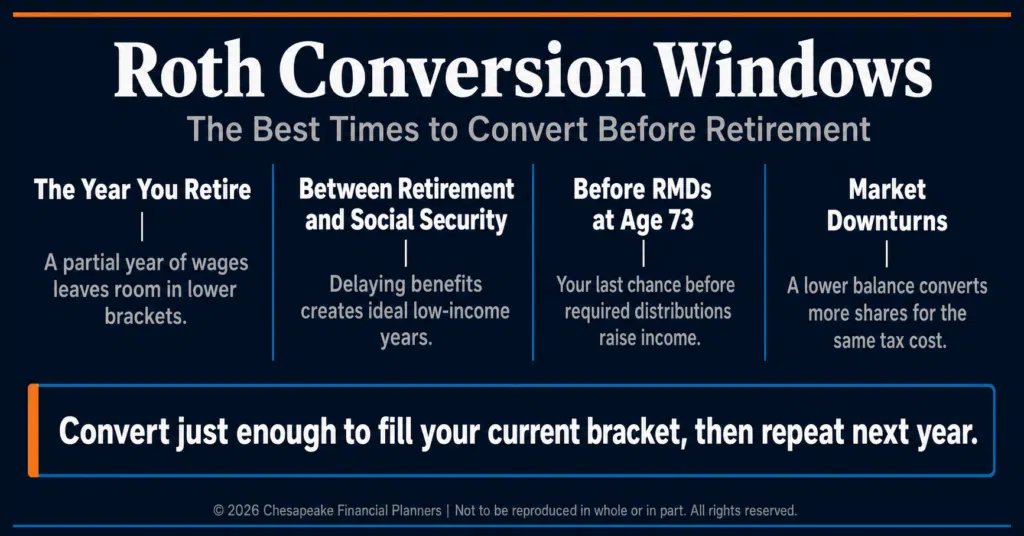
Timing is most of the strategy. A few windows tend to produce the lowest-cost conversions.
| Window | Why it works |
|---|---|
| The year you retire | A partial year of wage income can leave room in lower brackets before retirement income begins |
| Between retirement and Social Security (ages 62–70) | Delaying benefits creates low-income years ideal for converting |
| Before RMDs begin (ages 65–72) | Your last chance to convert before age-73 distributions raise your income |
| Market downturns | A lower account balance means you convert more shares for the same tax cost |
That last one matters more than people expect. When the market drops, your IRA balance is temporarily smaller. Converting then moves more shares into the Roth for the same tax bill, and the recovery happens tax-free inside the Roth.
The window between retirement and age 73 is the one most pre-retirees underuse. Social Security claiming decisions interact directly with this, which is why we coordinate the two. If you're weighing when to claim benefits, that choice shapes how much conversion room you have each year.
What Should You Prioritize Financially in the 5 Years Before Retirement?
How Much Should You Convert Each Year?
There's no single right number. The most common approach is to convert just enough each year to "fill up" your current tax bracket without spilling into the next one. You convert to the top of the 12% or 22% bracket, stop, and repeat next year.
For 2026, the IRS has set the standard tax brackets and the standard deduction. According to the IRS, the 2026 standard deduction for married couples filing jointly is $32,200, and for single filers it is $16,100. That deduction shields a chunk of income before conversions even start counting, which is why your first dollars converted are often the cheapest.
But the tax bracket isn't the only ceiling to watch. Two others matter just as much:
- IRMAA thresholds. A large conversion can raise your income enough to bump your Medicare Part B and Part D premiums two years later. The surcharge is based on your modified adjusted gross income.
- Social Security taxation. Conversion income can increase how much of your benefit gets taxed if you've already claimed.
This is where a one-year view fails people. A conversion that looks cheap on this year's return can quietly raise your Medicare premiums and your Social Security tax down the road. The planning work is in modeling all of it together.
How do Roth conversions affect IRMAA and Medicare Part B premiums?
What Are the Downsides of Converting?
Conversions aren't free, and they aren't right for everyone. The obvious cost is the tax bill in the conversion year, which you ideally pay from outside the IRA so the full amount keeps growing in the Roth. Paying the tax with IRA dollars defeats much of the benefit.
There's also the five-year rule. Each conversion starts its own five-year clock before the converted amount can be withdrawn penalty-free if you're under 59½. For most pre-retirees this isn't an issue, but it matters if you'll need the money soon.
If you expect to be in a much lower bracket in retirement and stay there, converting may not pay off. And if a conversion would push you over an IRMAA cliff or balloon your Social Security tax, the math can flip against you. That's why "how much" matters as much as "whether."
Frequently Asked Questions
What is a Roth conversion before retirement?
A Roth conversion before retirement is moving money from a traditional IRA or 401(k) into a Roth IRA during your working or early-retirement years. You pay ordinary income tax on the converted amount now, and in exchange all future growth and qualified withdrawals come out tax-free. The strategy works best in lower-income years.
When is the best time to do Roth conversions before retirement?
The best time is typically the low-income window between your final paycheck and the start of Required Minimum Distributions at age 73. Years when you've retired but delayed Social Security are often ideal, since your taxable income is temporarily low. Market downturns also create good conversion opportunities because lower balances mean lower tax cost.
How much should I convert to a Roth each year?
Most retirees convert just enough to fill their current tax bracket without spilling into the next one. The right amount depends on your other income, the 2026 brackets, the standard deduction, and whether a conversion would trigger higher Medicare premiums or additional Social Security taxation. Modeling several years together produces a better answer than any single rule.
Do Roth conversions affect my Medicare premiums?
Yes, large Roth conversions can raise your Medicare Part B and Part D premiums through the IRMAA surcharge, which is based on your modified adjusted gross income from two years earlier. A conversion that crosses an IRMAA threshold can increase your premiums even if it still keeps you in a reasonable tax bracket, so the surcharge needs to be modeled before you convert.
Will Roth conversions reduce my Required Minimum Distributions?
Yes, converting traditional IRA money to a Roth before age 73 directly shrinks the balance subject to future Required Minimum Distributions. Roth IRAs carry no RMDs during your lifetime, according to the IRS. By converting steadily in the years before RMDs begin, you reduce the forced taxable withdrawals later and gain more control over your retirement income each year.
Roth conversions before retirement are one of the highest-leverage tax decisions you'll make, and the difference between doing them well and doing them carelessly can run into tens of thousands of dollars. At Chesapeake Financial Planners, we model conversion plans across multiple years, accounting for brackets, IRMAA, and Social Security together. If you're weighing whether to convert, a second opinion costs you nothing. Visit chesapeakefp.com to learn more.
Want to go deeper? Our Roth Conversion Window walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
A Roth IRA offers tax deferral on any earnings in the account. Qualified withdrawals of earnings from the account are tax-free. Withdrawals of earnings prior to age 59 ½ or prior to the account being opened for 5 years, whichever is later, may result in a 10% IRS penalty tax. Limitations and restrictions may apply.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


