

Last reviewed: July 2026
A Roth conversion gap year is a low-income year when business owners can move money from a pre-tax account into a Roth at a much lower tax rate than usual. For most owners that year arrives right after a sale, during a soft revenue stretch, or in the early semi-retirement window before required distributions and Social Security begin. The whole strategy turns on one number: the tax rate you pay on the way in. Convert in a low year and you buy the same Roth dollars at a discount.
Key Takeaways
- A Roth conversion moves pre-tax retirement money into a Roth; you pay ordinary income tax now so qualified withdrawals later avoid further federal tax.
- The cheapest year to convert is a low-income year, which for business owners usually arrives after a sale or during a down year.
- In 2026 a married couple stays in the 24% bracket up to $403,550 before the rate jumps to 32%.
- Maryland does not tax qualified Roth distributions, and its pension exclusion reaches $40,600 at age 65.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has spent years helping families and business owners across Harford County and the Baltimore metro area plan around income swings and Roth conversions, using the firm's signature process, the R.U.D.D.E.R. Method™. "The owners who win at this have someone watching their income year over year, ready to say this is the year, here is how much, do it before December," Jeff says.
What Is a Roth Conversion Gap Year, and Why Does It Matter for Business Owners?
A Roth conversion moves money from a pre-tax account, like a traditional IRA or an old 401(k), into a Roth IRA. You pay ordinary income tax on the amount you move in the year you move it. After that the money grows and, assuming you are at least 59½ and have met the five-year rule, comes out without further federal income tax in retirement. The entire trade comes down to the rate you pay going in. Convert when your rate is low and you have made a smart trade. Convert when your rate is high and you have prepaid tax at a premium.
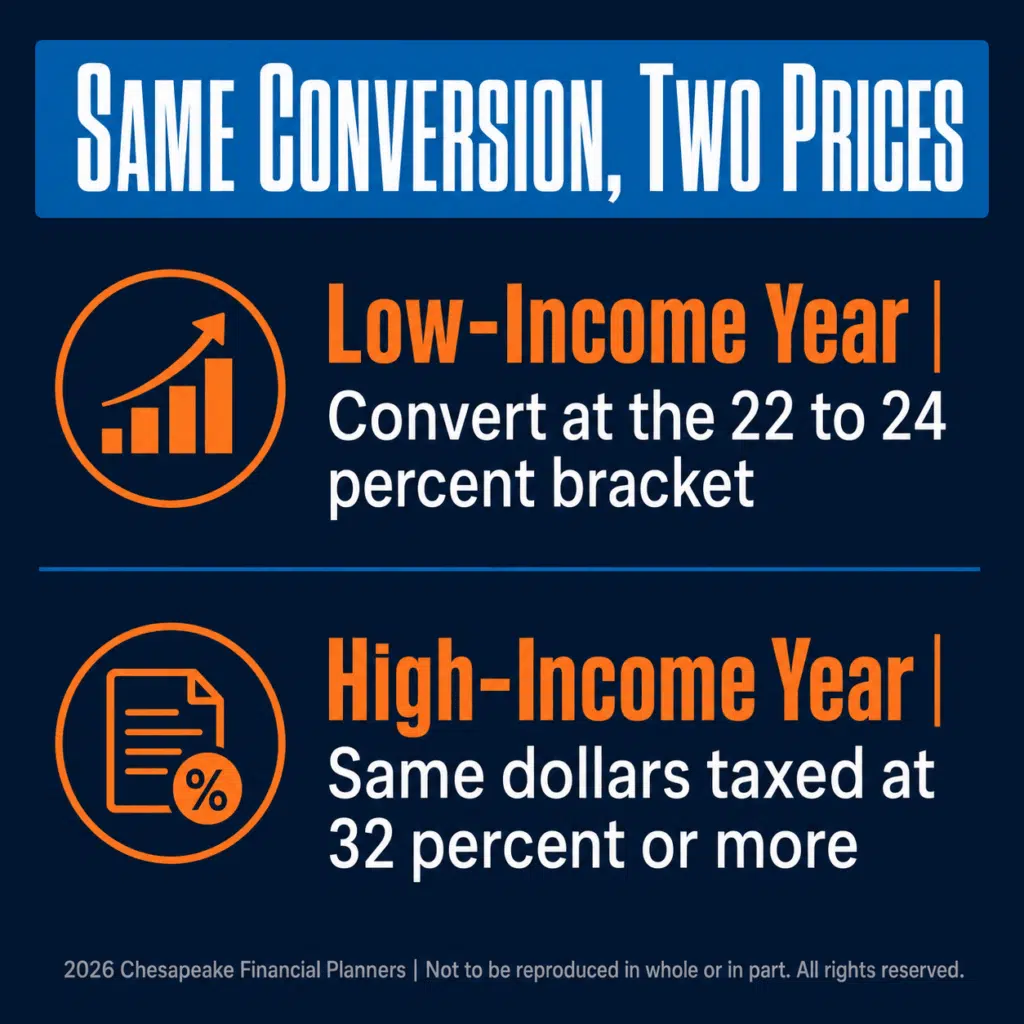
A gap year is simply a year when your taxable income drops far enough that a chunk of a conversion falls into a lower bracket than normal. Business owners get these more often than salaried workers because their income is lumpy. According to the IRS, in 2026 a married couple filing jointly stays in the 24% bracket on taxable income up to $403,550 before the next dollar is taxed at 32%. Those middle brackets are wide. In a quiet year you may have a lot of unused room to convert at 22% or 24% instead of the 32% to 35% you would pay in a strong year. Same conversion, very different price. The only variable that changed is the calendar.
When Do Business Owners Actually Get a Gap Year?
Owners do not earn a flat salary, and that volatility is the opportunity. Three windows show up again and again: the year after you sell the business, when the deal is closed and next year's income has not ramped back up; a revenue-dip year, when the business slows and your taxable income falls with it; and the early semi-retirement stretch, after you step back but before required distributions and Social Security start filling your return. Any one of these can drop you a bracket or two.
The problem is that the gap year almost always arrives disguised as something louder. The year after a sale, all your attention is on the transaction and what comes next. In a down year, you are focused on the business itself. The bracket sitting wide open is the last thing on your mind.
"In my experience, owners spend a full low-income year focused on the deal in front of them, only to realize afterward they let the single best conversion window of their lives close untouched." – Jeff Judge, CFP®
There is also a psychological hurdle. A conversion feels like volunteering to write the IRS a check you did not have to write this year. That instinct is exactly backward in a gap year, because the alternative is writing a bigger check later on the identical dollars.
How Much Should You Convert in a Roth Conversion Gap Year?
The guiding idea is to fill the bracket: convert just enough to use the room left in your current, lower bracket without spilling into the next one. Here is the simplified math. Say a couple has a quiet year with about $150,000 of taxable income. Their 24% bracket runs to $403,550, so they have roughly $250,000 of headroom they could convert at 24% rather than the 32% or higher they would face in a normal year. On a six-figure conversion, that eight-point difference is real money kept in the family instead of sent to Washington.
How do I know how much room I have? Start from your projected taxable income for the year, subtract it from the top of your current bracket, and that gap is your rough conversion capacity at today's rate. Because the number moves as the year unfolds, size it late, before December, once the year's income is mostly known.
| Scenario | Taxable income | Marginal rate on the conversion |
|---|---|---|
| Gap year (post-sale or soft year) | Around $150,000 | 24% |
| Normal earning year | Around $450,000 | 32% to 35% |
This is the kind of year-over-year sizing the R.U.D.D.E.R. Method™ is built to catch. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Reviewing income every single year is how a gap year gets spotted while there is still time to act on it.
What Does a Gap-Year Roth Conversion Do for You Later?
A well-timed conversion does three things. First, you pay the tax at a lower rate, which is the whole point. Second, you shrink the traditional balance that will one day drive your required minimum distributions, so the forced withdrawals in your 70s are smaller and less likely to push you into a higher bracket. The IRS requires most savers to begin taking those distributions at age 73, and every dollar you convert early is a dollar that never has to come out on the IRS's schedule. Third, you build a pool of Roth money you can draw on in a future year when you want to keep taxable income down.
That third benefit is easy to underrate. Does a Roth conversion affect my Medicare premiums? Yes, and it cuts both ways. A conversion adds to your income now, which can raise your Medicare Part B and Part D premiums about two years later through the income-related surcharge known as IRMAA. For 2026, Kiplinger reports the first surcharge tier begins at $218,000 of modified adjusted gross income for a married couple. But once the Roth is funded, you can pull from it in a later year without adding to that income figure at all, which gives you a lever to stay under a surcharge line or a bracket threshold.
Jeff Judge often reminds business-owner clients that a conversion is never a standalone decision. It ripples into how much of your Social Security gets taxed and into those Medicare surcharges two years down the road, so the amount has to be sized against the whole picture, not just this year's bracket.
Why Does the Gap Year Matter More for Maryland Business Owners?
For owners here in Harford County, the gap year carries an extra layer of value. Maryland taxes withdrawals from traditional IRAs and 401(k)s as income, but it does not tax qualified Roth distributions. Converting during a low-income year lets you pay the state tax on those dollars once, at a low federal rate, and then draw them later with no Maryland tax on the qualified distribution. There is a second wrinkle. Maryland's pension exclusion for residents 65 and older reaches $40,600 in 2026, but it phases down against your Social Security benefits, which limits how much traditional-account income it can shelter. That makes the pre-RMD gap years, before Social Security and required distributions crowd the exclusion, a genuinely useful window for Maryland owners.
Chesapeake Financial Planners sits in Forest Hill, and a large share of the owners we work with built or sold companies around Aberdeen and the rest of Harford County. We see the same pattern locally: a strong exit year, a quiet year or two, and a Roth conversion window that opens and closes without anyone naming it. Jeff Judge has watched more than one local owner spend that entire quiet stretch heads-down in the next venture, only to look up and find the cheapest conversion years of their life already behind them. If you are thinking about retiring in Maryland or planning around a sale, the coordination between your tax preparer and your planner is what turns a gap year into a decision instead of a missed footnote.
Frequently Asked Questions
What is a Roth conversion gap year?
A Roth conversion gap year is a low-income year when your taxable income drops enough that you can convert pre-tax retirement money into a Roth at a lower tax rate than usual. For business owners, these years typically follow a sale, a soft revenue stretch, or an early step back before Social Security and required distributions begin.
Why are business owners more likely to have a gap year than employees?
Business owners get a gap year more often because their income is lumpy rather than a steady salary. Revenue dips, the year after selling the company, and the early semi-retirement window can all pull taxable income into a lower bracket, opening room to convert at 24% instead of the 32% or more paid in a strong year.
How much should I convert during a gap year?
Convert enough to fill the bracket, meaning enough to use the room left in your current tax bracket without pushing income into the next one. Estimate your taxable income for the year, subtract it from the top of your bracket, and size the conversion late in the year once your income is mostly known.
Will a Roth conversion raise my Medicare premiums?
A Roth conversion can raise your Medicare premiums about two years later because it increases your income for the conversion year. In 2026 the first IRMAA surcharge tier for a married couple begins at $218,000 of modified adjusted gross income. Sizing the conversion carefully helps you stay under a surcharge threshold when it matters.
Do Maryland residents get an extra benefit from converting?
Maryland residents benefit because the state taxes traditional IRA and 401(k) withdrawals but does not tax qualified Roth distributions. Converting in a low-income year means paying tax once at a low rate, then drawing the money later with no Maryland tax on the qualified distribution. The state pension exclusion also phases down against Social Security income.
Ready to Spot Your Next Gap Year Before December?
The hard part of a Roth conversion gap year for business owners is not the math, it is noticing the year while you can still act on it. If you have a sale on the horizon, a slow stretch, or an early step back from the business, that is exactly when a second set of eyes on your bracket earns its keep. Schedule a call with Jeff Judge to look at whether this is your year and how much room you actually have.
A version of this article was originally published on Chesapeake Financial Planners' LinkedIn.
Want to go deeper? Our Tax Strategy Readiness Quiz walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Traditional IRA account owners have considerations to make before performing a Roth IRA conversion. These primarily include income tax consequences on the converted amount in the year of conversion, withdrawal limitations from a Roth IRA, and income limitations for future contributions to a Roth IRA. In addition, if you are required to take a required minimum distribution (RMD) in the year you convert, you must do so before converting to a Roth IRA.
To qualify for tax-free withdrawals, you must generally be age 59½ and hold the converted funds in the Roth IRA for at least five years. Each conversion has its own five-year period, and early withdrawals may be subject to a 10% penalty unless an exception applies. Income limits still apply for future direct Roth IRA contributions.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 ½ may result in a 10% IRS penalty tax in addition to current income tax.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


