
Last reviewed: July 2026
Inheritance family conflict rarely starts with the money. It starts with everything the money stirs up: ambiguity about what a parent actually wanted, an executor who goes quiet for a month, and a decades-old sibling scorecard that reopens the moment the will is read. After sitting with families through estate settlements, the dollars are seldom what does the damage, and the damage is largely preventable, not with a better will, but with a better process in the first few months.
Key Takeaways
- Inheritance family conflict is usually driven by ambiguity, role confusion, and reopened family history, not the size of the estate itself.
- The first 90 days are about family process, not investing; predictable communication and written decision rights head off most estate settlement disputes.
- Maryland imposes both an estate tax, with a $5 million exemption, and a 10% inheritance tax on non-lineal heirs.
- The 2026 federal estate tax exemption is $15 million per person, so most Maryland families owe no federal estate tax.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has helped families across Harford County and the Baltimore metro area work through inheritances and estate settlements since earning his CFP® certification in 2013, using Chesapeake's signature process, the R.U.D.D.E.R. Method™. "The families who come through an inheritance intact are almost never the ones with the simplest estate," Jeff says. "They are the ones who agreed on how decisions would get made before the hard decisions arrived."
Why Isn't the Money the Real Cause of Inheritance Family Conflict?
The money is rarely the real cause of inheritance family conflict, because grief, ambiguity, and old family history do the actual damage. An inheritance lands at the worst possible moment for clear thinking: you are grieving, and the grief arrives with paperwork, deadlines, and a group project you never signed up for, run with the people you have the longest history with.
Then ambiguity walks in. A will says who gets what, but almost never why. It does not explain what your mother hoped for the lake house, or why one child's share came through a beneficiary form and another's through probate. Grieving people fill those gaps with interpretation, and interpretation runs toward old fears. "She must have meant" is the most expensive phrase in any estate settlement.
Why does one sibling seem to get paid first? One sibling becomes the executor overnight, with legal duties and personal liability, while the others have expectations and no visibility. Accounts with named beneficiaries pay out within weeks while probate assets take months, so one sibling watches money arrive while another is still mailing death certificates to a court. When the executor also goes quiet because the process is slow, the silence reads as secrecy, and the structure itself starts manufacturing suspicion.
Underneath all of it, the oldest ledger in the family reopens: who paid for whose degree, who gave up years to caregiving, who borrowed and never repaid. I once watched a family spend more energy on a $40,000 disagreement than on the $1.5 million that moved without a hitch, because that $40,000 stood in for eleven years of one sister driving to every appointment. The estate did not create that imbalance; it handed it a microphone. Much of what looks like greed is really grief and old arithmetic, a pattern anyone who studies behavioral finance recognizes.
What Are the Most Common Flashpoints When Siblings Settle an Estate?
Three flashpoints show up again and again when siblings settle an estate: the family home, the executor imbalance, and the uneven history nobody wrote down. Naming them early keeps an inheritance dispute from hardening into a permanent rift.
The house comes first. One sibling wants to keep it, the others want to sell, and both are answering different questions: the keeper hears "you are erasing Mom," the sellers hear "you are holding my inheritance hostage." The fight stays unwinnable while the property carries two prices, one sentimental and one financial. What settles it is speed to clarity: an early appraisal, real buyout terms on paper, and a decision date. Families rarely fight over a number; they fight over a fog.
The executor imbalance comes second. The named sibling has authority without training; the others have a stake without information. The executor is allowed to get help, handing the administrative weight to professionals while keeping the decisions, and the family should hear that as diligence, not expense. An exhausted, resentful executor costs far more than any fee.
The uneven history comes third: lifetime gifts, undocumented loans, caregiving nobody invoiced. A will cannot settle what it never mentions, so those items reach the table dressed as a fairness argument. Naming that out loud, ideally with a neutral professional present, takes much of the sting out. What stays unspoken stays weaponized.
| Flashpoint | What each side hears | What actually settles it |
|---|---|---|
| The family home | "You are erasing Mom" vs "You are holding my share hostage" | An early appraisal, written buyout terms, and a decision date |
| The executor role | "You are hiding something" vs "You are second-guessing me" | Scheduled updates, shared documents, and permission to delegate |
| The uneven history | "You always got more" vs "I did all the work" | Naming the old debt out loud, with a neutral third party |
Jeff Judge tells families the same thing in nearly every first meeting after a loss: the estate settles once, but the family keeps showing up to Thanksgiving, so make each decision in a way you could defend at that table twenty years from now.
What Should Families Settle in the First 90 Days?
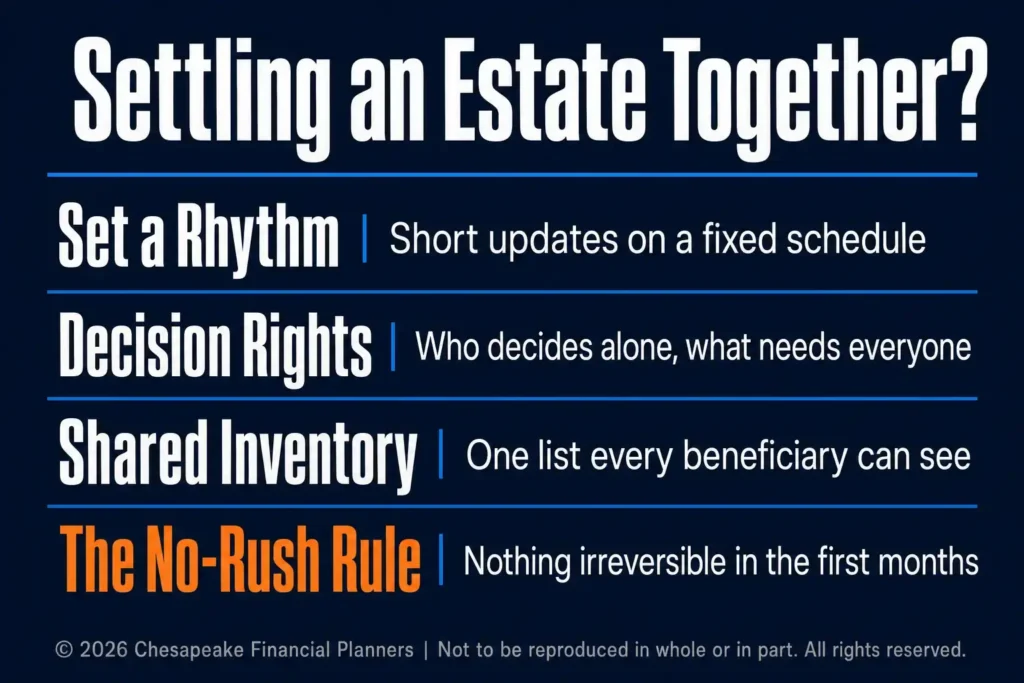
In the first 90 days, families should settle their process, not their portfolio. Where the money gets invested matters in year two; in month two, the investments can wait and the family process cannot. Seven things to put in place early:
- Set a communication rhythm. A short update on a fixed schedule, even if it is "nothing new, still waiting on the court." Silence is the accelerant in most estate conflicts.
- Put decision rights on paper. Spell out what the executor decides alone, what the group decides, and what waits for the professionals, before the first hard call arrives.
- Build a shared inventory. One document listing the accounts, properties, debts, and deadlines, visible to every beneficiary. Opacity costs goodwill that does not refill easily.
- Adopt the no-rush rule. Nothing irreversible happens in the first months without a stated reason. Early decisions are the ones people carry, and often cannot undo.
- Expect the phone to ring. Wealth events attract polished pitches. Agree on one sentence: "No investment decisions for six months, and everything goes through our planner first."
- Name the timeline out loud. Settlement runs on court calendars and moves slower than families expect, so saying so upfront keeps slowness from reading as stalling.
- Capture the why. If anyone knows the reason behind an uneven split or a bequest, write it down. Families make peace with a reason, never with a blank they fill in at 2 a.m.
This is the same discipline behind our first-90-days checklist for sudden wealth: decide the process before the money forces the pace.
How Do Maryland's Estate and Inheritance Taxes Change the Calculation?
Maryland changes the calculation because it is the only state that levies both an estate tax and an inheritance tax, so a local family faces a layer most national advice ignores. Maryland's estate tax exemption sits at $5 million per person, far below the 2026 federal exemption of $15 million. A household with a paid-off home, retirement accounts, and life insurance can quietly approach that state threshold without feeling wealthy, and the top federal estate tax rate still reaches 40%.
The second layer surprises people. Maryland's inheritance tax is 10% on property passing to non-lineal heirs, while lineal heirs, a spouse, child, grandchild, or parent, are exempt. A bequest to a niece, a nephew, a sibling, or a friend can carry a tax the same gift to a child would not. When that lands mid-settlement it reads as one more unfair twist, when it is really just Maryland law, which is why the interaction of Maryland's estate and inheritance taxes belongs in the conversation early.
We work with families across Forest Hill, Bel Air, and the rest of Harford County, and the Maryland layer is a routine part of every estate settlement we sit in on. Being local is part of why we can flag it early, whether a client is around the corner or handling a parent's estate from out of state.
When Does a Family Need a Neutral Professional to Settle an Estate?
A family needs a neutral professional the moment the process starts generating suspicion faster than answers. Many benefit from borrowing a structure, a professional whose job is the process rather than a side. The change is immediate: questions that would have been accusations across a kitchen table become agenda items in a meeting. "Why is this taking so long" gets asked to the advisor instead of at the brother, the executor stops being the face of every unwelcome answer, and the fight shifts from sibling versus sibling to family versus problem.
What does a defensible decision actually look like? For every major call, the reason gets written down when it is made. Sold the house in month five because the appraisal said one thing and the carrying costs said another. Distributed early because the court signed off. Two sentences per decision. Years later, memories of why will differ; the written record will not, and it shields the decision-maker as much as it reassures everyone watching.
A word to the person handling this alone, often a widow or a daughter who became the family's decision-maker overnight: you deserve professionals who talk to you, not past you. If someone explains your own estate to the person next to you, or treats your questions as interruptions, change professionals. Competence includes respect.
Coordination matters as much as credentials. The CPA sees the tax picture, the estate attorney sees the legal picture, and a financial planner sees how it lands in real life. When those three have never spoken, the family becomes the messenger service between offices, and many "conflicts" turn out to be two professionals answering different questions. That sequencing is the point of our approach: the R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. In practice it can be a single hour: the shared inventory on one screen, the timeline with real dates, the decision-rights list, and the tax calendar for the year ahead, which rarely looks the same after a wealth event. Our guide on who a windfall recipient should call first lays out that order.
The estate is a one-time event. The family is permanent. When that ordering drives the process, the money tends to sort itself out with calm.
Frequently Asked Questions
Why does inheriting money cause family conflict?
Inheriting money collides with grief, ambiguity, and decades of family history all at once. A will says who gets what but rarely why, so siblings fill the gaps with old assumptions and old fears. The friction is relational, not financial; the money is the stage, not the script.
What should you do in the first 90 days after an inheritance?
Focus on process, not investing. Set a communication rhythm, put decision rights on paper, build a shared inventory every beneficiary can see, and adopt a no-rush rule that holds any irreversible move. The portfolio can wait; the family agreements cannot, and that order matters most.
Does Maryland have an inheritance tax?
Yes. Maryland is one of the only states with both an estate tax and a separate inheritance tax. The inheritance tax is 10% on property passing to non-lineal heirs, while lineal heirs are exempt. So a bequest to a niece, nephew, or friend can carry a tax a gift to a child would not.
Who should serve as executor, and can they get help?
The executor is usually named in the will, and yes, they can and should get help. The role carries legal duties and personal liability, but the administrative work can be delegated to professionals while the executor keeps the decisions. Framed as diligence, not expense, that help prevents resentment.
How do you keep siblings from fighting over the family home?
Replace feelings with facts quickly. Get an early professional appraisal, put real buyout terms in writing, and set a firm date for the decision. Most fights are not about the price; they are about the fog around it, so speed to clarity defuses the standoff between siblings.
Here is the question worth sitting with: if difficult news arrived tomorrow, would everyone in your family know who is supposed to do what, and would they hear it from each other or from a lawyer? Settling that while nobody is grieving is one of the kindest financial decisions a family can make, and it is the surest way to keep inheritance family conflict from taking root. If your family is in the middle of a settlement, or hoping that day stays far off, schedule a call with Chesapeake Financial Planners and we will help you build the plan before anyone needs it.
A version of this article was originally published on Chesapeake Financial Planners' LinkedIn.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


