
Published: | Last reviewed: July 2026 by Jeff Judge, CFP®
Divorce financial planning for women centers on three things: getting a complete picture of marital assets, protecting retirement and Social Security rights that are often invisible during marriage, and rebuilding an independent financial life after the settlement. Women frequently take a bigger financial hit from divorce than men do, which makes the planning around it different in both stakes and strategy. The work isn't just dividing what exists today. It's making sure the numbers still hold up 20 years from now.
On This Page
- Key Takeaways
- Why Does Divorce Hit Women's Finances Harder?
- What Assets Get Overlooked in a Divorce Settlement?
- How Do You Divide Retirement Accounts Without a Tax Penalty?
- What Are Your Social Security Rights After Divorce?
- How Do You Rebuild Financially After the Settlement?
- Frequently Asked Questions
- Where to Go From Here
- Disclosures
Key Takeaways
- Women who divorce after age 50 see household income drop more sharply than men, making long-term planning essential.
- A divorced spouse can claim up to 50% of an ex's Social Security benefit if the marriage lasted at least 10 years, per the Social Security Administration.
- Retirement accounts split through a QDRO avoid the 10% early-withdrawal penalty when done correctly.
- The 2026 IRA contribution limit gives women rebuilding savings a defined annual target to work toward.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate major financial transitions like divorce since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched too many women accept a settlement that looked fair on paper and turned out to be anything but once the tax bills and cash-flow gaps showed up.
Why Does Divorce Hit Women's Finances Harder?
Divorce reshapes finances for everyone, but the data shows women absorb a steeper hit. Research summarized by the U.S. Government Accountability Office has long found that women's household income falls more sharply after a gray divorce than men's, and that gap widens with age. Part of this is structural. Women are more likely to have stepped back from careers to raise children, which lowers lifetime earnings, shrinks retirement contributions, and reduces their own Social Security record.
That career gap compounds. A woman who took five years out of the workforce didn't just lose five years of salary. She lost five years of 401(k) matching, five years of market growth on those contributions, and five years of building toward a higher Social Security benefit. By the time a divorce arrives at 55, that gap can represent six figures of missing retirement assets.
The emotional weight of divorce also pushes financial decisions to the back burner exactly when they matter most. Jeff Judge often tells clients that the worst time to make a permanent financial decision is in the middle of an emotional crisis, yet that's precisely when divorce forces the issue. Good planning slows the process down enough to make the math work.
How should women approach financial planning during major life transitions?
Why should divorce financial planning start before the papers are filed?
Divorce financial planning should start the moment you sense the marriage may end. Waiting until papers are filed puts you at a structural disadvantage, and the earlier you build a clear picture of what you own and owe, the harder it is for anyone to control or hide assets.
Gather the documents first. Collect copies of everything that touches your money: at least three years of tax returns, bank statements, investment and retirement account statements, mortgage documents, credit card statements, insurance policies, and any business valuations. Store copies somewhere your spouse cannot reach, such as a safety deposit box in your name only or secure cloud storage with a private login. The Consumer Financial Protection Bureau explains how to get your own credit reports so you can see every account tied to your name.
Understand the full picture. Many women have been less involved in day-to-day finances, sometimes by choice and sometimes because that is how the household ran. Check property records, review every insurance policy, and if your spouse owns a business, learn how it is structured and roughly what it is worth. Knowing the numbers before mediation puts you in a stronger position to negotiate.
Open accounts in your own name. Open a checking account, a savings account, and at least one credit card in your name only before any separation begins. If your only credit history is joint, a divorce can leave you unable to qualify for a lease, a car loan, or a mortgage on your own, and building separate credit is slow.
What Assets Get Overlooked in a Divorce Settlement?
The house and the checking account are obvious. The assets women lose money on are the ones nobody puts on the kitchen-table spreadsheet. A complete settlement accounts for every one of them, because what you don't value, you don't get credited for.
Commonly overlooked assets include:
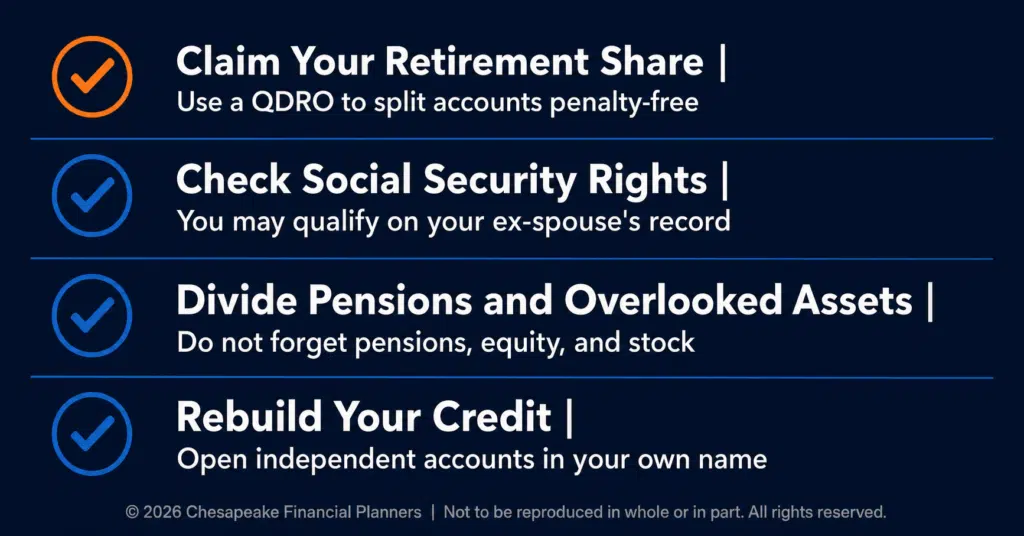
- Retirement accounts and pensions. A 401(k), 403(b), or traditional pensionA defined benefit retirement plan where your employer promises a specific monthly payment for life in retirement, typically based on salary and years of service. Pensions are increasingly rare in the private sector but remain common in government and some union jobs — and if you have one, understanding your payout options is an important financial decision. is often the largest marital asset after the home. Pensions are especially tricky because they pay out decades later and require a present-value calculation to divide fairly.
- Stock options and restricted stock unitsA form of equity compensation where your employer grants you shares of company stock that vest over a set schedule. When RSUs vest, their full value is taxed as ordinary income, which can create a significant tax event — and since you often have little control over timing, planning around vesting dates is an important part of managing your tax picture.. If a spouse earned these during the marriage but they haven't vested yet, they may still be marital property depending on state law.
- Tax carryforwards and refunds. Capital loss carryforwards and a pending joint refund have real dollar value.
- Health Savings Accounts and deferred compensationAn arrangement where a portion of your income is set aside today and paid out at a future date — typically retirement — when you may be in a lower tax bracket. Non-qualified deferred compensation plans are common among executives, but they carry real risk: if the company goes bankrupt, you're an unsecured creditor for those funds.. These rarely show up on a basic asset list but can hold meaningful balances.
- The tax basis of what you're keeping. A $300,000 brokerage account with a $50,000 cost basis is worth far less after taxes than a $300,000 Roth IRAA retirement account funded with after-tax dollars where your money grows completely tax-free and qualified withdrawals in retirement are also tax-free — including all the gains. There are no Required Minimum Distributions during your lifetime, making the Roth one of the most flexible and powerful long-term savings tools available.. Splitting accounts of equal face value can leave one spouse with a hidden tax bill.
That last point is where Jeff sees the most damage. Two accounts can show the same number on a statement and be worth thousands of dollars apart once you account for the tax owed on the way out.
Why is $200,000 of retirement savings not the same as $200,000 of home equity?
Picture a common scenario. Your spouse keeps a $200,000 401(k) and you keep $200,000 in home equity. On the settlement sheet it reads as a clean, equal split. In reality, the 401(k) is pre-tax money taxed as ordinary income when withdrawn, so its real value is lower than the sticker price. The home equity is illiquid and may carry capital gainsThe profit you make when you sell an asset for more than you paid for it. Short-term gains (assets held less than a year) are taxed at your ordinary income rate; long-term gains (held more than a year) qualify for preferential rates of 0%, 15%, or 20% — a meaningful difference that shapes many investment decisions. tax when you sell, plus selling costs, property taxes, and upkeep. Neither asset is worth its face amount, and they are not worth the same amount as each other.
Compare what each asset is worth after taxes, after liquidity, and after carrying costs, not what it says on the page.
Hypothetical example for illustration only; actual after-tax values depend on your tax bracket, state, and the asset's cost basis.
How Do You Divide Retirement Accounts Without a Tax Penalty?
You divide a workplace retirement account through a Qualified Domestic Relations Order, or QDROA Qualified Domestic Relations Order — a court order that allows retirement account assets to be divided between spouses in a divorce without triggering early withdrawal penalties or taxes at the time of the split. Without a QDRO, dividing a 401(k) or pension in divorce can create unintended and costly tax consequences.. A QDRO is a court order that tells a 401(k) or pension plan to pay a portion of one spouse's account to the other. Used correctly, it lets the receiving spouse take their share without triggering the 10% early-withdrawal penalty that normally applies before age 59½.
The mechanics matter. According to the Internal Revenue Service, funds transferred under a valid QDRO to a former spouse's own retirement account avoid both the early-withdrawal penalty and immediate income tax. If you instead take the money as cash, you owe income tax and possibly the penalty. The QDRO is the difference between a clean transfer and a costly mistake.
IRAs work differently. Splitting an IRA in divorce doesn't require a QDRO; it's handled as a "transfer incident to divorce" directly through the custodian. Get the language in the divorce decree right, and the IRS treats it as a tax-free transfer rather than a taxable distribution.
For 2026, the IRS set the IRA contribution limit at $7,500, with an additional $1,100 catch-up for those age 50 and older. Once a settlement is final, that limit becomes a concrete annual target for rebuilding. Knowing the number turns "I need to save more" into a plan with a ceiling you can actually hit.
What Are Your Social Security Rights After Divorce?
A divorced woman may be able to claim Social Security benefits based on her ex-husband's earnings record, and many women have no idea this option exists. The Social Security Administration allows a divorced spouse to receive up to 50% of an ex's full retirement benefit if the marriage lasted at least 10 years, the claiming spouse is currently unmarried, and is at least 62.
This benefit doesn't reduce what your ex receives, and your ex doesn't have to be collecting yet, as long as you've been divorced at least two years. You also get whichever is larger: your own benefit or the divorced-spousal benefit, not both stacked together.
The 10-year marriage threshold is one Jeff watches closely. A couple separating at nine and a half years sometimes has a real financial reason to wait a few months before finalizing, because crossing that 10-year line can mean a lifetime of higher benefits. It's the kind of detail that never shows up in the emotion of the moment but shapes income for decades.
How Do You Rebuild Financially After the Settlement?
Why is joint debt more dangerous than joint assets?
A divorce decree can assign a debt to your ex-spouse, but it does not change your contract with the lender. If your name is on a joint credit card or mortgage and your ex stops paying, the lender can come after you, and it shows up on your credit report. The Consumer Financial Protection Bureau explains that a divorce decree or property settlement may allocate debts to a specific spouse, but a creditor can still collect from anyone whose name appears as a borrower. The fix is to close joint accounts, refinance shared loans into one name, and confirm in writing that balances are paid off, not just reassigned.
Pull your credit reports from all three bureaus at AnnualCreditReport.com and check them again every few months during the process. Watch for accounts you forgot about and for activity on cards you assumed were closed. For the full sequence, see How do I rebuild my finances and establish financial independence after a divorce?.
What is different about divorce after 50?
Gray divorce, the term for divorce after age 50, carries financial risks that younger divorces do not, because there is far less time to recover. The divorce rate for adults over 50 has roughly doubled since 1990, according to Bowling Green State University's National Center for Family & Marriage Research, though it has leveled off in recent years. Work histories are often shorter because of career breaks, and a household budget built for two incomes must now stretch across far less.
One approach is to treat the first three years after the split as a savings sprint, since income is often higher than it will be in retirement and the children are often grown. In 2026 the IRA contribution limit is $7,500 and the 401(k) employee contribution limit is $24,500, and savers 50 or older can add catch-up contributions ($1,100 for an IRA and $8,000 for a 401(k)). The single-filer standard deduction for 2026 is $16,100.
Rebuilding starts the day the settlement is signed, and it follows a sequence. The goal is to convert a one-time settlement into a sustainable, independent financial life rather than a balance that quietly erodes. At Chesapeake Financial Planners, we walk divorcing clients through our R.U.D.D.E.R. Method™, the firm's six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. For a recently divorced woman, that framework turns a pile of new accounts and decisions into an ordered plan.
The practical first moves are straightforward. Update beneficiaries on every account and insurance policy, because an ex-spouse named on a 401(k) can still inherit it even after divorce if the form isn't changed. Rebuild an emergency fund as a genuine cushion now that there's only one income. Re-run the retirement projection from scratch using your numbers alone, not the household's old combined picture. And revisit estate documents, since a will, healthcare directive, and powers of attorney drafted during the marriage almost certainly name the wrong person now.
Articles in this topic
- What do women need to know about investing for financial independence?
- Should I work with a financial advisor who understands women’s needs?
Frequently Asked Questions
Do I get half of my husband's 401(k) in a divorce?
Not automatically half, but you are generally entitled to a portion of the retirement assets your spouse accumulated during the marriage, depending on your state's property laws. The split is executed through a Qualified Domestic Relations Order, which transfers your share into your own retirement account without triggering the early-withdrawal penalty.
How long do you have to be married to get your ex's Social Security?
You must have been married at least 10 years to claim Social Security benefits based on an ex-spouse's earnings record. You also need to be at least 62, currently unmarried, and divorced for at least two years if your ex hasn't started collecting yet. The benefit can be up to 50% of your ex's full retirement amount.
Will I have to pay taxes on my divorce settlement?
Most property transfers between spouses in a divorce are tax-free at the time of transfer, including a QDRO split of a retirement account. The taxes come later, when you actually withdraw from a pre-tax retirement account or sell an appreciated asset. That's why comparing accounts by their after-tax value, not their statement balance, matters so much in a settlement.
What is a QDRO and do I need one?
A QDRO, or Qualified Domestic Relations Order, is a court order directing a workplace retirement plan to pay part of one spouse's account to the other. You need one to divide a 401(k), 403(b), or pension without taxes and penalties. You do not need a QDRO to divide an IRA; that is handled as a transfer incident to divorce through the custodian.
How much should I save after divorce to rebuild my retirement?
Start with the 2026 IRA contribution limit of $7,500, plus the $1,100 catch-up if you are 50 or older, and contribute to any workplace plan up to at least the employer match. The right target depends on your age and the gap a divorce left in your retirement projection, which is worth re-running from scratch on your numbers alone.
Should I keep the house in the divorce?
Keeping the house feels safe, but it often isn't the strongest financial choice. A home ties up money you can't easily access, comes with ongoing costs on a single income, and may carry a built-in capital gains exposure when you eventually sell. Run the numbers on whether the equity would do more for you invested and diversified than locked in the walls.
Will I lose my health insurance after divorce?
If you were covered under your spouse's plan, you will need your own coverage. COBRA continuation coverage is available for up to 36 months after a divorce or legal separation, according to the Department of Labor, but it can be expensive. Build this cost into both your budget and your settlement.
Where to Go From Here
Divorce financial planning for women is less about the day the papers are signed and more about the 30 years that follow it. The settlement that protects retirement accounts, preserves Social Security rights, and accounts for taxes is the one that still works when you're 75. At Chesapeake Financial Planners, we work through this with clients regularly, and a second opinion on a proposed settlement costs you nothing. Visit chesapeakefp.com to learn more.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


