

How Can a CFP Financial Planner Help With Business Exit Planning?
Last reviewed: July 2026
A CFP financial planner helps with business exit planning by turning the proceeds of your sale into a tax-efficient retirement income plan, coordinating the timing of your exit around your tax brackets, and making sure the after-sale number actually funds the life you want. The role is not to sell the business. It is to make the money survive the sale, the taxes, and the next thirty years. Most owners optimize the deal and ignore the part that determines whether they ever have to work again.
Key Takeaways
- A CFP coordinates the sale proceeds, your tax bracket, and your retirement income so the after-tax number actually funds your life.
- The 2026 federal estate and gift tax exemption is $15 million per individual, which reshapes how owners gift equity before a sale.
- Long-term capital gains on a business sale top out at 20% federally, but timing and structure can shave that bill substantially.
- Section 1202 stock can exclude up to 100% of qualified gain for eligible C-corp owners.
- Most exit failures are planning failures, not deal failures: the price was fine, the after-tax life was not.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate business exits since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched more deals get wrecked by tax surprises after the sale than by anything that happened at the closing table.
What Does a CFP Actually Do in a Business Exit?
A CFP financial planner in a business exit handles the part the investment banker and the attorney do not own: what happens to your personal finances after the wire hits. The banker maximizes the sale price. The attorney structures the legal terms. The CFP makes sure the proceeds fund your retirement, minimize your lifetime tax bill, and stay coordinated with your estate plan.
Think of it as three jobs running at once. First, modeling what number you actually need so you do not sell too cheap or hold too long. Second, building a withdrawal and investment plan for a sudden, large liquidity event. Third, coordinating with your CPA and attorney so the deal structure does not blow up your tax return in the year of sale.
Jeff Judge often tells owners that the sale price is the headline and the after-tax retirement income is the story. A business that sells for $4 million can fund a very different retirement depending on whether you paid 20% or 32% on the gain, and whether the proceeds went into a plan or a brokerage account with no strategy behind it.
This is also where the R.U.D.D.E.R. Method™ earns its place. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. For a business exit, that framework keeps the sale tied to a real plan instead of a one-time event you react to.
How do you plan your business exit and protect what you've built?
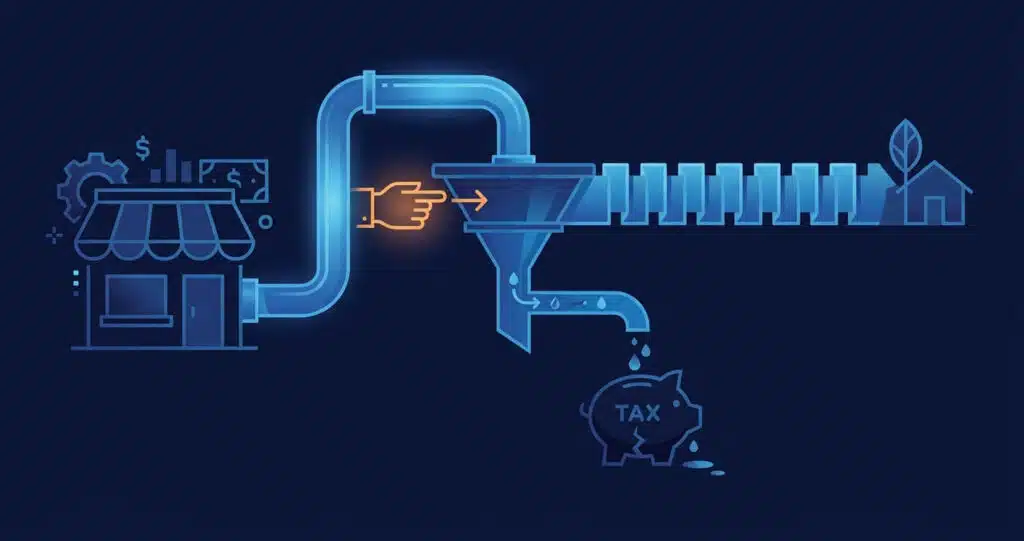
How a CFP Helps With Business Exit Planning: The Step-by-Step Process
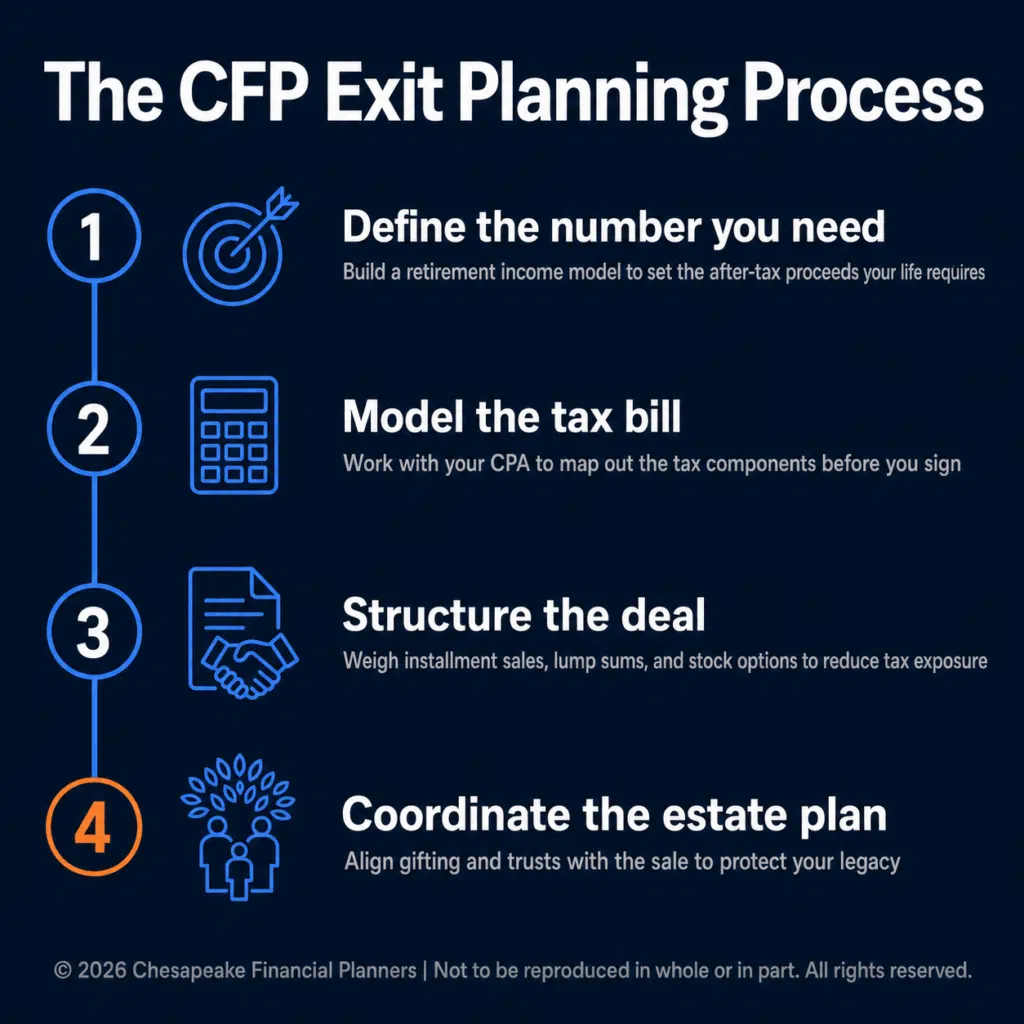
A CFP works through a business exit in a defined sequence. Each step protects a different part of your number. Here is the process most planners follow with an exiting owner.
Step 1: Define the number you actually need
Before any deal talk, the CFP builds a retirement income model: your spending, your timeline, your other assets, and the after-tax proceeds required to fund the rest of your life. This sets the floor. If the business needs to net $2.8 million after taxes to fund your retirement, you now know whether a $3.5 million offer is enough or whether you are leaving the table too early.
Step 2: Model the tax bill before you sign anything
The single largest line item in most exits is taxes. A CFP coordinates with your CPA to model federal and state capital gains, depreciation recapture, and any ordinary-income components of the deal. According to the IRS, long-term capital gains are taxed at 0%, 15%, or a top rate of 20% depending on your taxable income, before the additional 3.8% net investment income tax. Knowing your bracket before you negotiate structure can change how you take payment.
Step 3: Structure the deal for tax efficiency
Whether you take a lump sum, an installment sale, or a partial rollover changes your tax exposure. A CFP helps you evaluate spreading gain across years with an installment sale to stay out of the top bracket, or whether your C-corporation stock qualifies under Section 1202. The IRS allows eligible qualified small business stock to exclude up to 100% of qualified gain, which can be worth seven figures if you qualify.
Step 4: Coordinate the estate and gifting plan
A large liquidity event collides directly with your estate plan. The IRS confirms the 2026 federal estate and gift tax exemption is $15 million per individual under current law, and the annual gift tax exclusion is $19,000 per recipient. Gifting equity to heirs or trusts before a sale, while the business is valued lower, can move enormous value out of your taxable estate. A CFP times this with your attorney so the gifting happens before the price spikes.
Step 5: Build the post-sale investment and income plan
Once the wire arrives, you go from an illiquid business to a pile of cash that has to last decades. A CFP designs the allocation, sets up the withdrawal strategy, and builds a tax-aware drawdown so you are not paying unnecessary tax pulling income in retirement. This is the step owners most often skip, and it is the one that determines whether the money lasts.
Step 6: Reassess after the close
The plan is not finished at closing. Tax law changes, your spending changes, and markets move. A CFP revisits the plan annually so the strategy you built before the sale still fits the life you are living after it.
What is the complete financial planning guide for selling a business?
When Should You Bring a CFP Into the Exit?
You should bring a CFP into your business exit at least three to five years before you intend to sell, not in the month before closing. Early involvement is what unlocks the highest-value moves: multi-year tax planning, gifting before the valuation rises, and restructuring the business to maximize after-tax proceeds.
Jeff Judge has watched owners wait until they had a signed letter of intent before calling a planner. By then, most of the tax-saving levers are gone. You cannot retroactively shift gain into a lower bracket year, and you cannot gift equity at a discount once a buyer has set the price. The owners who keep the most are the ones who started planning while the business still had years of runway.
The earlier you start, the more the exit becomes a designed event instead of a tax ambush. A planner who has three years can spread income, fund retirement accounts, and reposition assets. A planner with three weeks can mostly just confirm the damage.
When is the right time for a business owner to start retirement planning?
What a CFP Does That Your CPA and Attorney Do Not
Your CPA files the return and your attorney drafts the documents, but neither owns the question of whether the proceeds actually fund your retirement. A CFP sits at the center, connecting the deal to your personal financial life.
| Role | Primary focus | What they do not own |
|---|---|---|
| Investment banker / broker | Maximizing the sale price | What you do with the money after |
| CPA | Filing the return, tax compliance | Long-term retirement income strategy |
| Attorney | Legal structure, contracts | Coordinating proceeds with your life plan |
| CFP financial planner | After-tax retirement income and coordination | Selling the business itself |
A CFP is the one who asks whether the deal you are about to sign leaves you with enough, in a structure you can live on, with a tax bill you saw coming. That coordination role is the difference between a good sale and a good retirement.
What tax issues do business owners face as they approach retirement?
Frequently Asked Questions
Can a CFP help me decide if my business sale price is enough to retire?
Yes. A CFP builds a retirement income model showing exactly how much after-tax proceeds you need to fund your lifestyle for the rest of your life. That number tells you whether an offer is enough or whether you are selling too early. Without it, you are guessing on the most important financial decision of your life.
How early should I hire a CFP before selling my business?
You should hire a CFP three to five years before you plan to sell. Early involvement unlocks multi-year tax planning, gifting equity before the valuation rises, and restructuring for efficiency. Owners who wait until a letter of intent is signed lose access to most of the tax-saving strategies that protect their proceeds.
Will a CFP replace my CPA or attorney in the sale?
No. A CFP works alongside your CPA and attorney, not in place of them. The CPA handles tax filing, the attorney handles legal structure, and the CFP coordinates the proceeds with your retirement income, estate plan, and long-term investment strategy. Each owns a different piece, and the best exits happen when all three communicate.
How does a CFP reduce the taxes on my business sale?
A CFP coordinates with your CPA to structure the deal for efficiency: spreading gain across years with an installment sale, evaluating Section 1202 qualified small business stock that can exclude up to 100% of qualified gain, and timing the sale around your tax brackets. According to the IRS, long-term capital gains top out at 20% federally before the net investment income tax.
What happens to the money after the business sells?
After the sale, a CFP designs an investment allocation and a tax-aware withdrawal strategy so the proceeds last for decades. You go from an illiquid business to a large cash position that needs structure. This post-sale income plan is the step owners most often skip, and it is the one that determines whether the money outlasts your retirement.
Ready to Plan Your Exit Around the Right Number?
At Chesapeake Financial Planners, we work through business exits with owners every week, coordinating the sale, the taxes, and the retirement income that comes after. If you are weighing this decision, a second opinion on whether your exit plan actually funds your life costs you nothing. Visit chesapeakefp.com to learn more about CFP help with business exit planning.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
CFP Board owns the marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the U.S.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization’s initial and ongoing certification requirements to use the certification marks.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


