
Financial Planning For Emerging Affluent
You Handle the Hustle. We’ll Handle the Numbers.
When you’re earning more than ever, but still feeling financially stuck, it’s time for a plan built around your life, not just your income
See if You’re a Fit
Featured In











You’ve built a great life. A rewarding career, a growing income, maybe even a few exciting assets in the mix. But let’s be honest, navigating all the financial pieces behind the scenes? That’s a full-time job in itself. One you don’t have the time (or frankly, the interest) to master solo.
Maybe you’ve outgrown DIY spreadsheets, HR pamphlets, and “my buddy says” advice. Or maybe a big life shift, like a career change, new business, or expanding family, has made it crystal clear: it’s time for a smarter, more coordinated plan. That’s where we come in.
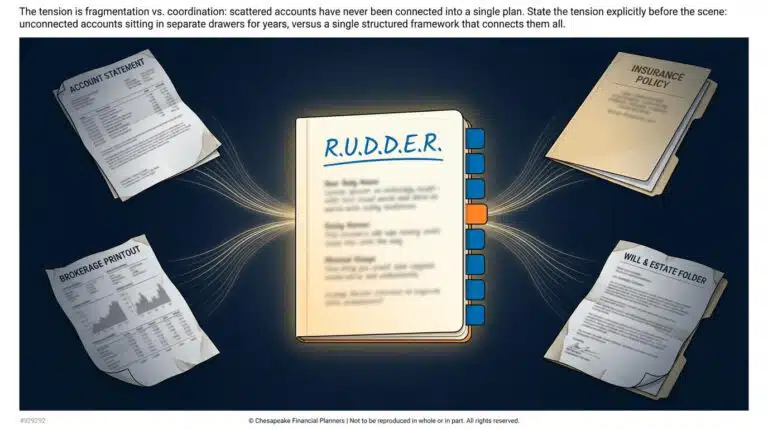
We get the tension you live with every day: You’re successful on paper, but your financial life doesn’t always feel stable. You’re earning more than ever but still wondering, “Am I making the right moves?” You want to grow wealth without sacrificing lifestyle, but also without making expensive mistakes.

Thomas Cowley
6 days ago
Mark and Jeff have handled my finances for over a decade. They have been great stewards for my investments which have grown substantially. They listen to my goals and give me recommendations and options to carry them out. I highly recommend them.
Jane Towery
3 months ago
I have been extremely pleased with Mark’s services over the last 15 years and would very highly recommend. Mark has taken the time to get to know my needs, interests, long and short term goals. We evaluate my portfolio yearly for any adjustments, reevaluation, or study trends. Mark objectively presents the pros and cons of options, answers questions, and leaves the final decision to me. I have never felt pressured and always appreciate how understood and listened to I have felt. More recently I have had some opportunity to work with Jeff as well. Mark and Jeff present a unified team who want to make your investments work for your needs.

Joyce Ducksworth
5 months ago
I have had the pleasure of entrusting my finances with Jeff and Mark for many years. Their expertise and advice are invaluable. My portfolio has grown significantly and has allowed me to retire comfortably with tremendous financial security. Mark is always available to answer my questions and provide solutions. I highly recommend Chesapeake Financial Planners.
stephen kinsley
5 months ago
Mark and Jeff have been my retirement advisors since 2011 and I could not be happier with them. They are knowledgeable and easy to talk with. They respond quickly to any questions and clearly explain all my options. I have been retired for 5 years and am fully confident that my financial future will continue to improve as it has so far with them. I would recommend them to anyone, and I only wish that I had met them sooner.
Bob Burris
6 months ago
I have been working with Mark and Jeff for 10+ years. I recently asked for a review of my financial plan and was provided outstanding feedback that provided me a much better solution.

Kim Wright
7 months ago
I am delighted with LPL. They've stayed with me for years and Jeff Judge has been exceptionally helpful. I've gotten good advice. He's managed my assets professionally and has always been available answer my questions.
He helped me consolidate several accounts into one manageable asset. He took the guesswork out of what could have been a complicated process.
I trust him to be there and guide me through issues in which I have no expertise. But he does this all the time and has proven to be trustworthy.
I do recommend Mr. Judge. You will not be disappointed.
Sharon Lewis
7 months ago
My husband and I met Mark and Jeff in 2014 when my husband left his job after 23 years. We met with Mark and Jeff to decide where to invest his retirement money. Before that decision was made, they took their time to understand our entire financial picture and based on that they gave us several options on where we could invest. They were very easy to talk with and made the conversation easy to understand. They are easy to get in touch with if you have questions and provide answers quickly. When it came time for me to retire, I also rolled my retirement investments into accounts managed by Mark and Jeff. We have also setup our estate planning as well as long term health planning based on advice we have had in review meetings in the years following our initial meeting. We have even referred our daughter and son in law to them. Highly satisfied with the investment service and customer service.

Andrew Benner
7 months ago
I check in with Mark a couple times a year and he always helps me keep my money that he manages growing. He also helps us with general advise regarding the type of places our 401k money should be (growth vs value, etc)

Mark Gray
9 months ago
Jeff has been helping me since 2014 with life insurance and retirement investment products. After a bad experience with a big insurance company, I found Mark and I’ve been working with him ever since. I’m successfully retired now and will begin drawing on my investments this year. I highly recommend Chesapeake Financial Planners for your retirement planning. – Mark G.
David Carrington
10 months ago
Jeff has been my financial advisor/ planner for several years. He has always guided me in the right direction and I have seen my retirement account continuously moving in the right direction. During the current uncertainty of the financial world right now Jeff has given me peace of mind that I continue to be in a safe and secure position with my finances. Jeff is very professional and quick to respond to my emails. As I approach my retirement years it is comforting to know my finances will be there when I need them.
Matt Hurson
11 months ago
I have been working with Jeff Judge and Chesapeake Financial Planners for about 3 years. Jeff has provided timely and well considered advice and acted promptly when I've needed access and changes to my portfolio. Highly recommend their services.

John Komoroski
12 months ago
We have worked with Jeff at Chesapeake Financial Planners for over 10 years. Throughout that time he has provided valuable investment and retirement information. Our investments have navigated this turbulent market far better than expected. Thank you Jeff.
Charles Gaither
12 months ago
I've been working with Chesapeake Financial Planners for a little over six years, and it's been an outstanding experience. They're knowledgeable, responsive, and consistently provide clear, personalized advice that aligns with my financial goals. Their long-term commitment and reliability have given me real peace of mind.
We’ll help you simplify the chaos, clarify the path, and keep things moving forward, strategically and sustainably. Our approach gives you:
- Clear, data-backed answers tailored to your unique situation
- A human sounding board who actually listens, no sales pitch, no shame
- Guidance that keeps pace with your life (and the markets)
- One place for all your financial questions and actual follow-through
You stay in control. We bring the plan, the accountability, and the calm.
So go ahead, keep doing what you do best. We’ll take care of the numbers, the strategies, and the “what now?” moments, so your financial life finally feels as aligned and confident as the rest of your world.
Frequently Asked Questions
How can I become a millionaire before 40?
Reaching a million dollars before 40 is achievable, but it comes down to what you do with your income, not just how much you earn. The six habits that consistently separate millionaires-at-40 from everyone else are: starting early so compounding has time to work, keeping your savings rate ahead of lifestyle creep, maxing tax-advantaged accounts like 401(k)s and Roth IRAs, taking calculated risks in entrepreneurship or equity, reducing your tax bill every year, and avoiding the wealth-destroying mistakes of market timingAttempting to buy and sell investments based on predictions about future market direction. Decades of research show that consistently timing the market is extraordinarily difficult — even for professionals — and attempts to do so usually result in worse returns than simply staying invested. and skipped insurance. Income is the raw material. Strategy is what turns it into wealth.
How much should I save to become financially independent?
To reach financial independence, a widely used target is saving 25 times your annual spending. That's the math behind the 4% ruleA retirement guideline suggesting you can safely withdraw 4% of your portfolio each year without running out of money over a 30-year retirement. It's a useful starting point, but your actual safe withdrawal rate depends on your specific situation, timeline, and market conditions., which suggests a portfolio of that size can sustain annual withdrawals of 4% indefinitely.
The 25x number is a starting point, not a finish line. Real factors that shift it include: when you want to stop working (early retirement demands more), other income sources like Social Security or rental income, tax exposure in retirement, healthcare costs before Medicare eligibility at 65, and how much flexibility you want if markets drop. For some people financial independence means $1.5 million. For others it's $5 million and a second home. The number is personal. The clarity is what matters.
Should I max out my 401(k) or invest elsewhere?
Whether to max your 401(k) or invest elsewhere depends on your plan quality, your timeline, and whether you need access before retirement age.
Max your 401(k) first if your plan has solid investment choices with low fees, you want to reduce your current taxable income, or you're targeting a traditional retirement in your 60s. Look beyond it if you're aiming for early retirement and need flexibility before age 59½, your plan's fund options or fees are poor, or you've already hit the contribution limit. Strong alternatives include a Roth IRAA retirement account funded with after-tax dollars where your money grows completely tax-free and qualified withdrawals in retirement are also tax-free — including all the gains. There are no Required Minimum Distributions during your lifetime, making the Roth one of the most flexible and powerful long-term savings tools available. or backdoor Roth, a taxable brokerage account for accessible liquidity, an HSA for tax-free medical savings, and a mega backdoor RothA strategy for high earners to contribute additional after-tax money to a 401(k) — beyond standard limits — and then convert those funds to a Roth account, dramatically increasing tax-free retirement savings. Not all plans allow it, so it's worth checking your plan documents or asking HR before assuming it's available to you. if your plan allows after-tax contributions.
Most people benefit from a mix. The sequence matters more than the choice.
What benefits should I negotiate when changing jobs?
When changing jobs, you can negotiate far more than salary. Signing bonuses, equity compensation, 401(k) vesting schedules, healthcare terms, remote or hybrid flexibility, extra PTO, professional development budgets, and severance protections are all on the table.
Here are the highest-value items to prioritize:
1. Signing bonus: especially important if you're leaving unvested stock or a bonus at your current employer
2. Equity compensation: RSUs, options, or performance shares can add significant long-term value
3. 401(k) match and vesting timeline: ask when you're eligible and how fast the match vests
4. Health coverage: compare premiums, deductibles, and whether the employer contributes to an HSA
5. Remote flexibility or relocation support: hybrid options and moving stipends are often negotiable
6. Additional PTO: easier to negotiate than base pay and often overlooked
7. Education and development budget: certifications, tuition reimbursement, conference access
8. Severance and contract terms: especially relevant in senior or executive roles
The headline number is rarely the whole story. Total compensation is what you're actually accepting.
When should I start working with a financial planner?
The right time to work with a financial planner is before you need one urgently. That usually means when income is rising faster than your strategy is, or when decisions are piling up without a clear framework.
Specific situations where a planner adds immediate value: you're earning more but not sure where to direct it, a major life change is on the horizon like marriage, kids, or a job switch, you've received equity compensation or a large bonus, you feel like you're managing okay but wonder if you're missing something, or you want someone to hold you accountable and take things off your plate.
Working with a planner isn't about wealth level. It's about wanting to make decisions with intention rather than inertia.
Am I on track to retire by 60?
Whether you can retire by 60 depends on five numbers: what you'll spend, how long you'll live, what income sources you'll have, how much you've saved and how it's invested, and how you'll manage taxes and healthcare in the gap before Medicare and Social Security kick in.
Most people who want to retire at 60 face two specific challenges. First, they need their portfolio to last 30 or more years, which is a longer runway than most retirement models assume. Second, they'll go roughly five years without Medicare eligibility and potentially longer without full Social Security benefits. Projecting those gaps with real numbers, not rough estimates, is how you find out whether you're on track or how close you are. The answer changes every time your income, savings rate, or investment mix shifts.
Should I pay off debt or invest my extra money?
For most people, the deciding factor is interest rate: high-interest debt above roughly 6% almost always beats investing it first, because debt paydown return is guaranteed while investment returns are not.
Pay down debt first if the rate is above 6%, the debt is non-deductible like credit cards or personal loans, or you're close enough to retirement that eliminating fixed expenses matters. Invest first if the debt is low-rate and manageable like a mortgage or student loans below 4-5%, you're behind on retirement savings and want compounding time on your side, or you have stable cash flow and a solid emergency fund already in place.
Most clients do both. Splitting extra dollars between debt paydown and investing lets you make financial progress while reducing the stress that high balances create. The right split is specific to your rate, your goals, and your timeline.
What’s the best way to balance saving and enjoying life now?
Balancing saving and enjoying life comes down to automation and intentionality, not deprivation. The people who do this well don't spend less, they spend deliberately.
Four practices that work consistently:
1. Automate savings before you see the money. Set contributions to retirement accounts, emergency funds, and short-term goals to transfer on payday. Enjoy what's left without second-guessing it.
2. Define what you're saving for. Vague savings goals lose to real spending every time. When you know the target, whether it's early retirement, a house, or career flexibility, the sacrifice has a point.
3. Use a values-based approach to spending. Spend freely on things that genuinely matter to you and cut back on what doesn't. That's different from cutting everything.
4. Increase savings rates with income, not just spending. Each raise is an opportunity to split the new income between lifestyle and long-term goals.
Progress and enjoyment aren't opposites. The plan just needs to make room for both on purpose.
How can I potentially optimize my taxes as my income grows?
Growing income creates both more tax exposure and more strategies to reduce it. The key shift is moving from reactive filing to proactive planning that runs year-round.
The most effective approaches for high earners:
1. Max tax-advantaged accounts in the right order: 401(k) for pre-tax reduction, HSA for triple-tax benefit, Roth IRA or backdoor Roth for tax-free growth, and 529A tax-advantaged savings account designed for education expenses, where contributions grow tax-free and withdrawals are tax-free when used for qualified education costs. Recent rule changes also allow unused 529 funds to be rolled into a Roth IRA, adding flexibility you may not have had before. plans if you have education goals
2. Use workplace benefits strategically: equity comp, deferred compensationAn arrangement where a portion of your income is set aside today and paid out at a future date — typically retirement — when you may be in a lower tax bracket. Non-qualified deferred compensation plans are common among executives, but they carry real risk: if the company goes bankrupt, you're an unsecured creditor for those funds. plans, FSAs, and employer HSA contributions all carry tax benefits many people overlook
3. Give through a Donor-Advised Fund: contribute appreciated stock instead of cash to avoid capital gainsThe profit you make when you sell an asset for more than you paid for it. Short-term gains (assets held less than a year) are taxed at your ordinary income rate; long-term gains (held more than a year) qualify for preferential rates of 0%, 15%, or 20% — a meaningful difference that shapes many investment decisions. and still get the charitable deduction
4. Apply tax-loss harvesting and asset locationThe strategy of placing different types of investments in the most tax-efficient accounts — for example, putting bonds in a tax-deferred IRA and growth stocks in a taxable brokerage account. Done well, asset location can meaningfully improve your after-tax returns without changing your overall risk profile.: placing tax-inefficient investments in tax-deferred accounts and keeping tax-efficient ones in taxable accounts improves after-tax returns without changing risk
5. Time income and deductions: for variable earners or business owners, when you recognize income or book deductions can shift your bracket year to year
Tax planning and financial planning need to run together. Optimizing one without the other leaves money on the table.
How do high earners build wealth without lifestyle creep?
High earners avoid lifestyle creep by treating every income increase as a savings opportunity before it becomes a spending habit. The trap isn't earning more, it's allowing expenses to rise automatically with income.
Five approaches that work:
1. Automate saving before you spend. Direct contributions to investment and retirement accounts on payday so the money moves before it reaches your checking account.
2. Apply a raise rule. Each time income increases, commit a fixed percentage, say 50%, to savings before expanding your lifestyle. You still enjoy the raise. You just don't spend all of it.
3. Track net worth, not lifestyle. Measuring what you actually own minus what you owe keeps the focus on wealth accumulation rather than visible consumption.
4. Set an intentional spending budget. Identify the categories that genuinely matter to you and spend freely there. Cut back on the ones that don't. That's different from cutting everything.
5. Let your standard of living lag your income. After a promotion or bonus, give yourself time before locking in new recurring expenses like a car payment or a bigger mortgage.
Jeff Judge often notes that the clients who build real wealth fastest aren't the highest earners, they're the ones who kept their savings rate climbing even when they could afford not to.
Why do I make a lot of money but still feel behind or like I’m not making progress?
High earners often feel financially behind because income growth and spending growth tend to rise together, leaving the savings rate flat even as the paycheck grows. It's not a math problem. It's a strategy problem.
The most common reasons the feeling persists:
1. Busy without a plan. Financial decisions pile up and get made reactively rather than intentionally. The pile never shrinks.
2. Lifestyle kept pace with income. If spending scaled with every raise, net worth didn't grow even if the number on the paystub did.
3. Measuring by the wrong benchmark. Comparing income to peers or focusing on what you earn rather than what you own creates a distorted picture of actual progress.
4. The strategy hasn't scaled with income. What worked at $80,000 doesn't work at $300,000 or more. Higher income brings more tax complexity, more benefit decisions, and more leverage if you're strategic.
5. No outside accountability. Without someone reviewing the full picture, blind spots compound quietly.
The feeling is real and common. The fix is a plan that actually matches your income level.
*Advisors are only obligated to apply the fiduciary standard in advisory relationships. They are not legally obligated to apply the fiduciary standard when working in Brokerage only relationships
**Mark Rossbach is the only advisor who has attained the RICP and CPA Designations and Jeff Judge is the only advisor who has attained the CFP, ChFC and CLU Designations
Ready to stop second-guessing and start feeling in control?
Book a short “Fit Call” to see if we’re the right partner for your financial life. No pressure, no jargon, just a conversation focused on your goals and whether our approach makes sense for your needs.