
How Do Maryland Business Owners Plan for Estate and Inheritance Tax?
Last reviewed: July 2026
Maryland business owners plan for estate and inheritance tax by combining a business succession plan with state-specific tax strategies, because Maryland is one of the few states that levies both an estate tax and a separate inheritance tax. The estate tax kicks in above a $5 million exemption, and the inheritance tax can take 10% of what passes to nieces, nephews, friends, or business partners. For a business owner in Harford County, the value locked inside the company is often the single largest asset, and without planning it can force heirs to sell the business just to cover the tax bill.
Key Takeaways
- Maryland imposes both a $5 million estate tax exemption and a separate inheritance tax on certain heirs.
- The Maryland inheritance tax rate is 10% on transfers to non-exempt beneficiaries like nieces, nephews, and business partners.
- The federal estate tax exemption rose to $15 million per person in 2026 under the One Big Beautiful Bill Act.
- Business value drives most Maryland owner estates over the exemption, making succession and tax planning inseparable.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate estate and succession planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched too many owners assume the federal exemption is the only number that matters, only to learn that Maryland's separate estate and inheritance taxes quietly reshape the entire plan.
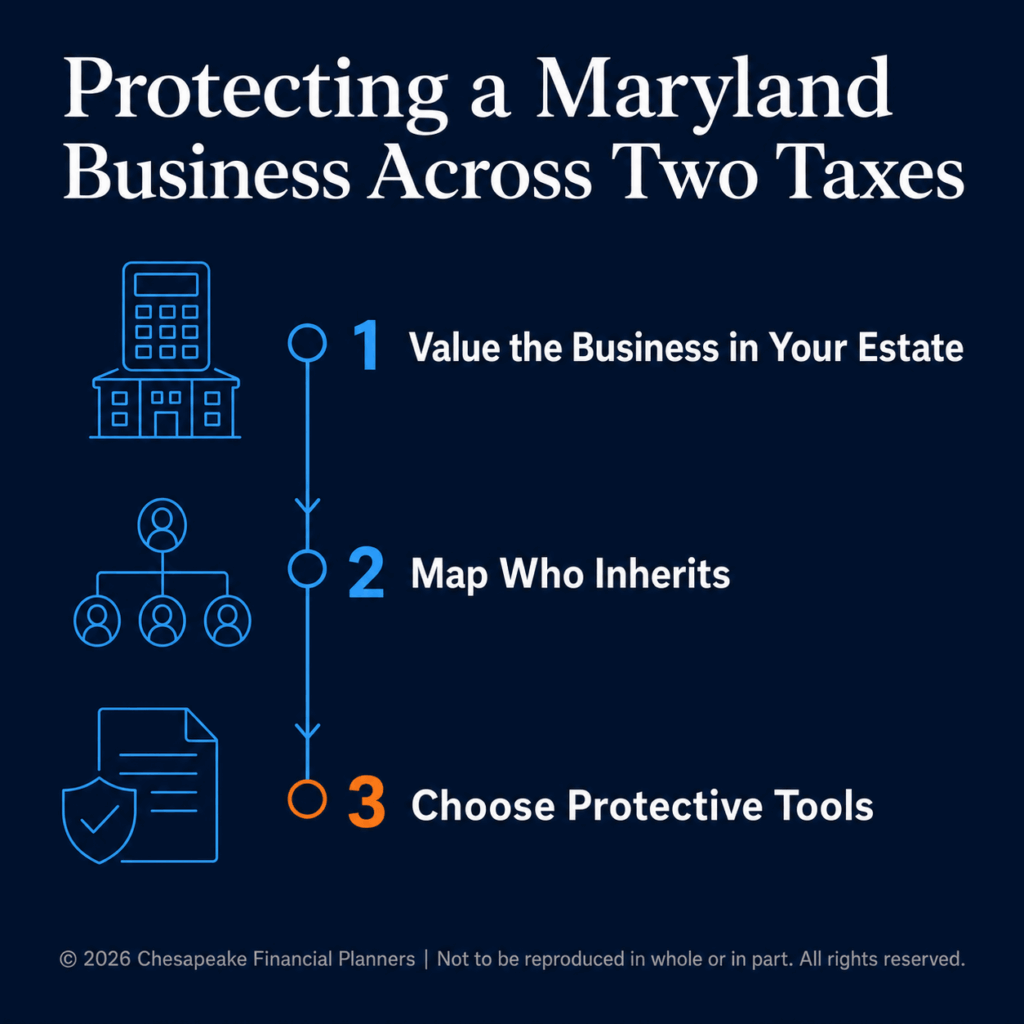
Maryland business owner estate planning is more complicated than planning in most states, and the reason comes down to two separate taxes that hit the same dollar from different angles. The good news: nearly every problem here is solvable with enough lead time. Below is the process Jeff uses with owners across Harford County and Bel Air, broken into clear steps.
Step 1: Calculate Your True Estate Value, Including the Business
Start by adding up everything you own, then add the fair market value of your business. This is where most owners underestimate. A company throwing off $400,000 in profit can carry a valuation of $2 million or more once a buyer applies a market multiple, and that number lands in your taxable estate whether you ever planned to sell or not.
Maryland's estate tax exemption sits at $5 million per person, and unlike the federal exemption, it is not indexed for inflation. So an owner with a $2.5 million home and investment base plus a $3 million business is already over the Maryland line, even though they are nowhere near the federal threshold. Jeff often tells clients that the business valuation is the variable that decides everything, and most people have never had a real one done.
Get a defensible valuation from a qualified appraiser. The estate plan you build sits on top of that number, so it has to be right.
Step 2: Map Out Who Inherits and What Maryland Inheritance Tax They Owe
Maryland's inheritance tax is separate from the estate tax and works differently. It is charged based on who receives the assets, not how large the estate is. Spouses, children, parents, grandchildren, and siblings are exempt. But transfers to nieces, nephews, cousins, friends, or unrelated business partners are taxed at a flat 10%.
This matters enormously for business succession in Harford County. If you plan to leave the company to a key employee, a longtime business partner, or a niece who has worked in the firm for fifteen years, that transfer triggers the 10% inheritance tax on the full value passing to them. On a $2 million business stake, that is a $200,000 bill, often due before the business generates the cash to pay it.
Map every intended beneficiary now and label which ones are exempt and which ones are not. The answer changes how you structure the transfer.
Step 3: Choose Succession and Tax Tools That Fit Maryland Law
Once you know your estate value and your beneficiary mix, you select the tools. For Maryland business owners, the workhorses are usually a buy-sell agreement funded with life insurance, an irrevocable life insurance trust to keep proceeds out of the taxable estate, gifting strategies that use the $19,000 annual exclusion per recipient, and in some cases a grantor retained annuity trust to move business appreciation out of the estate.
A buy-sell agreement funded with life insurance solves the cash crunch directly. When the owner dies, the insurance pays out, the surviving partner or heir uses it to buy the shares, and the family gets liquidity instead of a forced sale. According to LIMRA, life insurance ownership remains a core funding tool for closely held business transfers, and for a Maryland owner facing both estate and inheritance tax, that liquidity often determines whether the business survives the transition.
This is the step where the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process of Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, keeps owners from grabbing a single tool and assuming it solves the whole problem. It rarely does.
Step 4: Build a Liquidity Plan So Heirs Never Have to Sell in Maryland
The final step ties the plan together: make sure there is enough cash to pay both the Maryland estate tax and the inheritance tax without touching the business. This is the failure point Jeff sees most often with Harford County owners. The plan looks elegant on paper, but no one funded the tax bill, so the heirs end up selling the company at a discount under deadline pressure.
Liquidity usually comes from life insurance held outside the estate, a sinking fund built over years, or a structured payout arrangement. The federal estate tax filing deadline is nine months after death, and Maryland follows a similar timeline, so the money has to be ready fast. For Maryland business owners, layering an irrevocable life insurance trust over the succession plan is often what turns a tax problem into a non-event.
Review the whole plan every two to three years and after any major change in business value, family situation, or tax law. The $15 million federal exemption that took effect in 2026 shifted the planning math for many owners, and Maryland's separate $5 million number did not move with it.
Estate and Inheritance Tax Planning for Owners in Harford County
Chesapeake Financial Planners works from our office in Forest Hill, just minutes from Bel Air, and a large share of the business owners we serve are based right here in Harford County and across the Baltimore metro. We see the same pattern repeatedly: an owner has spent thirty years building a company, has a will, and assumes that is enough. It almost never is when Maryland's two-tax structure is in play. Local ownership means we know the appraisers, the estate attorneys, and the succession dynamics specific to family businesses in this region.
If you own a business in Maryland and have not run the numbers on both the estate tax and the inheritance tax, that gap is worth closing before any transition is forced on you.
Frequently Asked Questions
Does Maryland have both an estate tax and an inheritance tax?
Yes, Maryland is one of only a handful of states that levies both. The estate tax applies to estates above the $5 million exemption and is paid by the estate itself. The inheritance tax is separate, charged at 10% based on who receives the assets, and applies even to smaller estates depending on the beneficiary.
How much is the Maryland inheritance tax for business owners in Harford County?
The Maryland inheritance tax is a flat 10% on transfers to non-exempt beneficiaries, including nieces, nephews, cousins, friends, and unrelated business partners. Spouses, children, parents, and siblings are exempt. For a Harford County owner leaving a business stake to a key employee or partner, that 10% can mean a six-figure bill due shortly after death.
What is the Maryland estate tax exemption in 2026?
The Maryland estate tax exemption is $5 million per person in 2026, and it is not indexed for inflation, so it does not rise each year like the federal exemption. Estates valued above that amount owe Maryland estate tax. Because business value is often included, many Maryland owners cross this threshold without realizing it.
How do Maryland business owners avoid forcing heirs to sell the company?
Maryland business owners avoid a forced sale by building a liquidity plan, usually through life insurance held outside the taxable estate, a buy-sell agreement, or a sinking fund. The goal is having cash ready to pay both the estate and inheritance tax within the nine-month filing window so the business itself never has to be sold under pressure.
When should a Maryland business owner start estate tax planning?
A Maryland business owner should start estate planning years before any intended transition, because the most effective tools, like gifting, irrevocable trusts, and funded buy-sell agreements, need time to work. Starting early in Harford County also allows a proper business valuation and lets owners adjust as the company grows past the $5 million estate exemption.
Take the Next Step
If you found this helpful, our guide to business succession and estate tax in Maryland walks through the funding strategies in greater depth. Jeff Judge and the Chesapeake Financial Planners team serve business owners across Harford County, Bel Air, and the Baltimore metro from our Forest Hill office. Schedule a free fit call at chesapeakefp.com to put real numbers around your estate and inheritance tax exposure.
How Do I Create a Business Succession Plan?
What is an ILIT, and how does it keep life insurance out of my estate?
Want to go deeper? Our Tax Strategy Readiness Quiz walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


