
Do Couples in Harford County, Maryland Need Both a Will and a Trust for Estate Planning?
Last reviewed: July 2026
Yes, most married couples in Harford County, Maryland benefit from having both a will and a trust, because each document does a different job. A will directs who inherits your assets and names guardians for minor children, but it passes through probate in the Orphans' Court. A trust lets you transfer assets privately, avoid probate delays, and control how and when your heirs receive money. For couples in Forest Hill, Bel Air, and across Harford County, the combination of a will and a revocable living trust usually delivers the cleanest result. The right Maryland estate planning approach for couples balancing a will and a trust depends on the size of the estate, whether you own a business, and how much privacy you want.
Key Takeaways
- A will alone sends your estate through Maryland probate, while a trust can bypass it entirely for faster, private transfers.
- Maryland imposes its own estate tax in 2026 on estates above $5 million, separate from the federal exemption.
- Couples with minor children, a business, or out-of-state property gain the most from pairing a will with a revocable living trust.
- Chesapeake Financial Planners coordinates with Harford County estate attorneys so your plan, taxes, and investments stay aligned.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate estate planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched more than one Harford County family discover, too late, that a single will left their surviving spouse stuck in probate for the better part of a year.
Estate planning is one of those things people in Bel Air and Forest Hill mean to handle and then put off for a decade. The cost of waiting isn't theoretical. When one spouse dies without the right documents in place, the survivor often inherits a mess: frozen accounts, court filings, and a tax bill nobody planned for. Let me walk through how a will and a trust actually work together for Maryland couples, and why the answer is rarely one or the other.
What Is the Difference Between a Will and a Trust in Maryland?
A will is a legal document that takes effect only after you die. It names who gets your property, who raises your minor children, and who serves as personal representative to settle the estate. In Maryland, a will must pass through probate, which is handled by the Register of Wills and the Orphans' Court in each county, including Harford County.
A trust, by contrast, is a legal entity you create while you're alive. You move assets into it, and a trustee manages them according to your instructions. A revocable living trust lets you stay in control of everything during your lifetime, then transfers assets to your heirs without probate when you die.
The practical difference comes down to three things: privacy, speed, and control. Probate in Maryland is a public process, so anyone can look up what your estate held and who inherited it. A trust keeps that private. Probate also takes time, often six months to over a year, while a trust can distribute assets in weeks. And a trust gives you control over timing, so you can stagger an inheritance for a young adult instead of handing them a lump sum at 18.
Jeff Judge often tells couples in Forest Hill that the will-versus-trust framing is the wrong question. The real question is which combination protects the surviving spouse and keeps the family out of court. For most couples, that means both documents working together.
Why Do Couples in Harford County Need Both Documents?
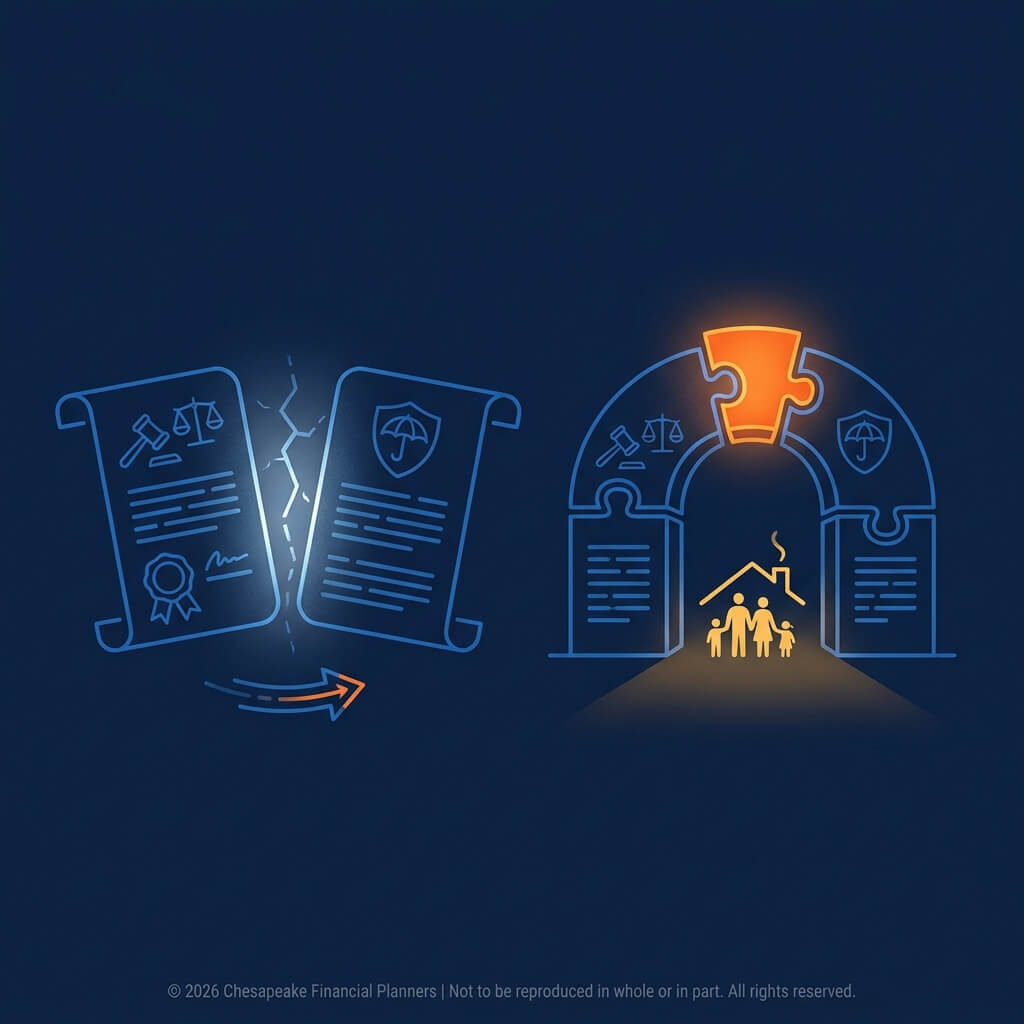
Couples in Harford County need both a will and a trust because the two documents cover different gaps. A trust handles the assets you fund into it and avoids probate. A will catches everything else, including assets you forgot to retitle, and it names guardians for minor children, which a trust cannot do.
This is the part people miss. A trust only controls what you actually put inside it. If you set up a revocable living trust but never retitle your house, your brokerage account, or that rental property in Bel Air into the trust's name, those assets still go through probate. The "pour-over will" exists precisely for this reason. It catches stray assets and pours them into your trust after death, so nothing falls through the cracks.
For couples with children under 18, the will is non-negotiable. Maryland law requires a will to name a legal guardian. No trust, no beneficiary designation, and no joint account can do that job. If you have young kids in Harford County and no will, the Orphans' Court decides who raises them. That alone is reason enough to have both.
There's also the matter of out-of-state property. Plenty of Harford County couples own a beach place in Delaware or Ocean City, or land elsewhere. Without a trust, that out-of-state property triggers a second probate proceeding in that state, a process called ancillary probate. Funding the property into a trust avoids it entirely.
According to the American Bar Association, a coordinated estate plan that pairs a will with a trust is the standard recommendation for families who want to avoid probate while still naming guardians and catching overlooked assets. That coordination is exactly where a financial planner and an estate attorney earn their keep.
How Does Maryland Estate Tax Affect Your Planning in 2026?
Maryland is one of the few states that still imposes its own estate tax, and it kicks in at a much lower threshold than the federal exemption. For 2026, the Maryland estate tax exemption is $5 million per person, according to the Comptroller of Maryland. Estates above that amount face a Maryland estate tax with a top rate of 16%.
That $5 million figure matters more than people in Bel Air and Forest Hill expect. Between a paid-off home, retirement accounts, life insurance, and a business, a successful Harford County couple can cross that line faster than they realize. Life insurance death benefits, in particular, count toward your taxable estate in Maryland unless they're owned correctly.
Maryland also has a separate inheritance tax, though spouses, children, parents, and grandchildren are exempt from it. The inheritance tax mainly affects more distant heirs like nieces, nephews, and friends, who pay a 10% rate on what they receive, per the Comptroller of Maryland.
On the federal side, the estate and gift tax exemption rose to $13.99 million per person in 2025, and under the law passed in 2025, that higher exemption was made permanent and set at $15 million per person beginning in 2026, according to the IRS. Most Harford County couples sit well below the federal line. The Maryland line is the one that catches people.
This is where a properly structured trust earns its place. A married couple can use credit shelter provisions inside their trusts to preserve both spouses' $5 million Maryland exemptions, effectively shielding up to $10 million from Maryland estate tax. Jeff Judge has used the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process of Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, to walk Harford County couples through exactly this kind of tax-aware trust design before sending them to a local attorney to draft the documents.
How Does Chesapeake Financial Planners Help With Estate Planning in Forest Hill?
Chesapeake Financial Planners doesn't draft your will or trust, because those are legal documents that require a licensed Maryland attorney. What we do is the part that usually gets skipped: making sure your financial plan, your tax picture, and your estate documents all point in the same direction.
Our office sits in Forest Hill, minutes from Bel Air, and most of our clients live right here in Harford County and the surrounding Baltimore metro area. That local footprint matters for estate planning, because Maryland's estate tax, probate rules, and inheritance tax are state-specific. We know the local estate attorneys, we understand Harford County's Register of Wills process, and we coordinate directly with the attorney you choose so your beneficiary designations actually match your trust.
That last point is where plans fall apart. People spend money on a beautiful trust, then leave their 401(k) and IRA beneficiary forms pointing at an ex-spouse or a now-adult child. Beneficiary designations override your will and your trust. We audit those for every couple we work with, because a misaligned beneficiary form can undo years of careful planning in a single afternoon.
If you've been meaning to get your estate documents in order, the practical first step is understanding what you actually own and how each asset would transfer today. That's the conversation we have with couples across Harford County every week.
Frequently Asked Questions
Do I need a will if I already have a revocable living trust in Maryland?
Yes, you still need a will even with a revocable living trust. The will names guardians for any minor children, which a trust cannot do, and it acts as a pour-over will that catches any assets you never retitled into your trust. Without it, overlooked assets go through Harford County probate.
How much does it cost to avoid probate in Harford County, Maryland?
Avoiding probate in Harford County typically means funding a revocable living trust, and attorney fees for a married couple's trust-based plan often run a few thousand dollars. That one-time cost frequently saves far more in probate expenses, court delays, and lost privacy. The exact figure depends on your assets and the attorney you choose.
Does Maryland have an estate tax in 2026?
Yes, Maryland imposes a state estate tax in 2026 on estates above $5 million per person, with a top rate of 16%, according to the Comptroller of Maryland. Maryland also levies a separate inheritance tax, though spouses, children, and grandchildren are exempt. This is separate from the much higher federal exemption.
What happens if a Harford County couple dies without a will or trust?
If a Harford County couple dies without a will or trust, Maryland's intestacy laws decide who inherits, and the estate goes through full probate in the Orphans' Court. For couples with minor children, the court also decides who becomes their guardian. The process is public, slower, and rarely matches what the couple would have wanted.
Should both spouses have separate trusts or one joint trust in Maryland?
Maryland couples can use either separate revocable trusts or a single joint trust, and the right choice depends on the estate's size and the Maryland estate tax exposure. Separate trusts often preserve both spouses' $5 million Maryland exemptions through credit shelter planning. A local estate attorney and your financial planner should make this call together based on your numbers.
Can Chesapeake Financial Planners draft my will and trust?
No, Chesapeake Financial Planners does not draft legal documents, because wills and trusts require a licensed Maryland attorney. We coordinate the financial side: aligning your beneficiary designations, modeling your Maryland estate tax exposure, and working directly with the Harford County or Bel Air estate attorney you select so every piece of your plan fits together.
If your estate documents are out of date or you've never had them reviewed, our free guide to organizing your estate plan walks Harford County couples through what to gather before meeting an attorney. Download it at chesapeakefp.com and start the conversation on your terms.
Want to go deeper? Our Estate Document Locator walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


