
Published: | Last reviewed: July 2026 by Jeff Judge, CFP®
Part of our guide: Can a high-income family qualify for financial aid, and what strategies are allowed?
The best FAFSAThe Free Application for Federal Student Aid — the form that determines your child's eligibility for federal grants, loans, and work-study programs. How your assets and income are counted on FAFSA affects the financial aid your family receives, making the financial decisions you make in the years before college more consequential than many parents realize. strategies come down to three moves: shift assessable assets into accounts the formula ignores, time your asset positioning before the income base year, and keep money out of your student's name. Two families with identical incomes can land thousands apart in aid, and the gap almost always traces back to whether they understood the formula. The Student Aid Index, not the family's good intentions, decides the award.
Key Takeaways
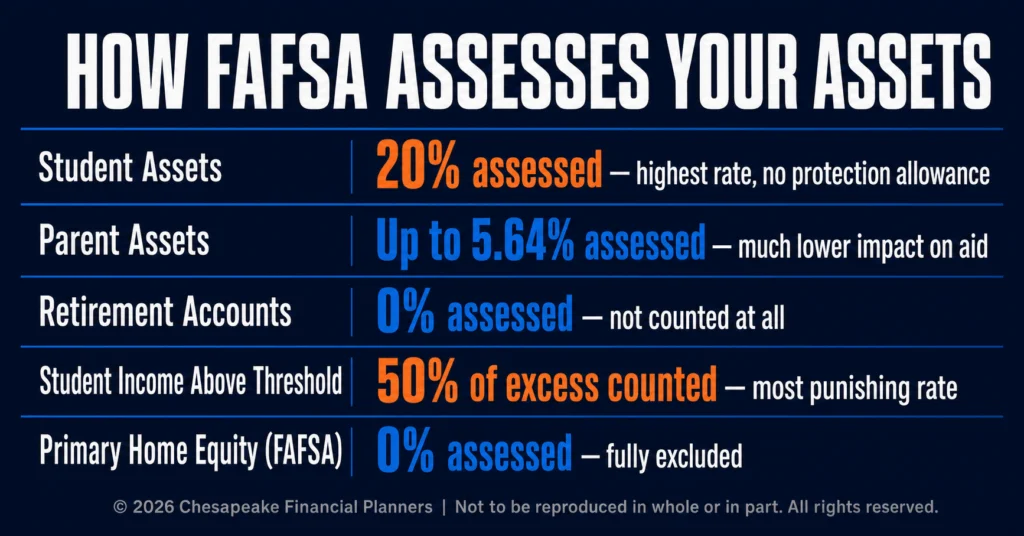
- The FAFSA assesses parent assets at up to 5.64% but student assets at a flat 20%, so account ownership matters.
- Retirement accounts, primary home equity, and life insurance cash value are fully excluded from the FAFSA asset calculation.
- The 2026-27 FAFSA uses 2024 income as its base year, so strategic moves work best two years before college.
- A parent-owned 529 plan is assessed at the parent rate, not the student rate, often saving over $1,400 per year in aid.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate college funding decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view: most families sweat the wrong number, agonizing over a few thousand in 529 returns while a single mistimed asset move quietly costs them five figures in aid.
What Is the Student Aid Index and Why Does It Matter?
The Student Aid Index (SAI) is the number the FAFSA produces to estimate what your family can contribute toward college, and it directly drives how much need-based aid your student qualifies for. It replaced the old Expected Family Contribution under the FAFSA Simplification Act. A lower SAI means more eligibility for grants, subsidized loans, and work-study.
The formula weighs income and assets differently, and that difference is the heart of every smart FAFSA strategy. According to Federal Student Aid, parent income above the protection allowance is assessed at a rate climbing up to roughly 47%, while parent assets above their allowance are assessed at a maximum of 5.64%. Student assets get hit hardest at a flat 20% with no protection allowance at all.
Jeff Judge often tells parents that the SAI is not a punishment for saving well. It is a math problem, and math problems have solutions if you start early enough.
Which Assets Does the FAFSA Ignore?
Several major asset categories are completely excluded from the FAFSA, and knowing them is the foundation of strategic college financial planning. The FAFSA does not count retirement accounts such as 401(k)s, IRAs, 403(b)s, and pensions. It also excludes the cash value of life insurance, annuities, and the equity in your primary residence.
For families who run a business, the FAFSA Simplification Act changed how small business and family farm assets are treated, and these now require careful reporting rather than automatic exclusion. This is where college funding for business owners gets nuanced, and where a planning conversation pays for itself.
The strategic lever here is simple to state and harder to execute well: moving assessable money into excluded categories before you file improves your expected family contribution math without making you poorer. A dollar in a Roth IRAA retirement account funded with after-tax dollars where your money grows completely tax-free and qualified withdrawals in retirement are also tax-free — including all the gains. There are no Required Minimum Distributions during your lifetime, making the Roth one of the most flexible and powerful long-term savings tools available. does the same retirement work as a dollar in a taxable brokerage account, but only one of them counts against aid.
In 2026, the IRS caps 401(k) employee contributions at $24,500, with an additional $8,000 catch-up for those age 50 and older ($11,250 at ages 60 through 63). Moving cash from a taxable account into retirement accounts before college is one way families reduce reportable assets, within contribution limits.
How Should I Time Asset Moves Before Filing?
You should make asset and income moves before your FAFSA base year, which for the 2026-27 cycle is the 2024 calendar year. The FAFSA uses prior-prior-year income, so by the time you file, the income figures are already locked. That is why the planning window opens in your student's freshman and sophomore years of high school, not senior year.
A clean way to think about it:
- Freshman or sophomore year: full runway. Reposition student assets, maximize retirement contributions, and plan any large capital gainsThe profit you make when you sell an asset for more than you paid for it. Short-term gains (assets held less than a year) are taxed at your ordinary income rate; long-term gains (held more than a year) qualify for preferential rates of 0%, 15%, or 20% — a meaningful difference that shapes many investment decisions. around the base year.
- Junior year: the base year is happening now. Be deliberate about discretionary income and avoid unnecessary realized gains.
- Senior year: most income strategies have closed, though a few asset-positioning moves still help.
This timing discipline is exactly what the R.U.D.D.E.R. Method™ is built for. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. College funding decisions touch taxes, cash flow, and retirement at once, so a structured process keeps families from optimizing one number while wrecking another.
For a deeper treatment of how 529 accounts fit this timing, see How does a 529 plan work and what are the rules for contributions and withdrawals?.
Income timing matters as much as asset timing. Because parent income is a major factor in the Student Aid Index, managing it during base years can have an outsized impact. If you are self-employed or can time compensation, deferring a bonus or delaying business income out of a base year may help; accelerating income into the year before your first base year keeps it off every FAFSA. Watch capital gains too: selling appreciated stock or property generates income that the FAFSA sees, so consider doing planned sales outside a base year. Be deliberate about Roth conversions. A conversion creates taxable income in the conversion year, which can raise your Student Aid Index if it lands inside a base year, so if conversions fit your long-term tax plan, consider completing them before the first base year or after the last one. The FSA Handbook describes how reported income feeds the formula.
What Are the Best 529 Plan Strategies for Aid?
The strongest 529A tax-advantaged savings account designed for education expenses, where contributions grow tax-free and withdrawals are tax-free when used for qualified education costs. Recent rule changes also allow unused 529 funds to be rolled into a Roth IRA, adding flexibility you may not have had before. plan strategies center on ownership and timing, because who owns the account changes how the FAFSA treats it. A 529 plan owned by a parent is reported as a parent asset and assessed at the maximum 5.64% rate. The same money sitting in a custodial UTMA or a student-owned account gets assessed at 20%.
The math is stark. Take $10,000 of college savings. Held in a student's name, the FAFSA can count roughly $2,000 of it against aid. Held in a parent-owned 529, it counts for about $564. That is a difference of $1,436 in a single year, and it repeats every year the student is enrolled.
Grandparent-owned 529 plans deserve their own note. Under FAFSA Simplification, distributions from a grandparent 529 no longer count as student income on the FAFSA, which removed a longstanding penalty. Families with generous grandparents should read How does the grandparent 529 work after FAFSA simplification? before assuming the old rules still apply.
If your income is high enough that need-based aid feels out of reach entirely, the calculus shifts toward merit aid and tax efficiency instead. That scenario gets its own treatment in What are my college funding options when my income disqualifies us from financial aid?.
Student income matters too: the formula assesses it at 50% after allowances, according to the FSA Handbook.
Frequently Asked Questions
Does the CSS Profile use the same rules as the FAFSA?
No, the CSS Profile is a separate aid application used by roughly 200 private colleges, and it assesses assets the FAFSA ignores. The biggest difference is home equity: most CSS Profile schools count the equity in your primary residence, while the FAFSA never does. CSS schools may also assess small business value and ask deeper questions about non-custodial parents.
How much do student assets really hurt financial aid?
Student assets are assessed at a flat 20% with no protection allowance, making them the most damaging place to hold college money. A student savings account of $10,000 reduces aid eligibility by roughly $2,000 every year it appears on the FAFSA. Moving that money into a parent-owned 529 before filing cuts the assessment to about 5.64%, which is why account ownership is the first thing Jeff reviews with families.
Will maxing out my 401(k) improve my financial aid?
Yes, contributing more to your 401(k) during the base year can lower your assessed income while building an asset the FAFSA does not count. Retirement plan contributions reduce the income figure that drives most of the SAI calculation. The exact benefit depends on your income tier, but families in the steeper assessment range often see a meaningful reduction in their Student Aid Index from a single base-year contribution decision.
When is it too late to use FAFSA strategies?
Most income strategies close once your base year ends, which is the calendar year two years before your student enrolls. For a student starting college in fall 2026, the base year was 2024, so income moves needed to happen by then. Asset positioning, including shifting student money into parent-owned accounts, can still help right up until you file, since the FAFSA takes an asset snapshot on the filing date.
Do I have to report my retirement accounts on the FAFSA?
No, you do not report the balances of qualified retirement accounts such as 401(k)s, IRAs, and pensions as assets on the FAFSA. The form excludes these entirely from the asset calculation. Be aware, though, that any distributions you take from those accounts during the base year do count as income, which can raise your Student Aid Index even when the account balance itself is protected.
Should I still file the FAFSA if I think I earn too much for aid?
Yes. You should file the FAFSA every year regardless of income. Federal student loan eligibility requires it, and some colleges tie merit scholarships to a completed FAFSA. Filing costs nothing, preserves your options, and positions you to request a professional judgment review if your financial situation changes.
Can a Roth conversion hurt my college financial aid?
It can. A Roth conversion creates taxable income in the conversion year, which can raise your Student Aid Index if it falls inside a FAFSA base year. If conversions fit your long-term plan, consider completing them before your first base year or after your last one.
Want a clear, step-by-step worksheet for positioning your accounts before you file? Our free college planning guide walks through the FAFSA timeline and the asset moves that matter most. Download it at chesapeakefp.com and start before your student's base year, not after.
Want to go deeper? Our College Funding Playbook walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Prior to investing in a 529 Plan, investors should consider whether the investor's or designated beneficiary's home state offers any state tax or other state benefits such as financial aid, scholarship funds, and protection from creditors that are only available for investments in such state's qualified tuition program. Withdrawals used for qualified expenses are federally tax free. Tax treatment at the state level may vary. Please consult with your tax advisor before investing.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


