
How to Use an HSA for Retirement: A Stealth IRA Strategy
Last reviewed: July 2026
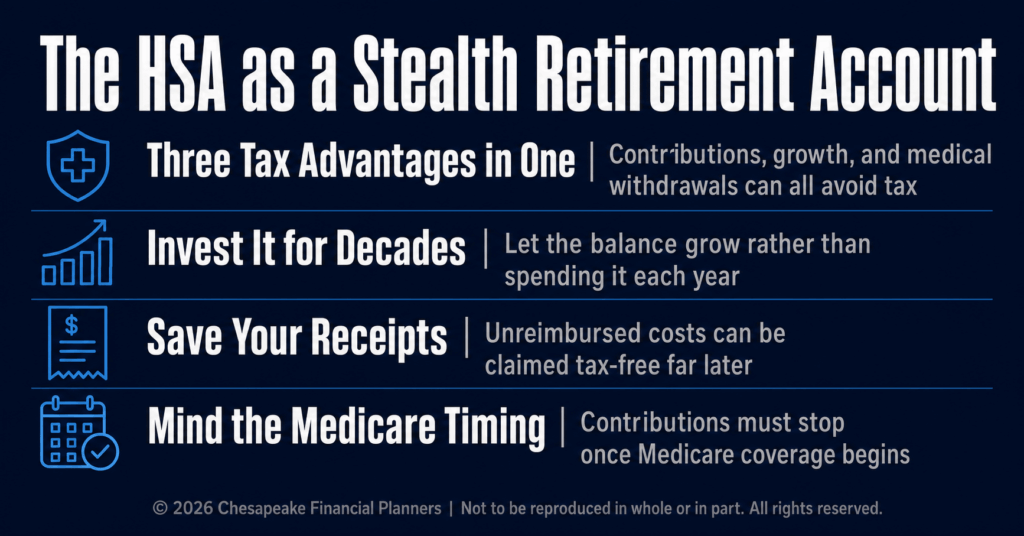
Using an HSA for retirement works because the Health Savings Account combines three tax advantages no other account can match: contributions reduce your taxable income, growth is tax-free, and qualified withdrawals are tax-free for life. The 2026 limits, set by IRS Revenue Procedure 2025-19, are $4,400 for self-only high-deductible coverage and $8,750 for family coverage, with an additional $1,000 catch-up for anyone 55 or older. If you max your account every year, invest the balance instead of holding cash, and time withdrawals around Medicare, the HSA quietly becomes one of the most efficient retirement assets you own.
On This Page
- Key Takeaways
- Step 1: Confirm You're HSA-Eligible Before You Open the Account
- Step 2: Max Your Contributions and Use the Age 55+ Catch-Up
- Step 3: Invest the Balance, Don't Just Hold Cash
- Step 4: Pay Medical Bills Out of Pocket and Save the Receipts
- Step 5: Use Your HSA for Retirement Spending After Age 65
- Related Topics Worth Reading
- Frequently Asked Questions
- Disclosures
Key Takeaways
- The 2026 HSA contribution limits are $4,400 self-only and $8,750 family, with a $1,000 catch-up at age 55 and older.
- HSAs are the only account that gives you a deduction going in, tax-free growth, and tax-free qualified medical withdrawals coming out.
- After age 65, HSA withdrawals for any purpose face only ordinary income tax with no 20% penalty.
- You cannot contribute to an HSA once enrolled in Medicare, so the months before age 65 are a critical funding window.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area plan around HSAs, high-deductible health plans, and Medicare timing since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often tells pre-retiree clients that the HSA is the most misused account on their statement, because most people spend it down for current bills when they could be using it as a stealth IRA that compounds untaxed for decades.
Step 1: Confirm You're HSA-Eligible Before You Open the Account
You can contribute to an HSA only if you are covered by a qualifying high-deductible health plan (HDHP), have no other disqualifying health coverage, are not enrolled in any part of Medicare, and cannot be claimed as a dependent. For 2026, the IRS defines an HDHP as a plan with a minimum annual deductible of $1,700 self-only or $3,400 family, and out-of-pocket maximums capped at $8,500 self-only or $17,000 family. If your plan's deductible falls below those thresholds, the plan is not HDHP-qualified and you cannot fund an HSA against it.
The "no other coverage" rule is where most disqualifications happen. A general-purpose Flexible Spending Account through your or your spouse's employer disqualifies you. So does TRICARE, Medicare enrollment in any part, or VA medical benefits received in the prior three months. Limited-purpose FSAs that cover only dental and vision are fine. Coverage under a spouse's non-HDHP plan also disqualifies you, which surprises a lot of two-income households.
The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. The first step of any HSA strategy is Review and Recognize: confirm eligibility, then build from there. Skip this and the rest of the plan unravels at audit.
Step 2: Max Your Contributions and Use the Age 55+ Catch-Up
The single biggest mistake we see is treating the HSA as a checking account for current medical bills. Treat it like a Roth IRA you happen to be allowed to fund with pretax dollars. For 2026, you can contribute up to $4,400 with self-only HDHP coverage and $8,750 with family coverage. At age 55 or older, add a $1,000 catch-up, which is statutory under IRC §223(b)(3) and not indexed for inflation. If both spouses are 55 or older, each can contribute their own $1,000 catch-up, but they must do so in separate accounts because HSAs are individual accounts.
A common HSA retirement strategy is to fund the HSA before fully maxing a traditional 401(k), once you have captured your employer match. Every dollar in the HSA is triple-tax-advantaged, while a 401(k) dollar is only tax-deferred and will be taxed on withdrawal. For a household in a 24% marginal bracket funding $8,750 in family contributions, the immediate federal tax benefit alone is roughly $2,100, before any state tax savings. Maryland residents typically save an additional 4.75% to 5.75% depending on bracket.
Pro-rate your contribution if your eligibility changes mid-year. The last-month rule lets you contribute the full annual amount if you are HSA-eligible on December 1, but you must remain eligible through all of the following year (the "testing period") or face taxes plus a 10% penalty on the excess. Jeff has watched clients trigger this penalty after taking a new job mid-year that came with non-HDHP coverage, which is one of the avoidable mistakes a quick check at open enrollment would have caught.
Step 3: Invest the Balance, Don't Just Hold Cash
The default custodian setting at most HSA providers parks contributions in a low-yield cash account. That is fine if you are using the HSA to pay current medical bills, but it is the wrong setting if the HSA is your stealth retirement account. Most providers, including Fidelity, HSA Bank, Lively, and HealthEquity, let you sweep balances above a custodian-set cash threshold (often $1,000 to $2,000) into mutual funds or ETFs. Set up the sweep once and let it run automatically with every paycheck.
The HSA investing menu matters less than the time horizon. For someone funding an HSA at 45 with no plan to touch it until 65 or later, a low-cost broad-market index fund inside the HSA can capture two decades of compounding inside a tax-free wrapper. Compare that to a non-deductible IRA contribution at the same age: the IRA pays tax on growth at withdrawal, the HSA does not, as long as the withdrawal is for qualified medical expenses, which most people end up incurring in retirement anyway.
Watch the fees. Some HSA custodians charge a monthly account fee, a monthly investment fee, or both. If you are at a high-fee custodian, you can transfer the investable portion to a low-cost custodian via a trustee-to-trustee transfer once a year without triggering taxes. Keeping the active payroll account where your employer directs contributions, while sweeping investable dollars elsewhere, is a common workaround when the employer plan has weak investment options.
A useful planning lever: if you are 50 and have a $20,000 HSA balance growing at a 7% real return for 15 years, you arrive at age 65 with roughly $55,000 in tax-free reimbursement capacity, assuming you have saved receipts (see Step 4).
How do I get health insurance between early retirement and Medicare?
Step 4: Pay Medical Bills Out of Pocket and Save the Receipts
Federal tax law lets you reimburse yourself from your HSA for any qualified medical expense you have paid out of pocket, in any prior year, as long as the expense was incurred after your HSA was opened. There is no statute of limitations on reimbursement. A medical bill you paid in 2030 can be reimbursed from your HSA in 2050.
That changes the calculus. Instead of using the HSA to pay current medical bills, pay the bills with after-tax cash from your checking account, let the HSA continue to compound tax-free, and save the receipts. Decades later, reimburse yourself tax-free for those receipts, pulling out a large sum of HSA dollars with zero tax owed. IRS Publication 969 is the source on what counts as a qualified medical expense.
Save receipts digitally with a backup, and keep the explanation of benefits from your insurance carrier alongside the receipt. Premiums for dental, vision, prescriptions, deductibles, and copays count, even if you never used your HSA debit card. Mileage to and from medical appointments counts at the IRS standard medical rate, which the IRS publishes annually. Long-term care insurance premiums count up to age-based limits. Medicare premiums for Parts B, D, and Advantage count once you are 65 or older.
Jeff has had clients walk into a meeting with a shoebox of medical receipts going back fifteen years and realize they had enough qualifying expenses to drain their entire $90,000 HSA tax-free in retirement. That is the play. The expenses have already been paid, and the HSA balance is sitting tax-free. The reimbursement is just paperwork.
How do you use the years between retirement and RMDs to reduce lifetime taxes?
Step 5: Use Your HSA for Retirement Spending After Age 65
Two rules govern HSAs after 65, and missing either is costly. First, enrolling in any part of Medicare ends your HSA contribution eligibility. The day Medicare enrollment becomes effective, you can no longer add new dollars. The balance keeps compounding tax-free and remains yours to withdraw, but no new contributions are allowed.
The Medicare enrollment trap hits people who delay Social Security past 65 and file for benefits later. If you start Social Security after 65, the Social Security Administration automatically enrolls you in Medicare Part A with a retroactive effective date of up to six months before you file. Those six months of retroactive Part A coverage retroactively disqualify your HSA contributions during the same period. The fix: if you plan to keep contributing to an HSA past 65, do not start Social Security until you are ready to stop HSA contributions, and stop HSA contributions six months before your Medicare Part A effective date.
The second rule turns the HSA into a stealth IRA. After age 65, HSA withdrawals for non-medical purposes face only ordinary income tax. The 20% penalty that applies to non-qualified withdrawals before 65 disappears. Your HSA after 65 then functions like a traditional IRA for non-medical withdrawals, with one major upside: qualified medical withdrawals remain tax-free for life. You can pay the standard $202.90 monthly Medicare Part B premium directly from the HSA, tax-free. You can pay Medicare Part D and Advantage premiums tax-free, plus long-term care premiums up to age-based limits.
Coordinate this with the rest of your retirement income plan. If you have a Roth conversion strategy running in your sixties, HSA dollars give you a flexible source of tax-free spending that does not increase your modified adjusted gross income, so it does not push you into a higher IRMAA bracket. Most pre-retirees we work with end up using the HSA last, letting it compound for as long as possible while drawing first from taxable accounts and Roth conversions in the lower-tax years before Medicare and RMDs begin.
Related Topics Worth Reading
The HSA is one piece of a broader retirement tax strategy. Pairing it with the right account sequencing, Medicare planning, and Roth conversions is where the real compounding happens.
- Roth conversion rules for 2026 walks through the conversion math and the bracket-by-bracket case for converting before Medicare and RMDs begin.
- IRMAA 2026 Medicare premium thresholds explains how Roth conversions and large IRA withdrawals can push you into higher Medicare premium brackets.
- How do you use the years between retirement and RMDs to reduce lifetime taxes? covers the ages 60-73 window for cutting your lifetime tax bill, where the HSA can play a major role.
- How Do I Maximize My 401(k) Employer Match? explains why you fund the HSA after capturing the full employer 401(k) match, not before.
Frequently Asked Questions
Can I use my HSA after I retire?
Yes, your HSA continues to work after you retire. Once you stop contributing, the existing balance keeps compounding tax-free, and you can withdraw funds for qualified medical expenses tax-free at any age. After age 65, you can also withdraw for non-medical purposes by paying only ordinary income tax with no 20% penalty, which makes the HSA function as a traditional IRA for retirement spending.
What happens to my HSA when I enroll in Medicare?
The day your Medicare enrollment becomes effective in any part (A, B, C, or D), you can no longer contribute new dollars to your HSA. The existing balance is unaffected and continues to grow tax-free, and you can use it to pay for qualified medical expenses, including Medicare Part B, Part D, and Advantage premiums. Stop HSA contributions six months before Medicare Part A coverage to avoid an excess contribution penalty.
How much should I contribute to my HSA each year?
For 2026, you can contribute up to $4,400 with self-only HDHP coverage or $8,750 with family coverage, plus a $1,000 catch-up at age 55 or older. Most pre-retirees benefit from maxing the HSA every year, because the triple-tax advantage typically beats the equivalent dollars in a 401(k) or non-deductible IRA. Pro-rate your contribution if you change coverage mid-year, and confirm eligibility before contributing.
Can I invest my HSA balance like a 401(k)?
Yes, most HSA custodians let you invest balances above a cash threshold (typically $1,000 to $2,000) into mutual funds or ETFs. Once the investment option is enabled, future contributions can sweep automatically into the investment account. For an HSA being used as a long-term retirement account, the investment option is the entire reason the strategy works, because the tax-free compounding only happens if the balance is growing.
What expenses can I reimburse from my HSA tax-free?
Qualified medical expenses include deductibles, copays, prescriptions, dental and vision care, mental health services, long-term care insurance premiums up to age-based limits, and Medicare premiums (B, D, and Advantage) after age 65. You can reimburse yourself in any future year for an expense you paid out of pocket today, as long as the expense was incurred after the HSA was opened.
What is the penalty for non-medical HSA withdrawals?
Before age 65, non-medical HSA withdrawals are taxed as ordinary income plus a 20% penalty. After age 65, the 20% penalty disappears, and non-medical withdrawals are taxed only as ordinary income, which makes the HSA function like a traditional IRA in retirement. Qualified medical withdrawals are always tax-free, regardless of age.
If you found this helpful, our pre-retirement tax-planning guide shows how to combine an HSA for retirement with Roth conversions and pre-RMD bracket management. Download it at chesapeakefp.com, or schedule a no-obligation call with Jeff to walk through your specific HSA setup and Medicare timing for retirement.
Want to go deeper? Our Retirement Income Blueprint Workbook walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 ½ may result in a 10% IRS penalty tax in addition to current income tax.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


