
How Do I Fill Out a W-4 So I Don't Owe or Overpay?
Last reviewed: July 2026
To fill out a W-4 so you neither owe nor overpay, complete Step 1 with your filing status, use Step 2 only if you hold more than one job or your spouse works, claim dependents in Step 3, and use Step 4 to fine-tune for extra income or deductions. The form no longer uses "allowances." It works off your actual filing status and income, which means accuracy matters more than guessing a number.
Key Takeaways
- The current W-4 has five steps, and most single-job filers only need Step 1 and Step 5.
- The IRS Tax Withholding Estimator is the fastest way to match withholding to your real tax bill.
- For 2026, the standard deduction is $32,200 for married couples filing jointly, which affects whether you adjust Step 4(b).
- Two-income households underwithhold most often, so Step 2 exists specifically to fix that.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate tax withholding decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff sees the same pattern every spring: people who got a big refund cheer, then realize they handed the government an interest-free loan all year.
A refund feels like a win. It isn't. A large refund means you overpaid every paycheck, and that money could have been in your account, your emergency fund, or paying down debt. The goal of a well-filled W-4 is a number close to zero at tax time. Here is how to get there, step by step.
What Is a W-4 and Why Did It Change?
A W-4 is the IRS form you give your employer that tells them how much federal income tax to withhold from each paycheck. It is not filed with the IRS. Your employer keeps it and uses it to calculate withholding.
The form was redesigned in 2020 and the old "number of allowances" system is gone. Instead, the W-4 now asks for concrete information: your filing status, other jobs, dependents, and any adjustments. According to the IRS, this change was made to improve accuracy and transparency. The practical effect is that you can no longer fudge an allowance count to dial withholding up or down. You work with real dollar figures instead.
How to Fill Out a W-4 Step by Step
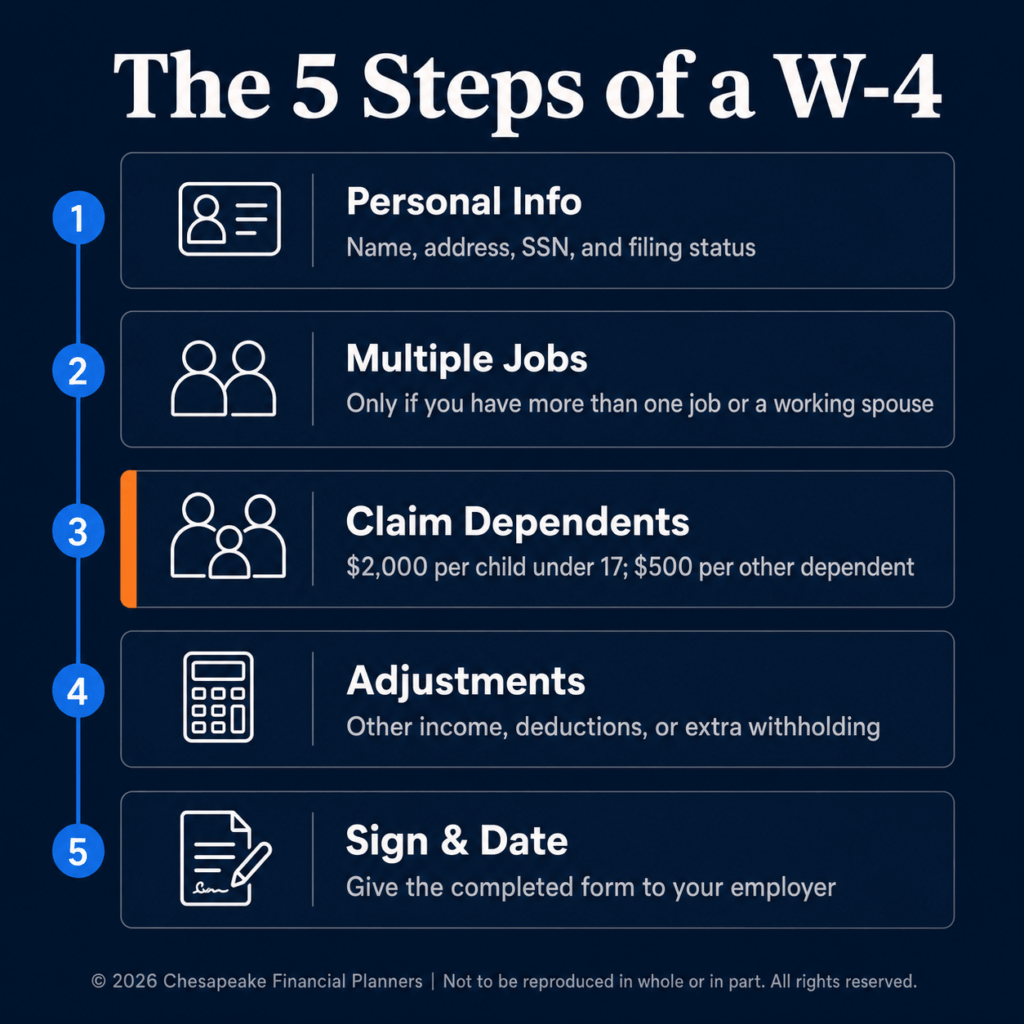
Follow these five steps in order. Most people with one job will finish in under five minutes.
- Step 1 — Enter your personal information. Provide your name, address, Social Security number, and filing status (single, married filing jointly, or head of household). Your filing status sets your standard deduction and tax brackets, so this single choice drives most of the math.
- Step 2 — Account for multiple jobs or a working spouse. Complete this only if you hold more than one job or you are married filing jointly and your spouse also works. You have three options: check the box in 2(c) if both jobs pay roughly the same, use the IRS estimator, or use the Multiple Jobs Worksheet. Skipping this step is the number one cause of underwithholding.
- Step 3 — Claim dependents. If your total income will be under the phase-out threshold, multiply qualifying children under 17 by $2,000 and other dependents by $500. Enter the total. This directly reduces the tax withheld.
- Step 4 — Make other adjustments (optional). Use 4(a) for other income not from jobs, such as interest or dividends. Use 4(b) if you itemize and expect deductions above the standard deduction. Use 4(c) to request an extra flat dollar amount withheld per paycheck.
- Step 5 — Sign and date. The form is not valid until you sign it. Hand it to your employer's payroll or HR contact.
How Do I Adjust Tax Withholding to Avoid Owing?
To adjust your tax withholding so you don't owe, run the IRS Tax Withholding Estimator with a recent pay stub and last year's return, then enter any recommended extra amount in Step 4(c). The estimator does the heavy lifting for you.
The most common reasons people owe at tax time are a working spouse whose income wasn't accounted for in Step 2, side income with no withholding, and a bonus taxed at the flat supplemental rate. The IRS withholds bonuses at a flat 22% supplemental rate up to $1 million, which is often lower than the bracket a high earner actually lands in. If your marginal rate is above 22%, that bonus is underwithheld, and you make up the gap in April.
Jeff Judge often tells clients to recheck their W-4 after any life event: marriage, a new baby, a second job, a spouse returning to work, or a large raise. Each of these changes the math, and the form you filled out three years ago is probably wrong now. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Withholding sits squarely in the "Reassess and Refine" step, because it is something to revisit yearly, not set once and forget.
How Do I Stop Overpaying and Getting a Huge Refund?
To stop overpaying, reduce or remove any extra withholding in Step 4(c) and confirm you correctly claimed dependents in Step 3. A large refund means you withheld too much all year.
According to the IRS, the average federal refund runs into the thousands of dollars, and that is money you loaned the government at zero interest. If your refund last year was $3,000, that is roughly $250 a month you could have kept. The fix is straightforward: if you consistently get a four-figure refund and your situation hasn't changed, your W-4 is set to overwithhold. Dialing back Step 4(c) or correctly claiming Step 3 dependents brings the number down. Aim for a small refund or a small balance due, not a windfall in either direction. Jeff Judge notes: "A $3,000 refund sounds like a win until you realize you handed the IRS an interest-free loan all year — adjusting Step 4(c) on your W-4 puts that $250 a month back in your pocket where it belongs."
When you weigh whether to keep more per paycheck or hold a buffer, it helps to understand the difference between your What Is the Difference Between Marginal and Effective Tax Rate?. Your marginal rate determines how much a bonus or raise actually gets taxed, which is why Step 2 and Step 4 matter for higher earners. For households juggling equity compensation or multiple income sources, coordinating withholding with your broader plan is part of How can I potentially optimize my taxes as my income grows?.
Frequently Asked Questions
How often should I update my W-4?
Update your W-4 whenever a major life or income change happens, and review it at least once a year. Marriage, divorce, a new child, a second job, a spouse returning to work, or a significant raise all change your withholding math. Waiting until tax season means the correction comes too late to help the current year.
Can I claim exempt on my W-4?
You can claim exempt only if you had no federal tax liability last year and expect none this year. Most working adults do not qualify. Claiming exempt when you owe tax leads to a large balance due plus potential underpayment penalties from the IRS. Verify your eligibility carefully before checking that box.
What happens if I fill out my W-4 wrong?
Filling out your W-4 incorrectly results in either too much or too little tax withheld. Too little means you owe at tax time and may face an underpayment penalty. Too much means a large refund and less cash in each paycheck. You can submit a corrected W-4 to your employer at any time during the year.
Do I have to use the Multiple Jobs Worksheet?
You do not have to use the Multiple Jobs Worksheet specifically, but you must account for multiple jobs somehow. The W-4 gives three options in Step 2: the IRS estimator, the worksheet, or the checkbox in 2(c) for two similar-paying jobs. Choose whichever fits, but do not skip the step entirely.
Will a bigger W-4 withholding lower my taxes owed?
No, extra withholding does not lower your actual tax owed; it only prepays more of it. Your total tax is determined by your income, deductions, and credits, not by your withholding. Adjusting Step 4(c) changes timing and refund size, not the final tax bill itself.
Get the Full Tax Planning Picture
A W-4 is one piece of a larger tax strategy. If you found this helpful, our tax planning guide covers withholding, bracket management, and year-round tax moves in depth. Download it at chesapeakefp.com to make sure your paycheck and your plan are working together.
Want to go deeper? Our Tax-Smart Financial Plan walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


