

What Behavioral Biases Most Commonly Hurt Investment Decisions and How Do You Fix Them?
Last reviewed: July 2026
Behavioral biases investing mistakes come from predictable mental shortcuts: loss aversion, recency bias, confirmation bias, overconfidence, anchoring, herd mentality, and status quo bias. These biases push investors to sell low, chase performance, and ignore evidence that contradicts what they already believe. The fix is the same for all of them: build a written, rules-based process that makes the decision before emotion gets a vote.
Key Takeaways
- Loss aversion makes losses feel roughly twice as painful as equivalent gains, per research from Daniel Kahneman.
- The average investor underperformed the S&P 500 by 5.5 percentage points in 2023, largely due to poor timing decisions.
- A written investment policy statement is the single most effective tool for removing emotion from portfolio decisions.
- Behavioral biases affect everyone, including professionals; the goal is managing them with structure, not eliminating them.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate behavioral biases investing decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched smart, successful people lose more money to their own emotions than to any market crash, which is why he treats behavioral coaching as the core of real planning.
The biggest threat to your portfolio usually isn't the market. It's the person making the decisions. Investors who understand behavioral finance still fall into these traps, because knowing about a bias doesn't switch it off. What follows is a step-by-step way to catch the seven most damaging biases and fix each one before it costs you.
Step 1: Recognize Loss Aversion Before It Makes You Sell Low
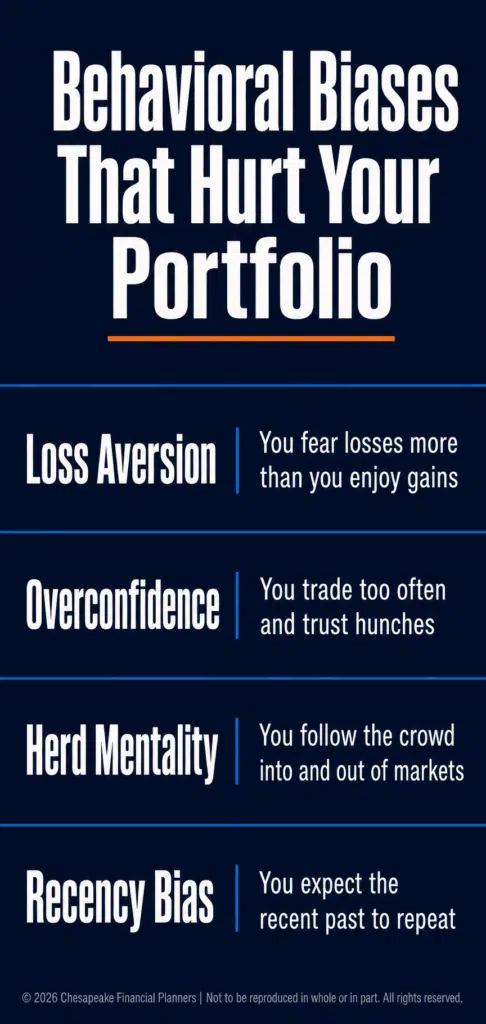
Loss aversion is the tendency to feel losses far more intensely than equivalent gains. Nobel laureate Daniel Kahneman found that the pain of losing roughly doubles the pleasure of an equal gain. In investing, this is the bias that makes people panic-sell during downturns and hold onto losing positions far too long, hoping to "break even."
The fix is mechanical. Decide your asset allocation in advance and write it down. When markets drop, you rebalance toward your target instead of fleeing to cash. Jeff often tells clients that the urge to sell during a crash is the most expensive feeling in finance. The investors who rebalanced into the March 2020 lows did far better than the ones who waited for things to "feel safe."
Step 2: Catch Recency Bias Before You Chase Performance
Recency bias is the habit of assuming the recent past will continue indefinitely. After a strong year, investors pile into whatever just won. After a bad year, they bail. According to DALBAR research, the average equity fund investor underperformed the S&P 500 by 5.5 percentage points in 2023, and chasing recent performance is the main reason.
The fix is a rebalancing schedule. Set a calendar reminder twice a year. Trim what has run up, add to what has lagged, and ignore the headlines telling you this time is different. A written rule beats a gut feeling every time. This is also why understanding Why Do Your Money Values Matter More Than Your Investment Choices? matters more than chasing the hot fund.
Step 3: Disarm Confirmation Bias by Seeking Disagreement
Confirmation bias is the tendency to seek out information that supports what you already believe and dismiss anything that contradicts it. An investor convinced a stock will soar reads only the bullish takes. The bearish case gets waved away. This is how people stay overweight a single position long past the point of reason.
The fix is uncomfortable but simple: actively look for the strongest argument against your position. Before buying or holding, write down what would have to be true for you to be wrong. If you can't make a credible bear case, you don't understand the investment well enough to own it in size.
Step 4: Check Overconfidence With Verifiable Numbers
Overconfidence is the bias that makes investors believe they can pick winners and time markets better than they actually can. Research consistently shows that frequent traders underperform buy-and-hold investors, largely because every trade carries costs and most trades are based on noise.
The fix is to track your actual results against a simple benchmark. If your stock-picking trails a low-cost index fund over three years, the data is telling you something. Jeff has watched clients argue with their own brokerage statements for years before accepting that a disciplined, diversified approach quietly outperformed their best ideas. Building strong What are the fundamentals of personal financial planning? removes the pressure to be a stock-picking genius.
Step 5: Break Anchoring by Reframing the Decision
Anchoring is the habit of fixating on an irrelevant reference point, usually the price you paid. "I'll sell when it gets back to what I paid for it" is anchoring in pure form. The market doesn't know or care what you paid. The only question that matters is whether you would buy this investment today at its current price.
The fix is to reframe every holding as a fresh decision. Ask: if I had this money in cash right now, would I buy this position at today's price? If the answer is no, the purchase price is just an anchor holding you back. A second set of eyes helps here, which is one reason What Does a Real Financial Review Actually Cover? includes a hard look at every position.
Step 6: Resist Herd Mentality by Following Your Plan
Herd mentality is the pull to do what everyone else is doing, whether that's piling into a meme stock or fleeing the market during a panic. The crowd feels safe. It rarely is. Most of the worst buying happens near tops and the worst selling near bottoms, precisely because the herd moves together.
The fix is a written investment policy statement that tells you what to own and when to rebalance, regardless of what's trending. When you have a plan, the crowd becomes background noise. Jeff puts it bluntly: the goal isn't to be smarter than the herd, it's to be more boring than the herd.
Step 7: Overcome Status Quo Bias With Scheduled Reviews
Status quo bias is the tendency to leave things as they are simply because changing requires effort. It's why people sit in a stale 401(k) allocation for a decade, hold a high-fee fund out of inertia, or never get around to building an How Much Should I Have in My Emergency Fund?. Doing nothing feels safe, but it's still a decision with consequences.
The fix is a recurring review built into your calendar. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. That final "Reassess and Refine" step exists specifically to override status quo bias before it quietly costs you years of growth. Jeff Judge notes: "A stale 401(k) allocation you haven't touched in ten years isn't a neutral choice — it's a decision you made by default, and we build the Reassess and Refine step into every client engagement specifically so that default never gets to run unchecked."
Frequently Asked Questions
What is the most damaging behavioral bias in investing?
Loss aversion is widely considered the most damaging behavioral bias because it drives investors to panic-sell during downturns and lock in losses. Research from Daniel Kahneman shows losses feel roughly twice as painful as equivalent gains, which leads to the most expensive mistake in investing: selling low.
Can you eliminate behavioral biases completely?
No, you cannot eliminate behavioral biases completely, because they are wired into how the human brain processes risk and reward. Even professional investors feel them. The realistic goal is to manage biases with structure, such as a written investment policy and a fixed rebalancing schedule that makes decisions before emotion takes over.
How does a written investment plan reduce bias?
A written investment plan reduces bias by deciding your asset allocation and rebalancing rules in advance, when you are calm and rational. When markets swing, you follow the plan instead of reacting to fear or greed. This single document neutralizes loss aversion, recency bias, herd mentality, and status quo bias at the same time.
What is recency bias and why does it cost investors money?
Recency bias is the assumption that recent performance will continue indefinitely, causing investors to chase winners and abandon losers at the wrong time. It costs money because it leads to buying high and selling low. DALBAR research shows the average equity investor underperformed the S&P 500 by 5.5 percentage points in 2023.
How can a financial advisor help with behavioral biases?
A financial advisor helps with behavioral biases by serving as an objective third party who enforces your plan when emotions run high. They build the written rules, run scheduled reviews, and talk you out of panic decisions during market drops. This behavioral coaching is often the most valuable service an advisor provides, well beyond investment selection.
Want to go deeper? Our R.U.D.D.E.R Audit for DIY Investors walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


